Water management company Advanced Drainage Systems (NYSE: WMS) missed Wall Street’s revenue expectations in calendar Q3 2026 (fiscal Q2 2027) as revenue rose 4.6% year on year to $889.4 million. The company’s full-year revenue guidance of $3.35 billion at the midpoint came in 3.1% below analysts’ consensus estimates. Its non-GAAP profit of $1.88 per share was 5.2% above analysts’ consensus estimates.
For more on Advanced Drainage, read the full research report for free.
Advanced Drainage (WMS) Q3 CY2026 highlights:
- Revenue $889.4 million vs S&P analysts’ consensus estimates of $925.7 million (4.6% year-on-year growth, 3.9% miss)
- Adjusted EPS $1.88 vs S&P analysts’ consensus estimates of $1.79 (5.2% beat)
- Adjusted EBITDA $286.8 million vs analysts’ consensus estimates of $284.2 million (32.2% margin, 0.9% beat)
- Revenue guidance The company lowered its revenue guidance for the full year to $3.35 billion at the midpoint from $3.45 billion, a 2.9% decrease
- EBITDA guidance $1.02 billion at the midpoint for the full year, below analysts’ consensus estimates of $1.05 billion
- Operating margin 21.9%, down from 26.3% in the same quarter last year
- Free cash flow margin 17.6%, down from 20.7% in the same quarter last year
- Market capitalization $10.86 billion
Scott Barbour, president and chief executive officer of ADS, commented, "Our second quarter results demonstrate the resilience of our business model and the team's ability to execute in a challenging demand environment. Net sales increased 4.6% to $889.4 million, including the contribution from NDS, and we generated Adjusted EBITDA of $286.8 million, resulting in an Adjusted EBITDA margin of 32.2%. Revenue in the second quarter was impacted by a larger than previously estimated pull forward of revenue into the first quarter. Looking back over the first half of fiscal year 2027, our performance was strong, with net sales up 12.5%, organic net sales up 2.3% and Adjusted EBITDA up 14.0%. The first half Adjusted EBITDA margin of 34.1% represents the highest first half profitability in the Company’s history."
Revenue growth
A company’s long-term revenue performance is one signal of its overall quality. Even a poor business can perform well for one or two quarters, but a high-quality one grows for years. Advanced Drainage’s revenue grew at a mediocre 7.2% compounded annual growth rate over the last five years, falling short of the industrials sector standard.
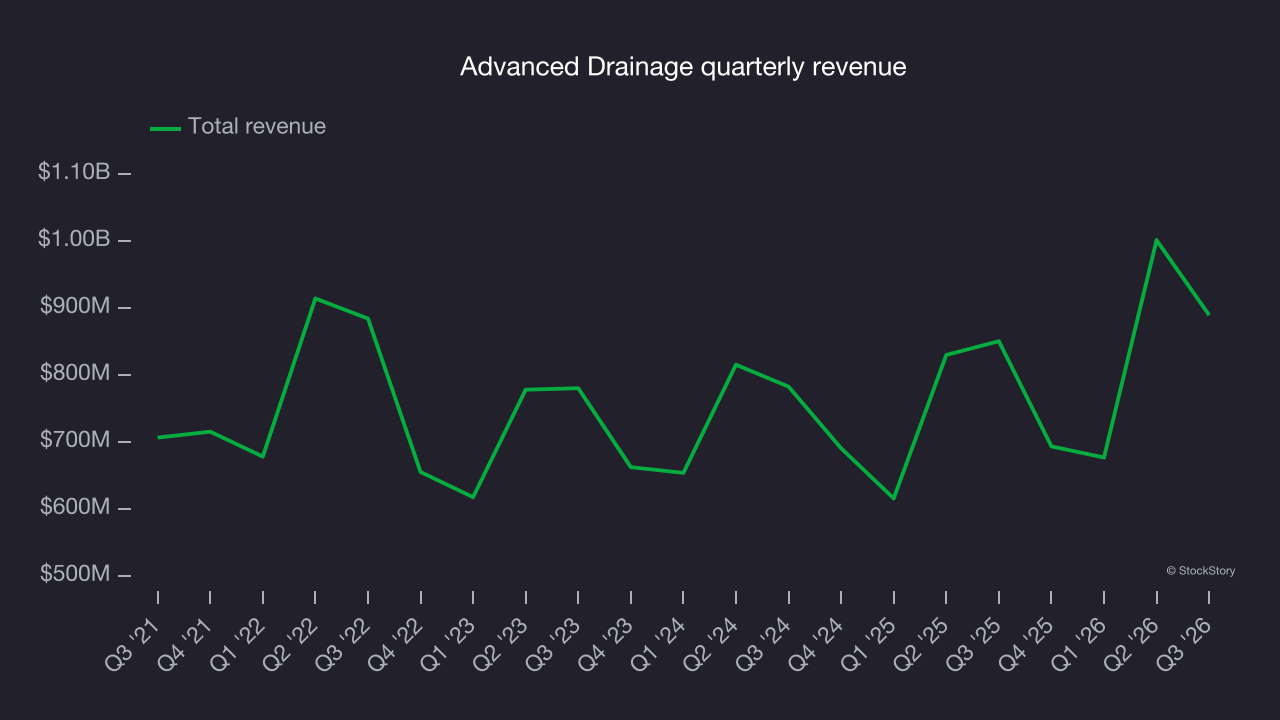
Long-term growth is the most important, but within industrials, a half-decade historical view may miss new industry trends or demand cycles. Advanced Drainage’s recent performance shows its demand has slowed as its annualized revenue growth of 5.8% over the last two years was below its five-year trend. Decelerating revenue growth in the sector is a concern, as it could signal changing consumer tastes aided by low switching costs. 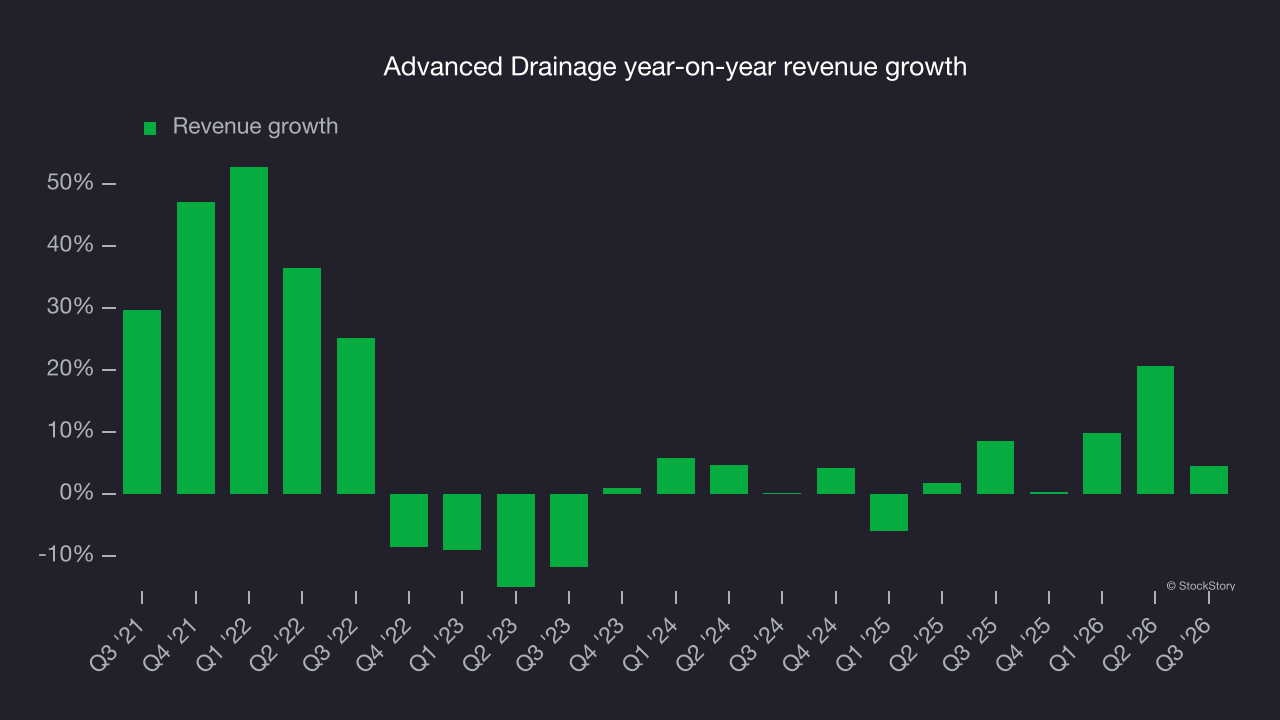
A closer look at the company’s most important segments, Pipe and Infiltrators, offers more detail on its revenue dynamics. These segments account for 80.1% and 19.9% of revenue. Over the last two years, Advanced Drainage’s Pipe revenue (thermoplastic corrugated pipes) averaged 48.9% year-on-year growth while its Infiltrators revenue (wastewater treatment systems) averaged 31.4% growth. 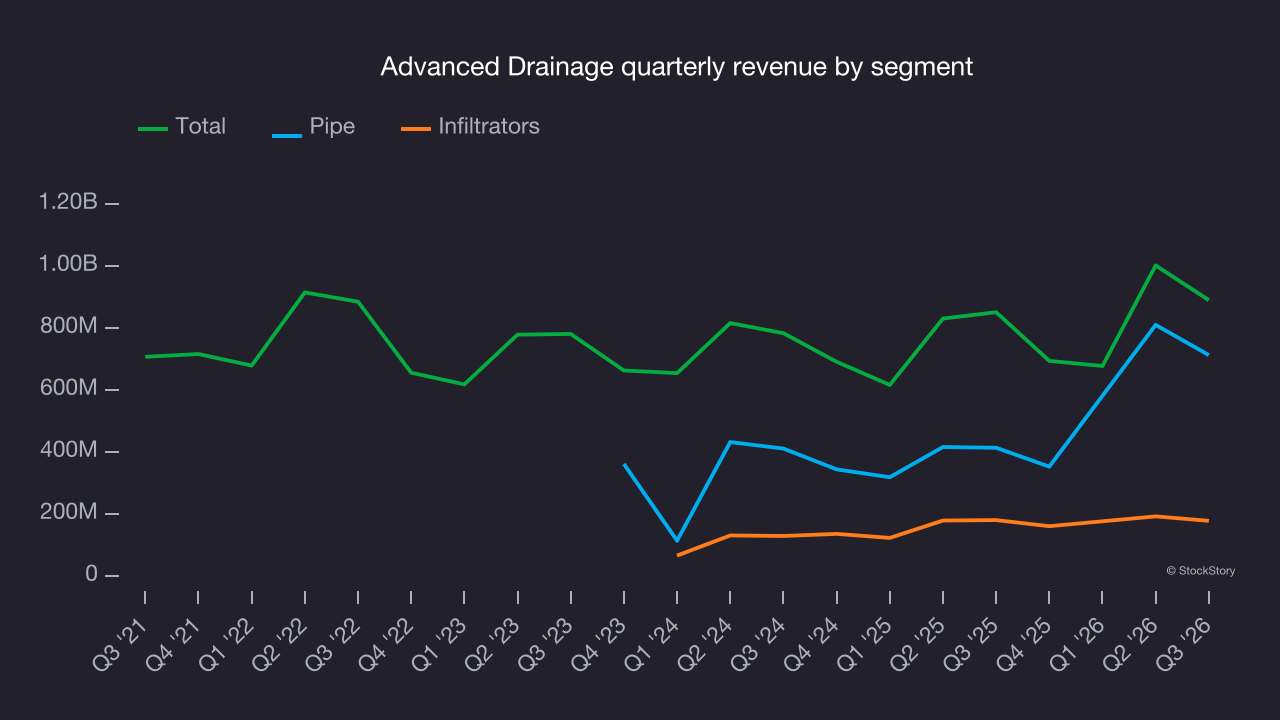
This quarter, Advanced Drainage’s revenue grew by 4.6% year on year to $889.4 million, falling short of Wall Street’s consensus estimates.
Looking ahead, sell-side analysts expect revenue to grow 9.4% over the next 12 months, according to S&P, an improvement versus the last two years. This is a solid growth outlook and implies its newer products and services will spur better revenue performance.
Operating margin
Advanced Drainage has performed well over the last five years. It demonstrated high profitability for an industrials business, with an average operating margin of 22.2%. That result is unsurprising given its favorable gross margin baseline.
Looking at the trend in its profitability, Advanced Drainage’s operating margin decreased by 1.1 percentage points over the last five years. This raises questions about the company’s expense base because its revenue growth should have given it leverage on its fixed costs, resulting in better economies of scale and profitability.
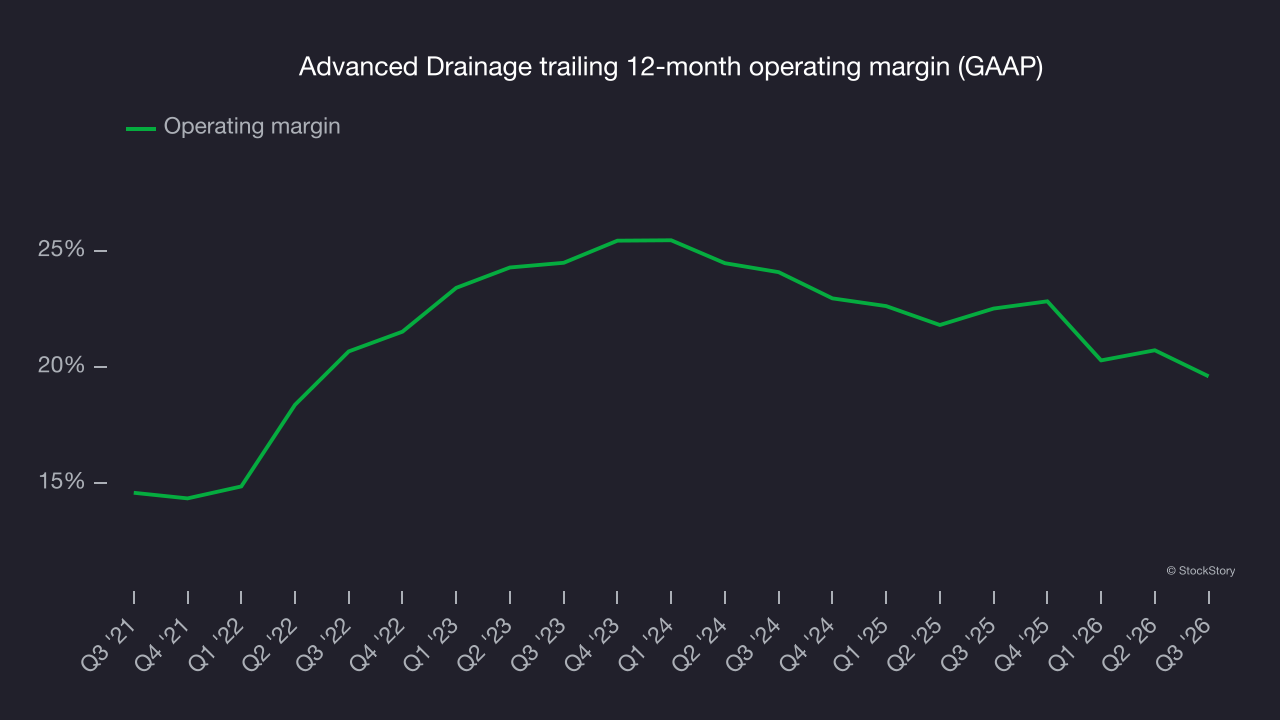
In Q3, Advanced Drainage generated an operating margin of 21.9%, down 4.3 percentage points year on year. Advanced Drainage’s operating margin decreased more than its gross margin, suggesting it was less efficient because expenses such as marketing, R&D and administrative overhead increased.
Earnings per share
We track the long-term change in earnings per share, or EPS, for the same reason as long-term revenue growth. Compared to revenue, however, EPS highlights whether a company’s growth is profitable.
Advanced Drainage’s EPS grew at a 12.5% compounded annual growth rate over the last five years, higher than its 7.2% annualized revenue growth. This indicates the company became more profitable on a per-share basis as it expanded.
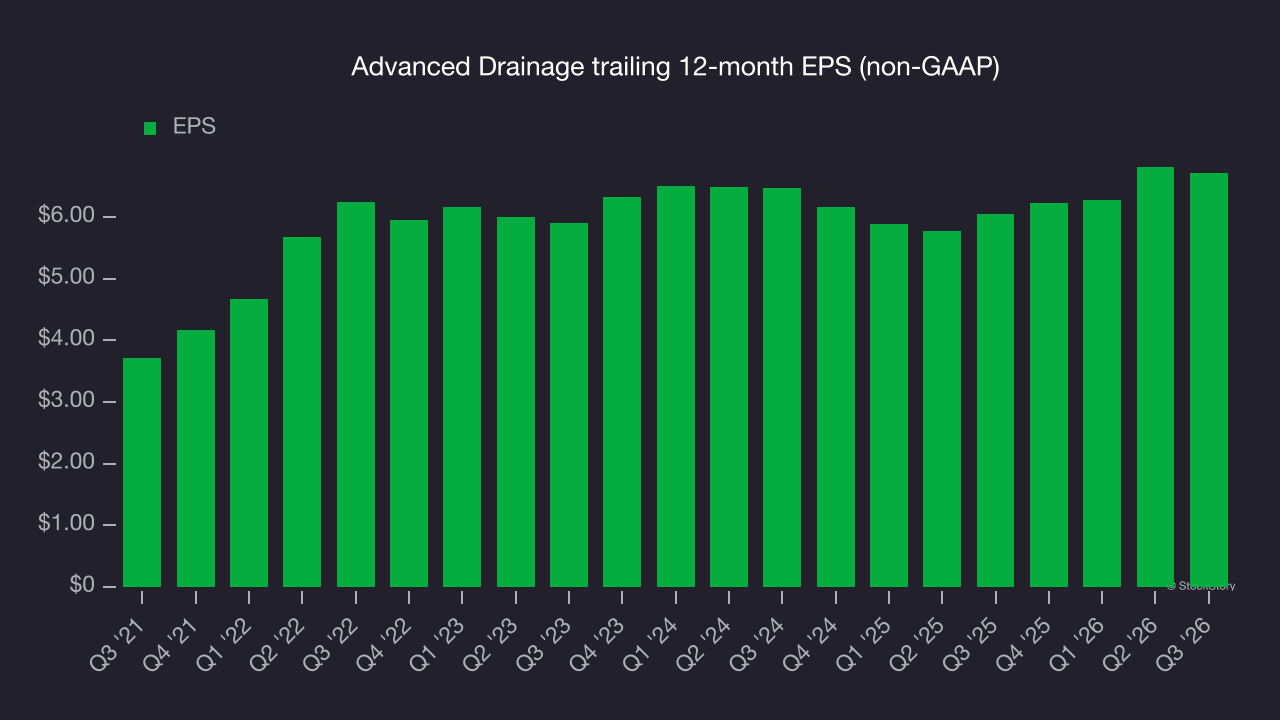
As with revenue, we analyze EPS over a more recent period because it can provide insight into an emerging theme or development for the business.
For Advanced Drainage, its two-year annual EPS growth of 1.8% was lower than its five-year trend.
In Q3, Advanced Drainage reported adjusted EPS of $1.88, down from $1.98 in the same quarter last year. Despite falling year on year, EPS beat analysts’ consensus estimates by 5.2%. Over the next 12 months, Wall Street expects Advanced Drainage’s full-year EPS to stay about the same, moving from $6.71 to $6.69, according to S&P.
Key takeaways from Advanced Drainage’s Q3 results
Advanced Drainage’s quarter could have been better: Revenue fell short of Wall Street’s consensus estimates, and full-year revenue guidance also missed expectations. EPS beat analysts’ consensus estimates and EBITDA narrowly topped Wall Street’s consensus, but those positives left the results mixed. Shares tumbled 8.4% to $132.04 immediately after the report.
Advanced Drainage may have had a tough quarter, but assessing whether the stock offers an investment opportunity requires a broader view. The latest quarter matters, but longer-term business quality and valuation matter more when deciding whether to invest. For more on those factors, read our full research report here (it’s free).