Online work marketplace Upwork (NASDAQ: UPWK) announced better-than-expected revenue in Q3 2026, but revenue tumbled 8% year on year to $185.6 million. Revenue guidance for the full year exceeded analysts’ consensus estimates, but next quarter’s guidance of $173 million was less impressive, coming in 1% below expectations. Its non-GAAP profit of $0.40 per share was 27.4% above analysts’ consensus estimates.
For more on Upwork, read our free full research report.
Upwork (UPWK) Q3 2026 highlights:
- Revenue $185.6 million vs S&P analysts’ consensus estimates of $180.2 million (8% year-on-year decline, 3% beat)
- Adjusted EPS $0.40 vs S&P analysts’ consensus estimates of $0.31 (27.4% beat)
- Adjusted EBITDA $63.79 million vs analysts’ consensus estimates of $52.39 million (34.4% margin, 21.8% beat)
- Revenue guidance $173 million at the midpoint for Q4 2026, below analysts’ consensus estimates of $174.7 million
- Adjusted EPS guidance Management raised its full-year adjusted EPS guidance to $1.46 at the midpoint, a 3.9% increase
- EBITDA guidance $238 million at the midpoint for the full year, above analysts’ consensus estimates of $229.5 million
- Operating margin 18.6%, up from 14.8% in the same quarter last year
- Free cash flow margin 29%, up from 18.8% in the previous quarter
- Market capitalization $1.14 billion
"In the third quarter, Upwork executed strongly as our strategic growth pillars continued to gain momentum," said Hayden Brown, president and CEO of Upwork Inc. "We are doubling down on our enterprise strategy with Lifted’s acquisition of WorkMotion, a leading Berlin-based EOR, to capture growing global demand. At the same time, the launch of Upwork’s MCP server is opening our marketplace to AI agents as a new class of client, and today we launched Upwork Now so clients can find talent to start work right away. Both mark a transformational shift toward making Upwork a capability wherever work begins. Combined with continued growth of our higher-margin products and high-value customers, we’re well positioned to capture new opportunities while continuing to drive strong, profitable growth."
Revenue growth
Examining a company’s long-term performance can provide clues about its quality. Any business can put up a good quarter or two, but many enduring ones grow for years. Upwork’s revenue grew at a sluggish 5% compounded annual growth rate over the last three years, falling short of our standard for the consumer internet sector.
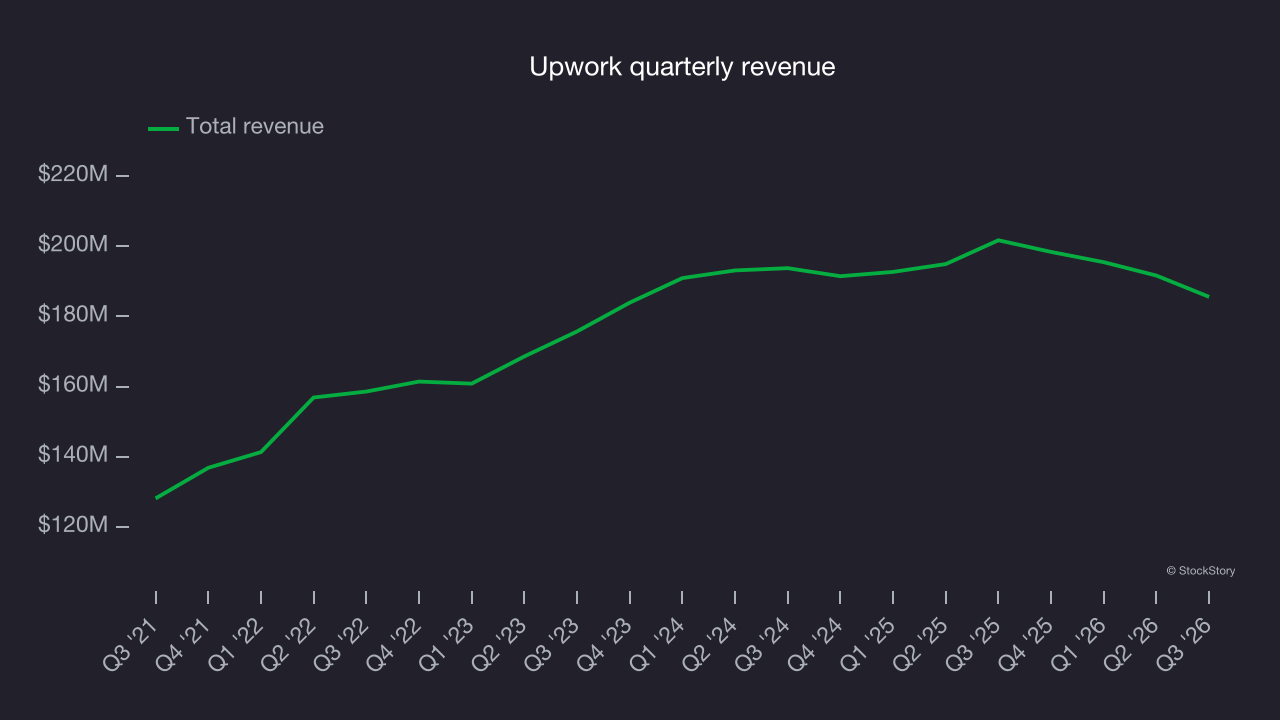
This quarter, Upwork’s revenue fell by 8% year on year to $185.6 million but beat Wall Street’s consensus estimates by 3%. Management is guiding for a 12.8% year-on-year decline in revenue next quarter.
Looking further ahead, sell-side analysts expect revenue to decline by 6.3% over the next 12 months, according to S&P, a deceleration versus the last three years. This uninspiring outlook suggests its products and services will face some demand challenges.
Free cash flow
Free cash flow matters because cash, not accounting profits, pays the bills.
Upwork has shown strong cash profitability, driven by its lucrative business model and cost-effective customer acquisition strategy that enable it to stay ahead of the competition through investments in new products rather than sales and marketing. The company’s free cash flow margin was among the best in the consumer internet sector, averaging 23.2% over the last two years.
Upwork’s margin expanded by 16.5 percentage points over the last few years. That is a positive development because it gives the company more flexibility.
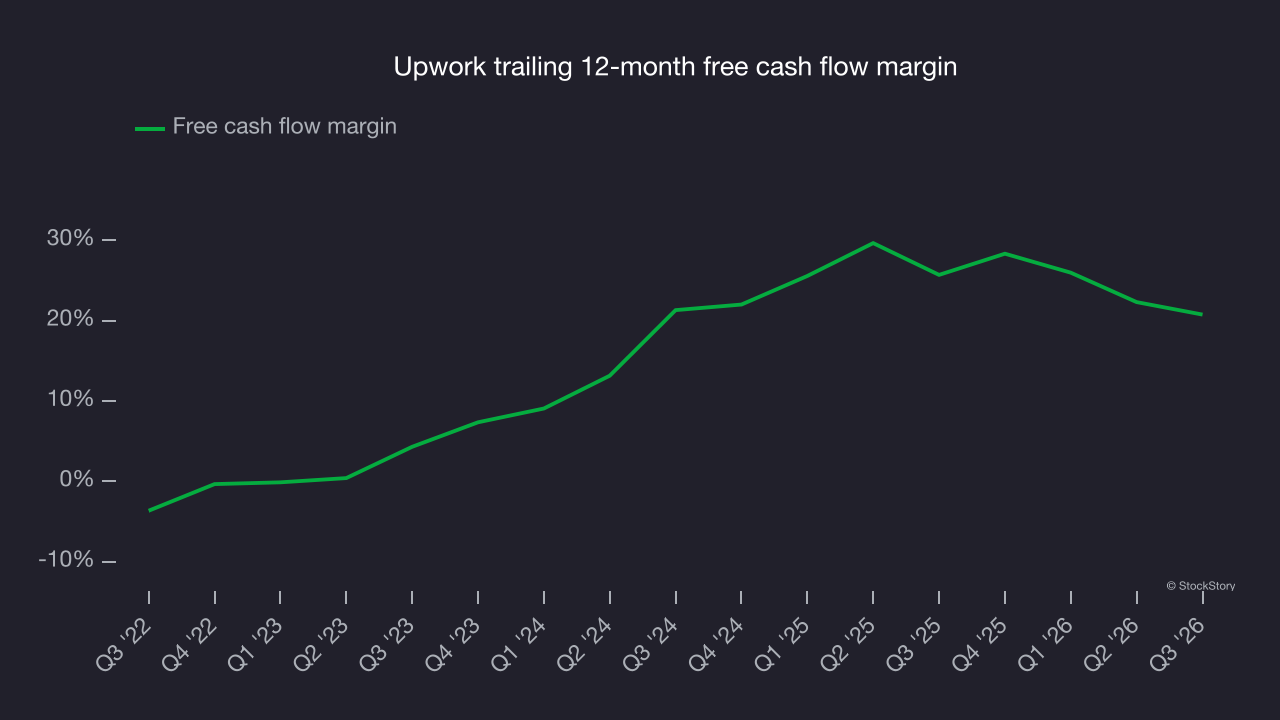
Upwork’s free cash flow came in at $53.85 million in Q3, equivalent to a 29% margin. The company’s cash profitability declined, with its margin 5.4 percentage points lower than in the same quarter last year, but still above its two-year average. The quarter’s decline should not carry too much weight because investment needs can be seasonal, causing short-term swings. Long-term trends matter more than temporary fluctuations.
Key takeaways from Upwork’s Q3 results
We were impressed by how significantly Upwork blew past analysts’ EBITDA expectations this quarter. We were also glad its full-year EBITDA guidance trumped Wall Street’s estimates. On the other hand, its revenue guidance for next quarter slightly missed. Zooming out, we still think this was a decent quarter. The stock traded up 14.6% to $11.16 immediately following the results.
For investors considering Upwork, the latest quarter is only one piece of the longer-term business quality picture. Quality, when combined with valuation, can help determine if the stock is a buy. For more on Upwork, read the full research report here (it’s free).