Electrical supply company WESCO (NYSE: WCC) reported revenue ahead of Wall Street’s expectations in Q3 2026, with revenue up 16.6% year on year to $7.23 billion. Its non-GAAP profit of $5.77 per share was 23% above analysts’ consensus estimates.
For more on WESCO, read our free full research report.
WESCO (WCC) Q3 2026 highlights:
- Revenue $7.23 billion vs S&P analysts’ consensus estimates of $6.88 billion (16.6% year-on-year growth, 5.1% beat)
- Adjusted EPS $5.77 vs S&P analysts’ consensus estimates of $4.69 (23% beat)
- Adjusted EBITDA $561.5 million vs analysts’ consensus estimates of $491.7 million (7.8% margin, 14.2% beat)
- Operating margin 6.2%, in line with the same quarter last year
- Free cash flow $164.8 million, up from -$89.3 million in the same quarter last year
- Organic revenue rose 16.6% year on year (beat)
- Market capitalization $16.92 billion
"We are very pleased with our record third quarter results and carry positive business momentum into the fourth quarter. Once again, sales, backlog, operating profit, and earnings per share all increased double digits versus the prior year and achieved records that exceeded our expectations. We are particularly pleased with our free cash flow generation during the quarter which was strong given the sales growth we delivered. The past five consecutive quarters of double-digit sales growth demonstrate Wesco's higher growth profile which extends well beyond our important data center positioning. Customer demand is strong across the rest of our diversified portfolio and end markets, with sales up high single-digits excluding data centers. Our customers continue to invest in major capital and infrastructure projects and increasingly rely on Wesco to manage their needs as we add more services to our portfolio and demonstrate the continued effectiveness of our One Wesco cross-selling strategy. Especially noteworthy, our backlog was up over 80%, to a new record level for each of our three business units," said John Engel, Chairman, President and CEO.
Revenue growth
A company’s long-term revenue performance can indicate its overall quality. Any business can have short-term success, but a top-tier one grows for years. WESCO’s revenue grew at a decent 8.3% compounded annual growth rate over the last five years. Its growth was slightly above the average industrials company and shows its offerings resonate with customers.
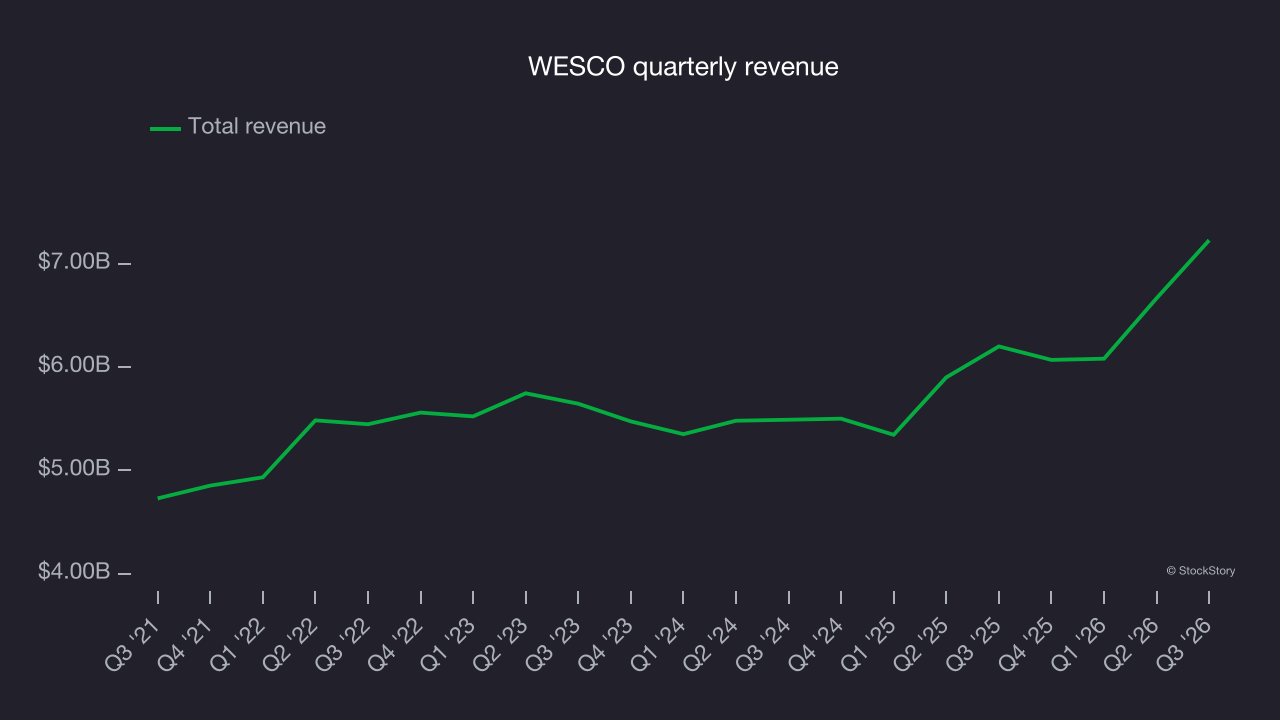
Long-term growth is the most important, but within industrials, a half-decade historical view may miss new industry trends or demand cycles. WESCO’s annualized revenue growth of 9.3% over the last two years is above its five-year trend, suggesting its demand recently accelerated. 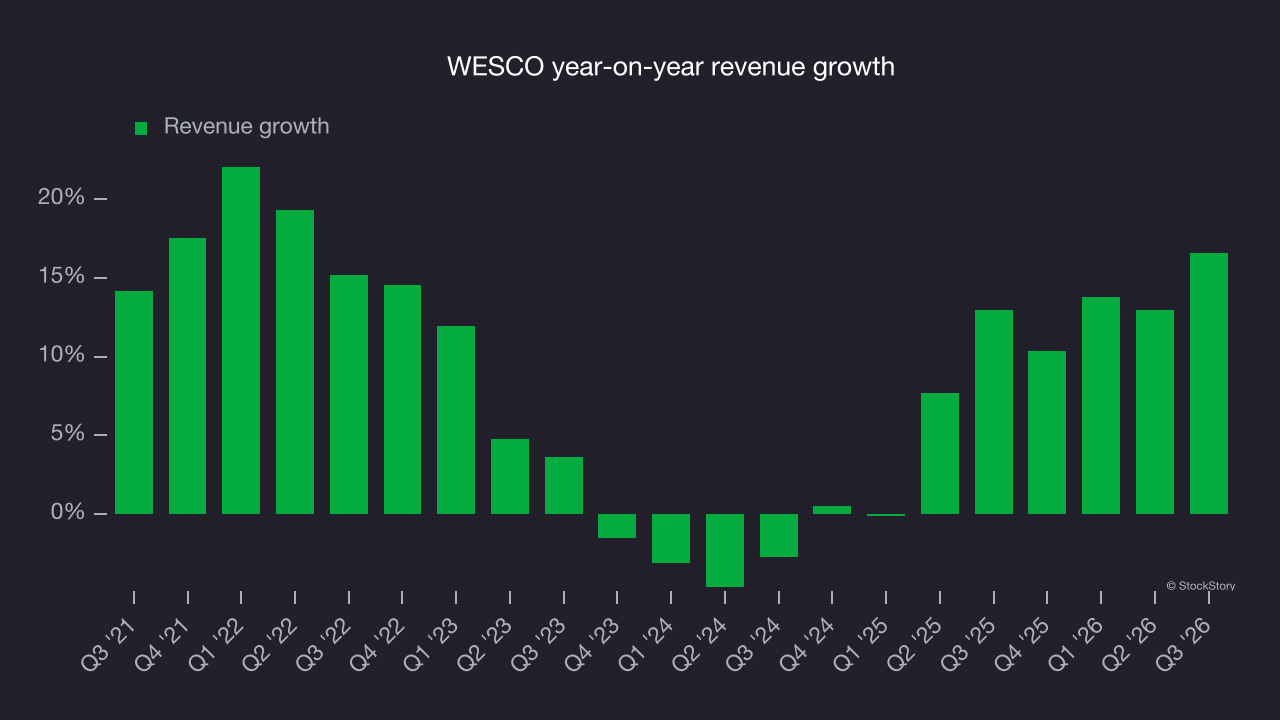
WESCO also reports organic revenue, which strips out one-time events like acquisitions and currency fluctuations that don’t accurately reflect its fundamentals. Over the last two years, WESCO’s organic revenue averaged 9.8% year-on-year growth. That was in line with its two-year revenue growth, indicating that core operations, rather than acquisitions and divestitures, drove most of its results. 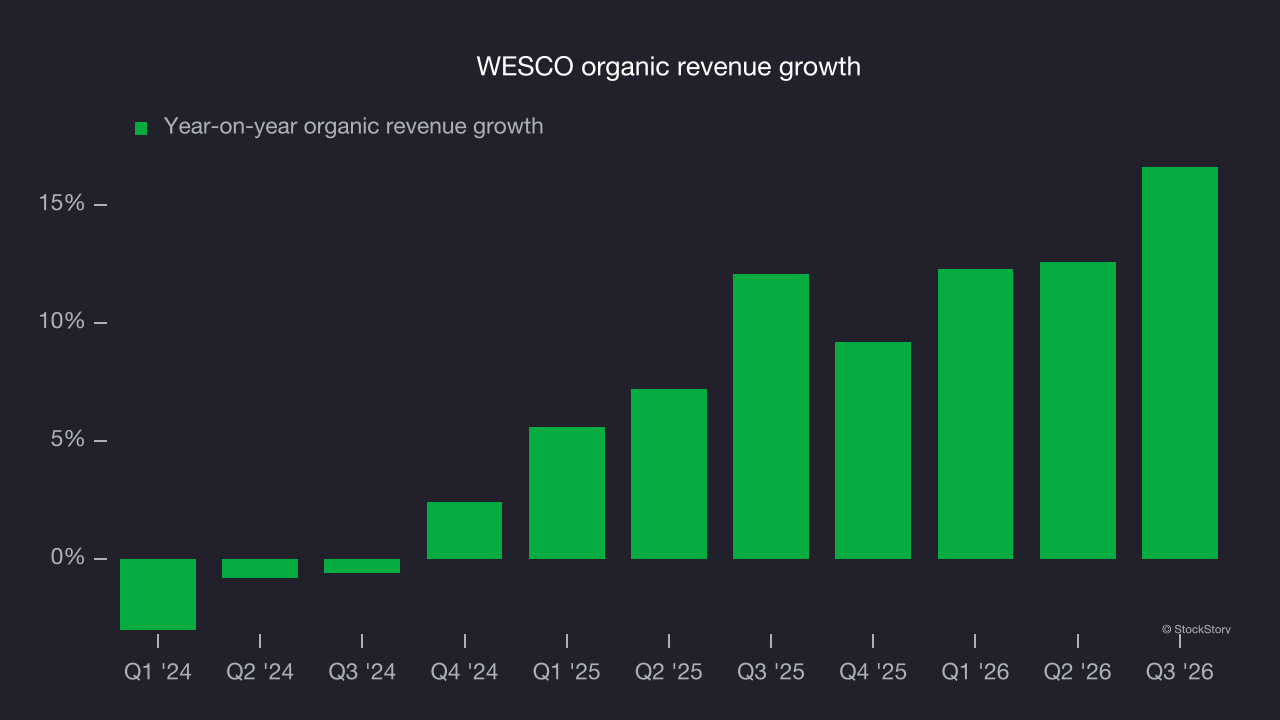
This quarter, WESCO reported year-on-year revenue growth of 16.6%, and its $7.23 billion of revenue exceeded Wall Street’s consensus estimates by 5.1%.
Looking ahead, sell-side analysts expect revenue to grow 5.5% over the next 12 months, according to S&P, a deceleration versus the last two years. That underwhelming projection implies its products and services will see some demand headwinds.
Operating margin
WESCO’s operating margin has generally stayed the same over the last 12 months, averaging 5.8% over the last five years. This profitability was poor for an industrials business, driven by its suboptimal cost structure and low gross margin.
Analyzing the trend in its profitability, WESCO’s operating margin might have fluctuated slightly but has generally stayed the same over the last five years. This raises questions about the company’s expense base because its revenue growth should have given it leverage on its fixed costs, resulting in better economies of scale and profitability.
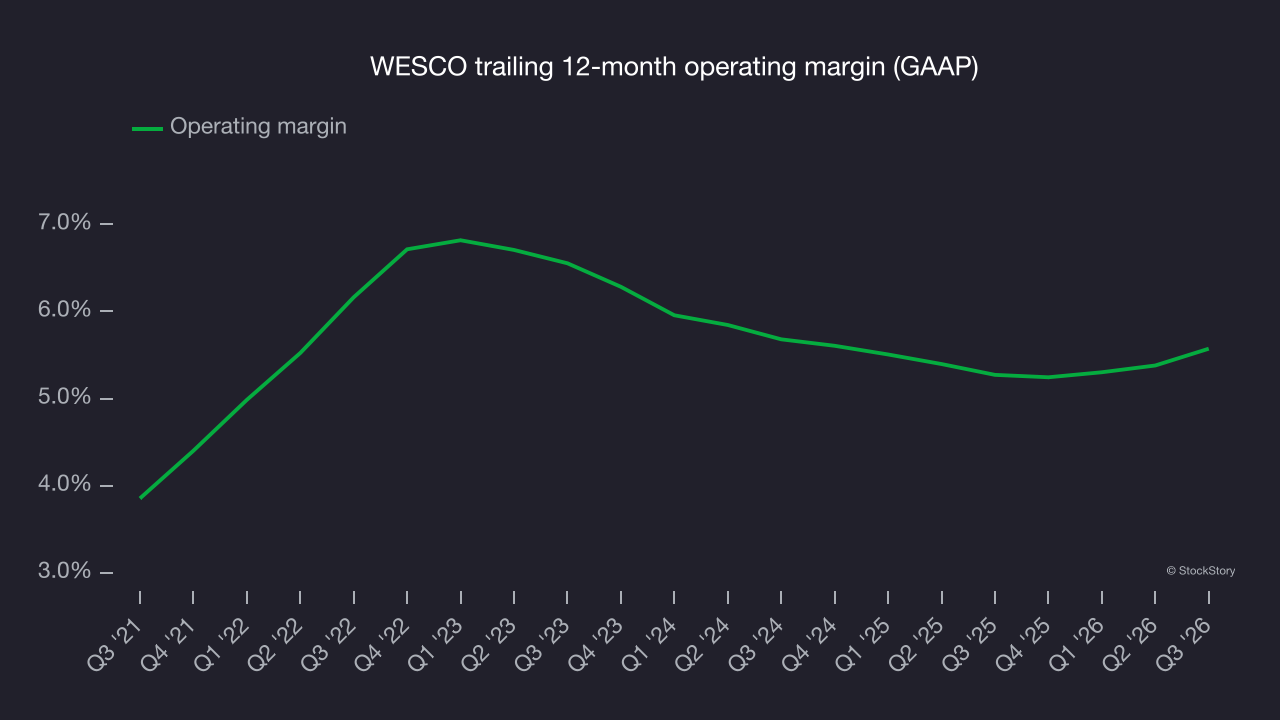
This quarter, WESCO generated an operating margin of 6.2%, in line with the same quarter last year. This indicates the company’s cost structure has recently been stable.
Earnings per share
Revenue trends explain a company’s historical growth, but the long-term change in earnings per share (EPS) points to the profitability of that growth. For example, a company could inflate its revenue through excessive spending on advertising and promotions.
WESCO’s EPS grew at a 16.3% compounded annual growth rate over the last five years, higher than its 8.3% annualized revenue growth. This tells us the company became more profitable on a per-share basis as it expanded.
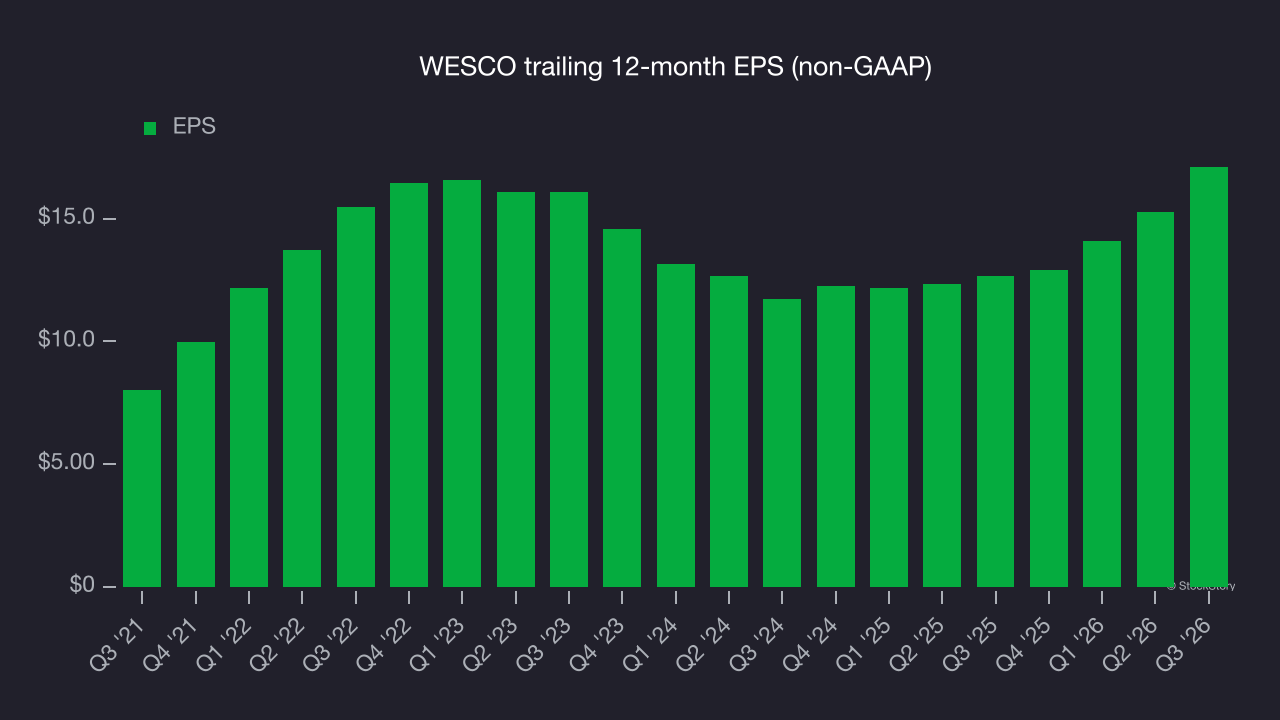
Examining WESCO’s quality of earnings helps explain its performance. A five-year view shows that WESCO has repurchased its stock, shrinking its share count by 5.3%. This indicates its EPS outperformed its revenue not because of increased operational efficiency but financial engineering, as buybacks boost per share earnings. 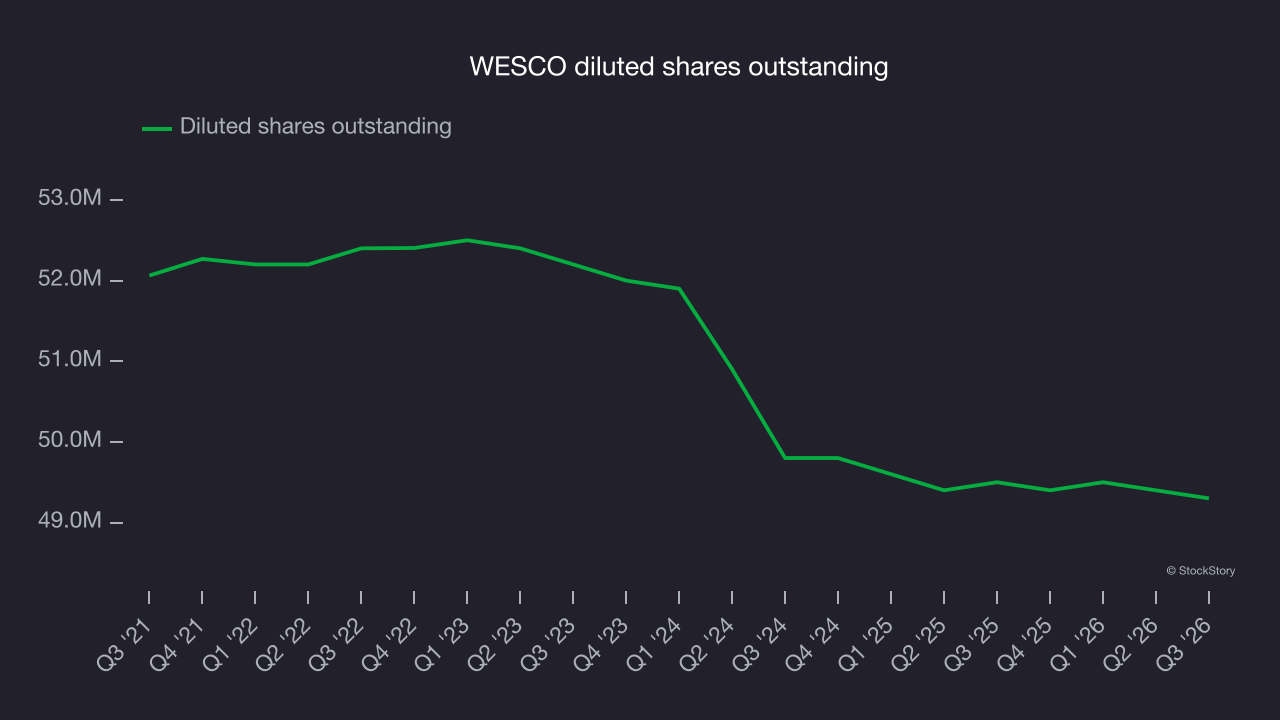
As with revenue, we analyze EPS over a more recent period because it can provide insight into an emerging theme or development for the business.
For WESCO, its two-year annual EPS growth of 20.7% was higher than its five-year trend. That acceleration is a positive sign, particularly given the already high growth rate.
In Q3, WESCO reported adjusted EPS of $5.77, up from $3.92 in the same quarter last year. EPS comfortably beat analysts’ consensus estimates, a positive result for shareholders. Over the next 12 months, Wall Street expects WESCO’s full-year EPS to grow 12.9% from $17.11 to $19.32, according to S&P.
Key takeaways from WESCO’s Q3 results
WESCO delivered some important positives this quarter, with organic revenue well above analysts’ consensus estimates and EBITDA also beating Wall Street’s estimates by a wide margin. Shares surged 6.7% to $370.39 immediately after the report.
WESCO had a solid quarterly earnings result, but whether the stock is a good investment depends on more than that. The latest quarter matters, but not as much as longer-term business quality and valuation when deciding whether to invest in this stock. For more on WESCO, read the full research report here (it’s free).