Enterprise workflow automation company ServiceNow (NYSE: NOW) met Wall Street’s revenue expectations in Q3 2026, with revenue up 20.5% year on year to $4.11 billion. Its non-GAAP profit of $1 per share was 2.3% below analysts’ consensus estimates.
For more on ServiceNow, read the full research report for free.
ServiceNow (NOW) Q3 2026 highlights:
- Revenue $4.11 billion vs S&P analysts’ consensus estimates of $4.10 billion (20.5% year-on-year growth, in line)
- Adjusted EPS $1 vs S&P analysts’ consensus estimates of $1.02 (2.3% miss)
- Adjusted operating income $1.34 billion vs analysts’ consensus estimates of $1.28 billion (32.6% margin, 4.8% beat)
- Operating margin 9.4%, down from 16.8% in the same quarter last year
- Free cash flow margin 20%, up from 15.9% in the previous quarter
- Billings $3.64 billion at quarter end, up 23.2% year on year (miss)
- Market capitalization $160 billion
“This was more than another beat-and-raise quarter for ServiceNow, this was the inflection point for ServiceNow as the Super Intelligence Control Tower,” said ServiceNow Chairman and CEO Bill McDermott. “Our customers have validated our strategic relevance as the single harness for enterprise intelligence and security. The Control Tower is the elixir that simplifies tech debt, limits token overload and manages unprecedented cybersecurity risk. That’s why AI adoption is accelerating, surging our hybrid business model to $30 billion in RPO, growing 23 percent. What other company at the forefront of the agentic enterprise has no capital or compute constraints? This is a one-of-one, rule of 571 growth company firing on all cylinders.”
Revenue growth
A company’s long-term performance is an indicator of its overall quality. Any business can have short-term success, but a top-tier one grows for years. Over the last five years, ServiceNow grew its revenue at a solid 22.8% compounded annual growth rate. Its growth surpassed that of the average software company and shows its offerings resonate with customers.
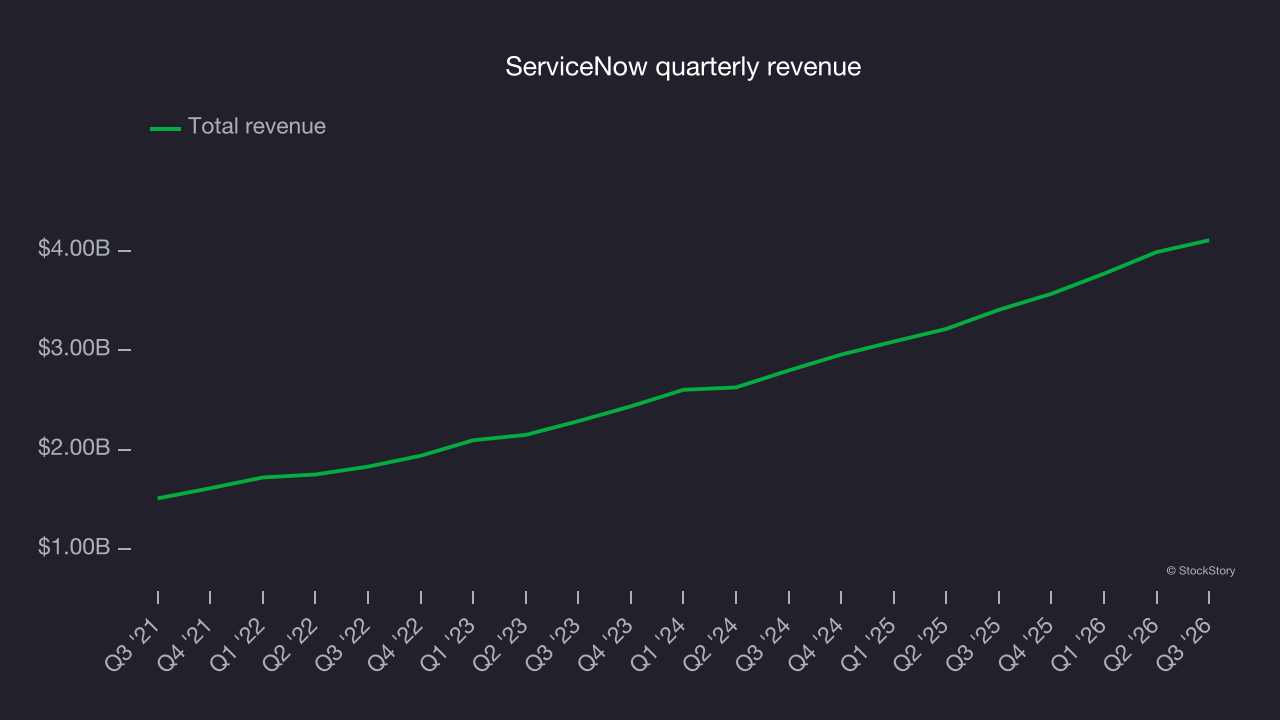
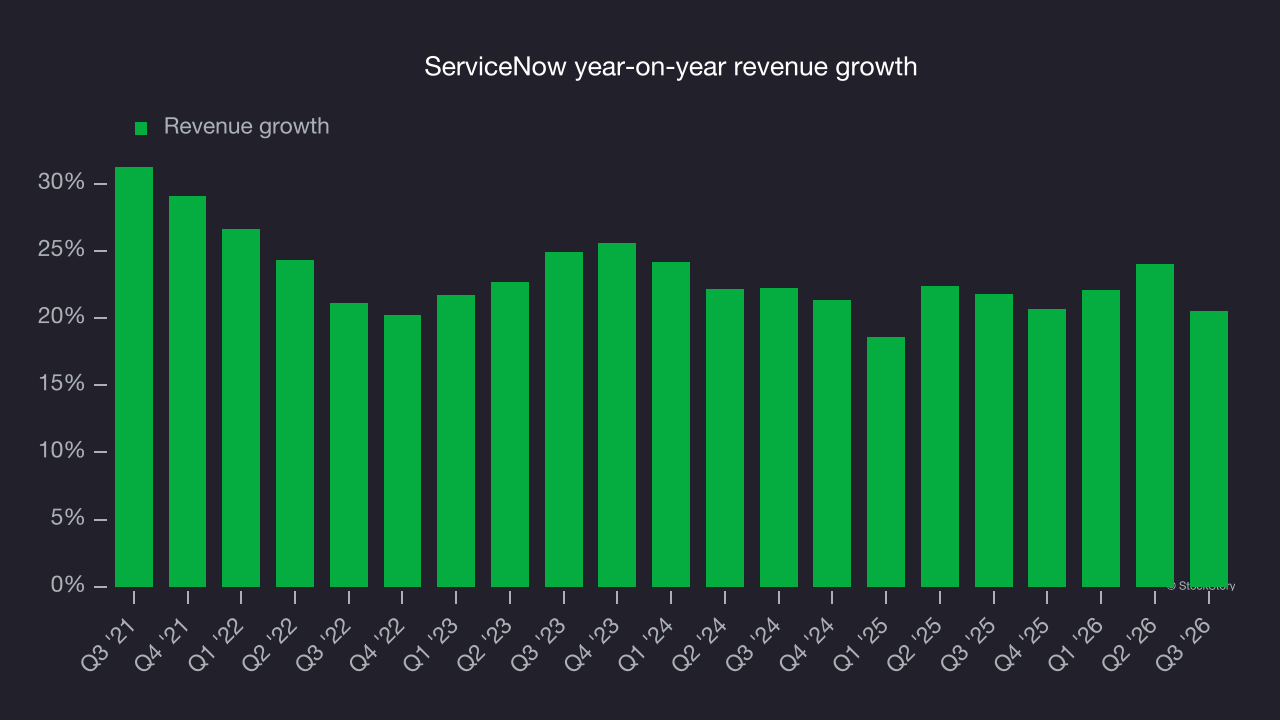
This quarter, ServiceNow’s year-on-year revenue growth of 20.5% was strong, and its $4.11 billion of revenue was in line with Wall Street’s consensus estimates.
Looking ahead, sell-side analysts expect revenue to grow 19.5% over the next 12 months, according to S&P, a slight deceleration versus the last two years. Its growth trajectory remains attractive given its scale and suggests the market sees success for its products and services.
Billings
Billings is a non-GAAP metric that is often called “cash revenue” because it shows how much money the company has collected from customers in a certain period. This is different from revenue, which must be recognized in pieces over the length of a contract.
ServiceNow’s billings totaled $3.64 billion in Q3, and over the last four quarters, growth was strong, averaging 22.2% year on year. This performance aligned with its total revenue growth, indicating healthy customer demand. The high level of cash collected from customers also supports liquidity and capacity for future investment and growth.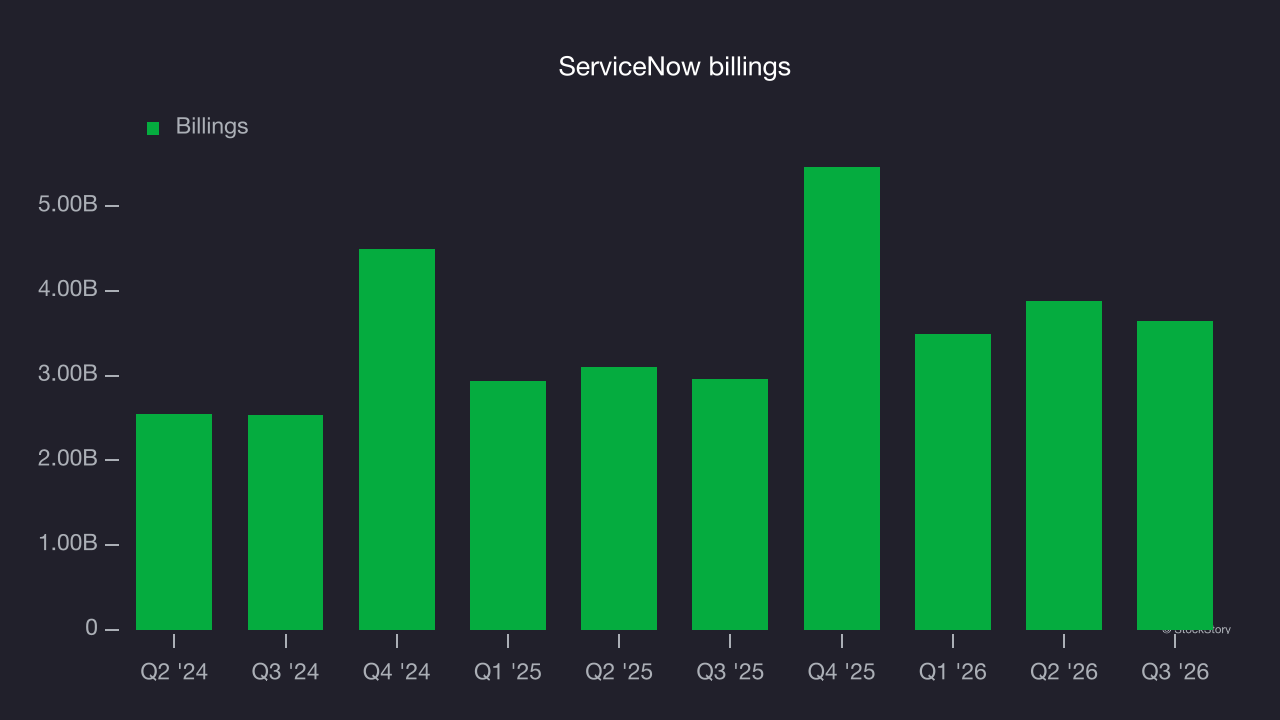
Customer acquisition efficiency
The customer acquisition cost (CAC) payback period represents the months required to recover the cost of acquiring a new customer. Essentially, it’s the break-even point for sales and marketing investments. A shorter CAC payback period is ideal, as it implies better returns on investment and business scalability.
ServiceNow is efficient at acquiring new customers, and its CAC payback period was 30.3 months this quarter. The company’s rapid recovery of its customer acquisition costs indicates it has a strong brand reputation due to its scale, giving it more resources to pursue new product initiatives while maintaining the flexibility to increase its sales and marketing investments.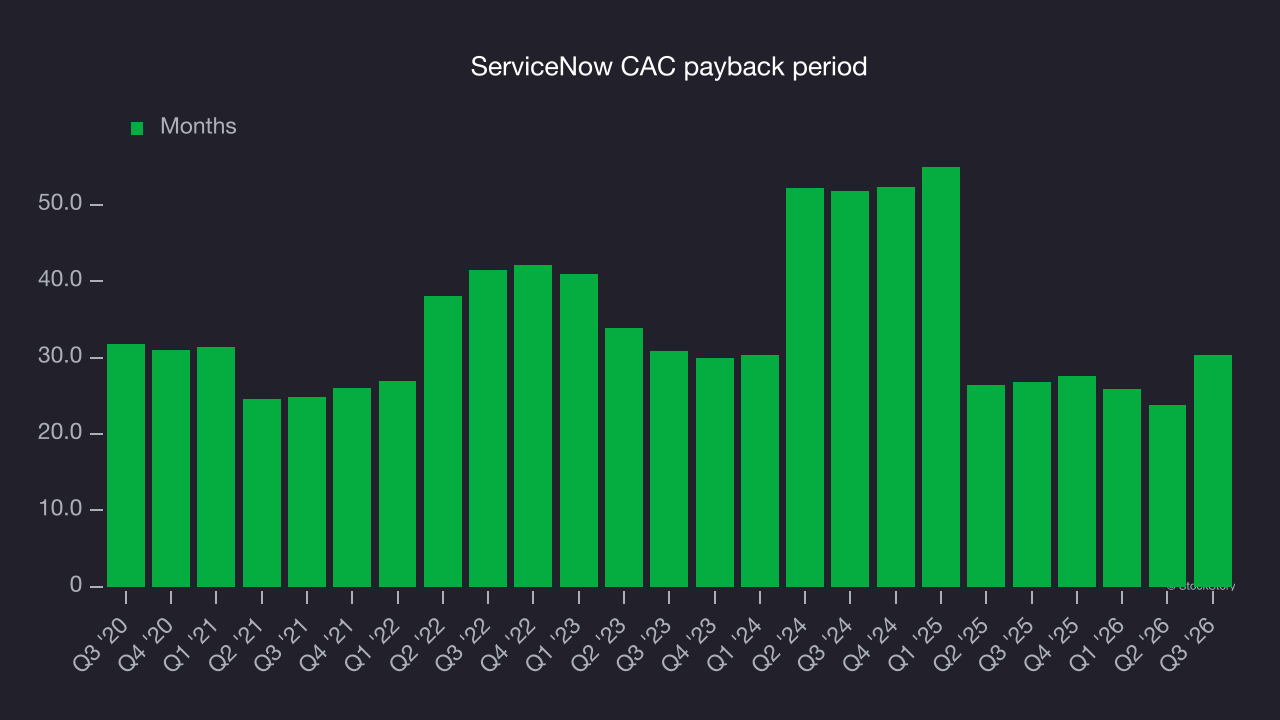
Key takeaways from ServiceNow’s Q3 results
We enjoyed seeing ServiceNow beat analysts’ adjusted operating income expectations this quarter. However, revenue was just in line and billings missed. Overall, this quarter was not good enough for a stock where there is skepticism around how AI could disrupt the company. The stock traded down 17.2% to $124.46 immediately following the results.
Is ServiceNow a buy at its current price? The latest quarter is only one part of assessing its longer-term business quality. Business quality, combined with valuation, can help determine whether the stock is a buy. For more on ServiceNow, read our full research report here (it’s free).