Oilfield equipment manufacturer Cactus (NYSE: WHD) met Wall Street’s revenue expectations in Q3 2026, with revenue up 63.2% year on year to $430.9 million. Its non-GAAP profit of $0.96 per share was 24% above analysts’ consensus estimates.
For more on Cactus, read the full research report for free.
Cactus (WHD) Q3 2026 highlights:
- Revenue $430.9 million vs S&P analysts’ consensus estimates of $431.6 million (63.2% year-on-year growth, in line)
- Adjusted EPS $0.96 vs S&P analysts’ consensus estimates of $0.77 (24% beat)
- Adjusted EBITDA $132 million vs analysts’ consensus estimates of $121.2 million (30.6% margin, 9% beat)
- Operating margin 21.8%, down from 23.2% in the same quarter last year
- Market capitalization $4.57 billion
Revenue growth
Cyclical sectors like energy often flatter weaker operators during favorable price environments, but a longer-term lens separates those from businesses that can consistently perform across market cycles. Cactus’s 32.3% annualized revenue growth over the last five years was strong. Its growth beat the average energy upstream and integrated energy company and shows its offerings resonate with customers.
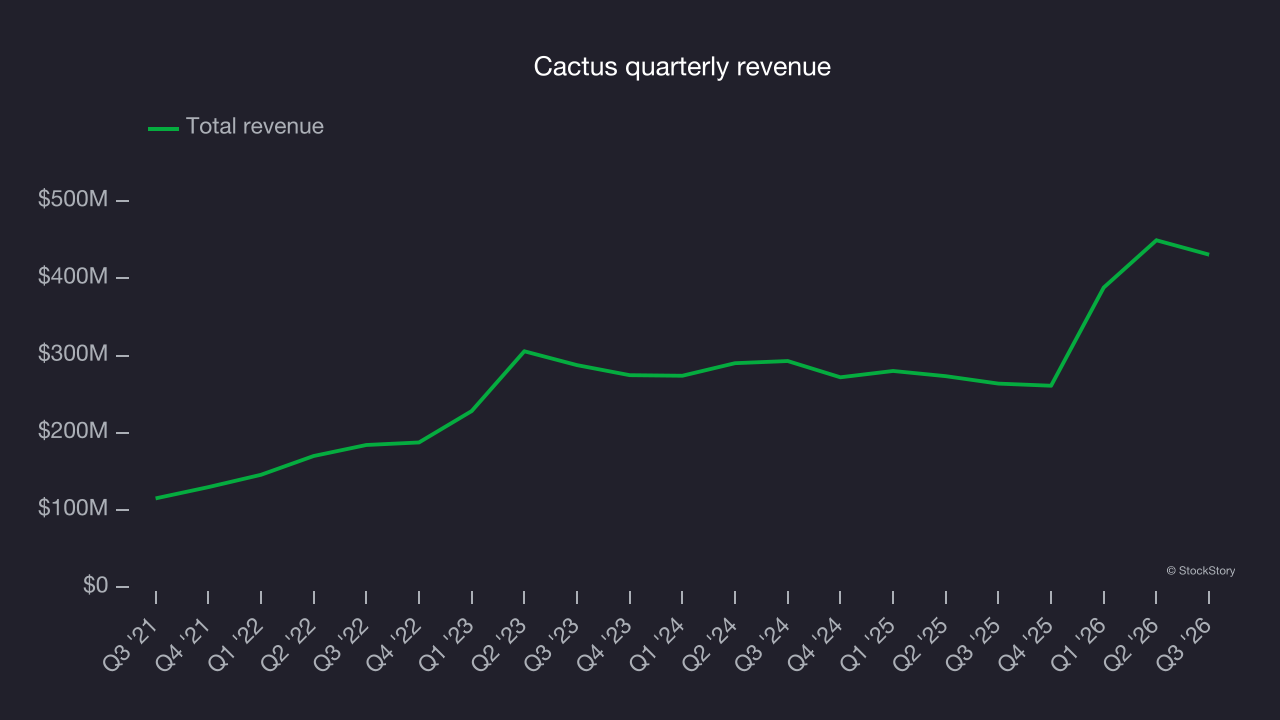
Even a long stretch in energy can be shaped by a single commodity cycle, so extending the view to ten years adds another perspective and reveals which companies are built to grow regardless of the pricing regime. Cactus’s annualized revenue growth of 28.2% over the last ten years is below its five-year trend, but the results still suggest decent demand.
This quarter, Cactus’s year-on-year revenue growth of 63.2% was strong, and its $430.9 million of revenue was in line with Wall Street’s consensus estimates.
Adjusted EBITDA margin
Cactus has managed its cost base reasonably well over the last five years. The company has produced an average EBITDA margin of 32.9%, higher than the broader energy upstream and integrated energy sector.
Looking at the trend in its profitability, Cactus’s EBITDA margin decreased by 2 percentage points over the last year. This raises questions about the company’s expense base because its revenue growth should have given it leverage on its fixed costs, resulting in better economies of scale and profitability.
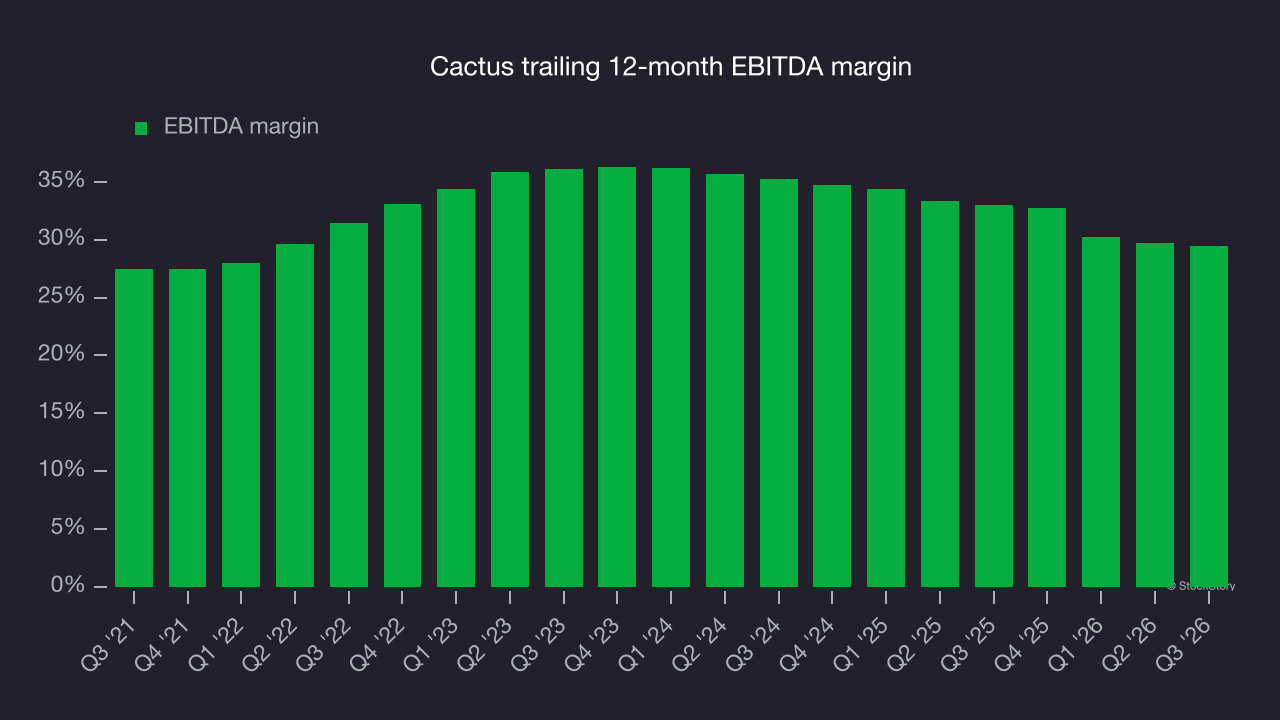
This quarter, Cactus generated an EBITDA margin of 30.6%, down 2.3 percentage points year on year. This contraction shows it was less efficient because its expenses grew faster than its revenue. Its adjusted EBITDA beat Wall Street’s consensus estimates by 9%.
Key takeaways from Cactus’s Q3 results
Cactus delivered a solid quarter, with both EPS and EBITDA topping analysts’ consensus estimates. Shares remained flat at $64.34 immediately after the results.
Evaluating Cactus at its current price requires considering its valuation, business quality and latest quarterly results. Read the full research report here (it’s free).