Regional banking company First Interstate BancSystem (NASDAQ: FIBK) met Wall Street’s revenue expectations in Q3 2026, but sales were flat year on year at $249.5 million. Its GAAP profit of $0.65 per share was 5% below analysts’ consensus estimates.
Is now the time to buy First Interstate BancSystem? Find out by accessing our full research report, it’s free.
First Interstate BancSystem (FIBK) Q3 2026 highlights:
- Net Interest Income: $206.2 million vs analyst estimates of $205.1 million (flat year on year, 0.5% beat)
- Net Interest Margin: 3.5% vs analyst estimates of 3.5% (2.3 basis point beat)
- Revenue: $249.5 million vs analyst estimates of $248.8 million (flat year on year, in line)
- Efficiency Ratio: 61.7% vs analyst estimates of 63.8% (212.6 basis point beat)
- EPS (GAAP): $0.65 vs analyst expectations of $0.68 (5% miss)
- Tangible Book Value per Share: $21.20 vs analyst estimates of $22.34 (3.8% year-on-year decline, 5.1% miss)
- Market Capitalization: $3.4 billion
“We are pleased to see meaningful improvement in our net interest margin and an increase in non-interest bearing deposits, as we remain focused on strengthening the quality and earnings power of the franchise,” said James A. Reuter, President and Chief Executive Officer of the Company. “We also continued to execute on our previously announced share repurchase authorization, underscoring our commitment to shareholder returns. Through disciplined capital deployment, operating model optimization, and continued investment in relationship growth, we are building a more efficient organization and remain confident in our ability to deliver improving returns over time.”
Company overview
Tracing its roots back to 1971 and still guided by founding family principles, First Interstate BancSystem (NASDAQ: FIBK) operates a network of community banks across 10 western and midwestern states, offering comprehensive banking services to individuals, businesses, and government entities.
Sales growth
In general, banks make money from two primary sources. The first is net interest income, which is interest earned on loans, mortgages, and investments in securities minus interest paid out on deposits. The second source is non-interest income, which can come from bank account, credit card, wealth management, investment banking, and trading fees. Unfortunately, First Interstate BancSystem’s 9.1% annualized revenue growth over the last five years was mediocre. This was below our standard for the banking sector and is a tough starting point for our analysis.
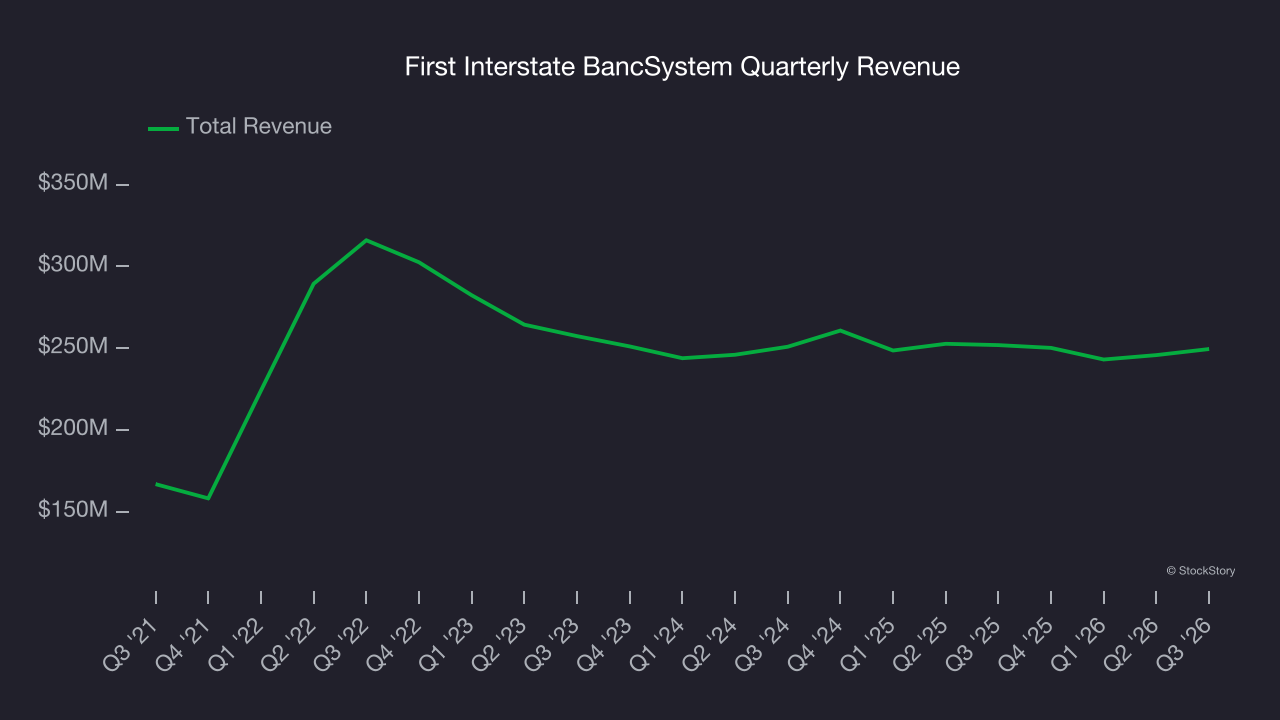
Long-term growth is the most important, but within financials, a half-decade historical view may miss recent interest rate changes and market returns. First Interstate BancSystem’s recent performance shows its demand has slowed as its revenue was flat over the last two years. 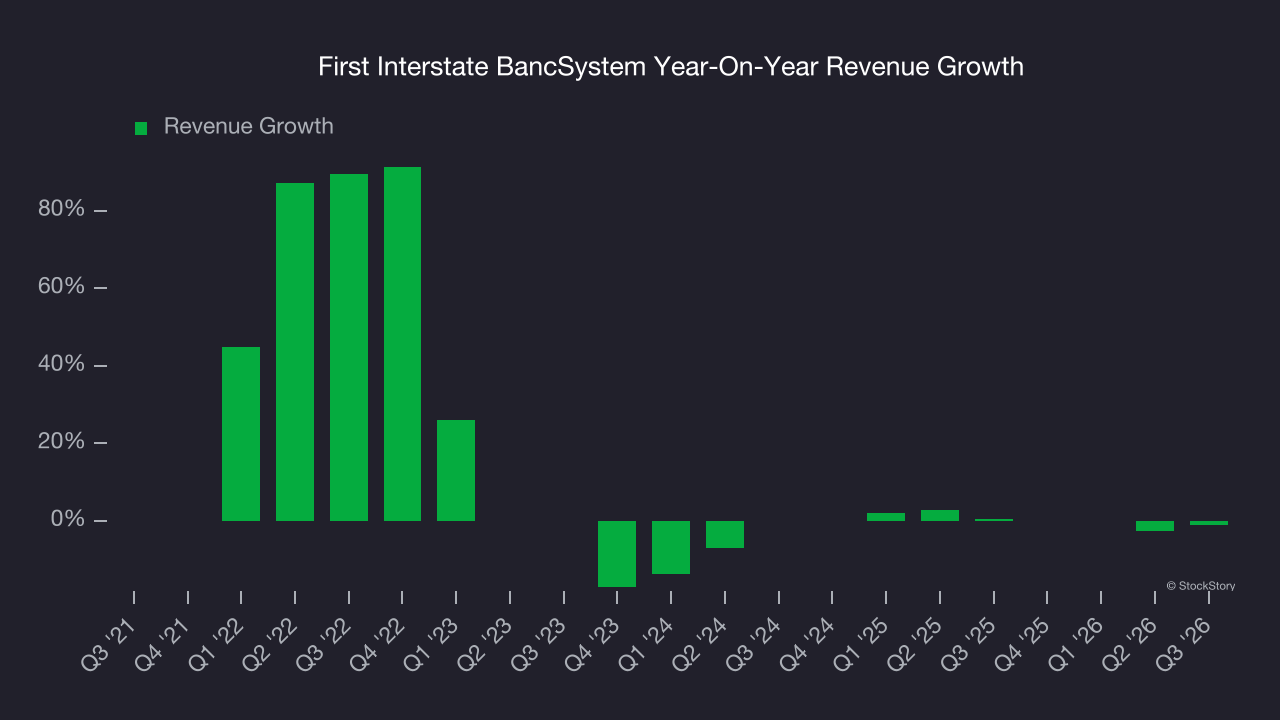 Note: Quarters not shown were determined to be outliers because they were impacted by outsized investment gains/losses that are not indicative of the recurring fundamentals of the business.
This quarter, First Interstate BancSystem’s $249.5 million of revenue was flat year on year and in line with Wall Street’s estimates.
Net interest income made up 82.4% of the company’s total revenue during the last five years, meaning First Interstate BancSystem barely relies on non-interest income to drive its overall growth.
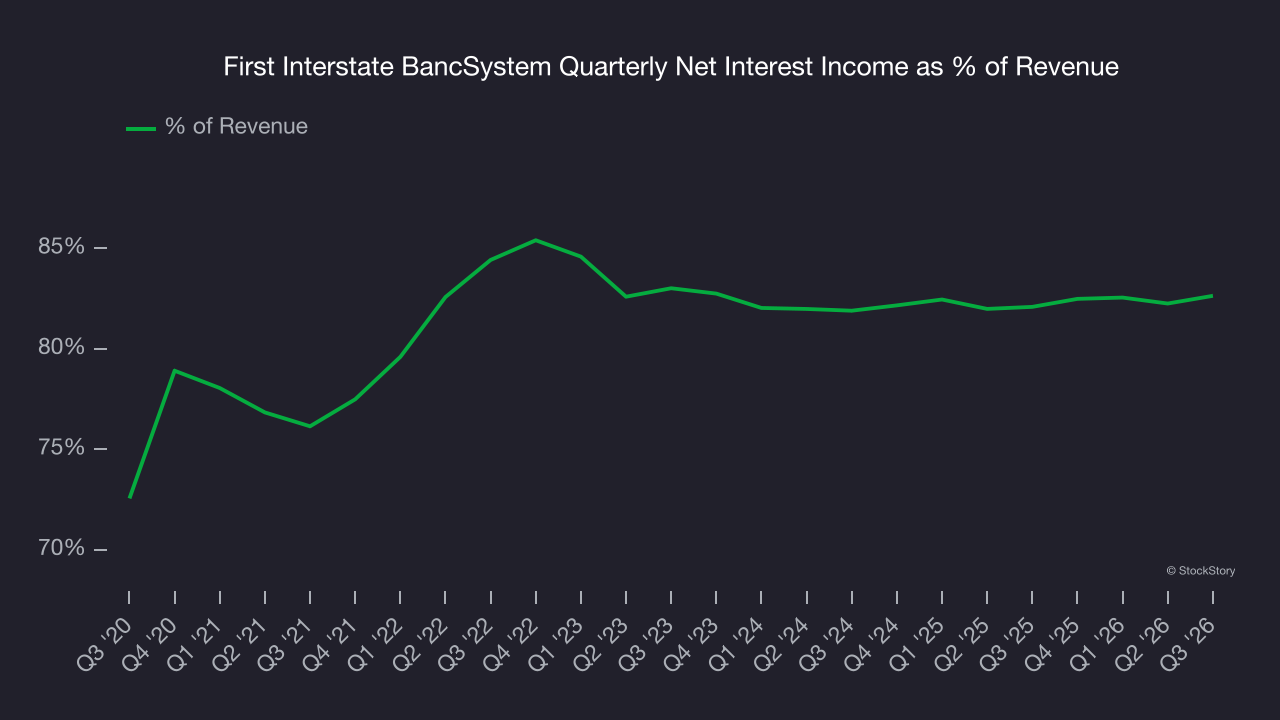
While banks generate revenue from multiple sources, investors view net interest income as the cornerstone - its predictable, recurring characteristics stand in sharp contrast to the volatility of non-interest income.
WHILE YOU’RE HERE: The Next Palantir? One satellite company captures images of every point on Earth. Every single day. The Pentagon wants it. Hedge funds are using it to beat earnings. You’ve probably never heard of it.
This is what the early days of Palantir looked like before it became a giant. Same playbook. Different technology. If you missed Palantir, you need to see this. Claim The Stock Ticker for Free HERE.
Tangible book value per share (TBVPS)
Banks profit by intermediating between depositors and borrowers, making them fundamentally balance sheet-driven enterprises. Market participants emphasize balance sheet quality and sustained book value growth when evaluating these institutions.
This explains why tangible book value per share (TBVPS) stands as the premier banking metric. TBVPS strips away questionable intangible assets, revealing concrete per-share net worth that investors can trust. Traditional metrics like EPS are helpful but face distortion from M&A activity and loan loss accounting rules.
First Interstate BancSystem’s TBVPS was flat over the last five years. The last two years unveil a similar pattern as TBVPS was roughly flat at $21.20 per share.
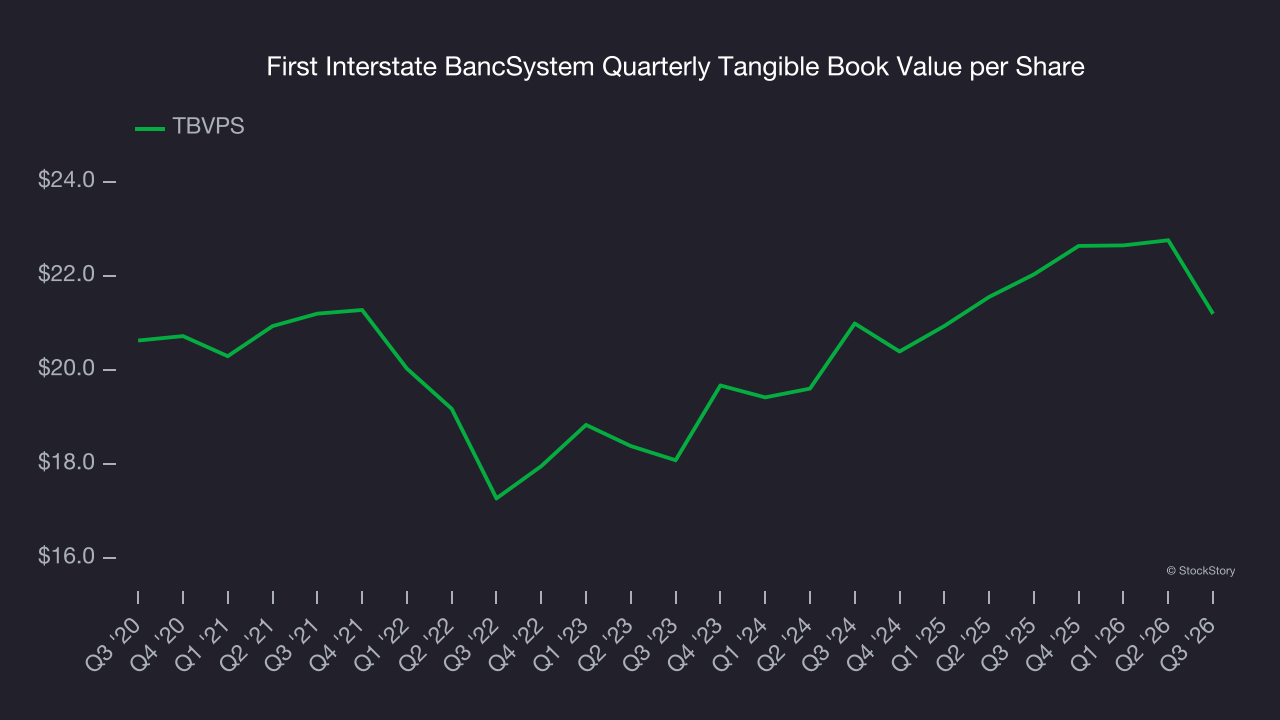
Over the next 12 months, Consensus estimates call for First Interstate BancSystem’s TBVPS to grow by 9.1% to $23.14, paltry growth rate.
Key takeaways from First Interstate BancSystem’s Q3 results
It was good to see First Interstate BancSystem narrowly top analysts’ net interest income expectations this quarter. On the other hand, its tangible book value per share missed and its EPS fell short of Wall Street’s estimates. Overall, this was a weaker quarter. The stock remained flat at $36.88 immediately following the results.
Is First Interstate BancSystem an attractive investment opportunity at the current price? If you’re making that decision, you should consider the bigger picture of valuation, business qualities, as well as the latest earnings. We cover that in our actionable full research report which you can read here (it’s free).