Over the last six months, Option Care Health’s shares have sunk to $23.95, producing a disappointing 15.7% loss - a stark contrast to the S&P 500’s 16.2% gain. This might have investors contemplating their next move.
Is now the time to buy Option Care Health, or should you be careful about including it in your portfolio? Check out our in-depth research report to see what our analysts have to say, it’s free.
Why Is Option Care Health Not Exciting?
Despite the more favorable entry price, we don’t have much confidence in Option Care Health. Here are three reasons why there are better opportunities than OPCH, plus one stock we’d rather own.
1. Projected Revenue Growth Is Slim
Forecasted revenues by Wall Street analysts signal a company’s potential. Predictions may not always be accurate, but accelerating growth typically boosts valuation multiples and stock prices while slowing growth does the opposite.
Over the next 12 months, sell-side analysts expect Option Care Health’s revenue to rise by 4.3%, a deceleration versus its 12.2% annualized growth for the past five years. This projection is underwhelming and suggests its products and services will face some demand challenges.
2. Free Cash Flow Margin Stuck in Neutral
Free cash flow isn’t a prominently featured metric in company financials and earnings releases, but we think it’s telling because it accounts for all operating and capital expenses, making it tough to manipulate. Cash is king.
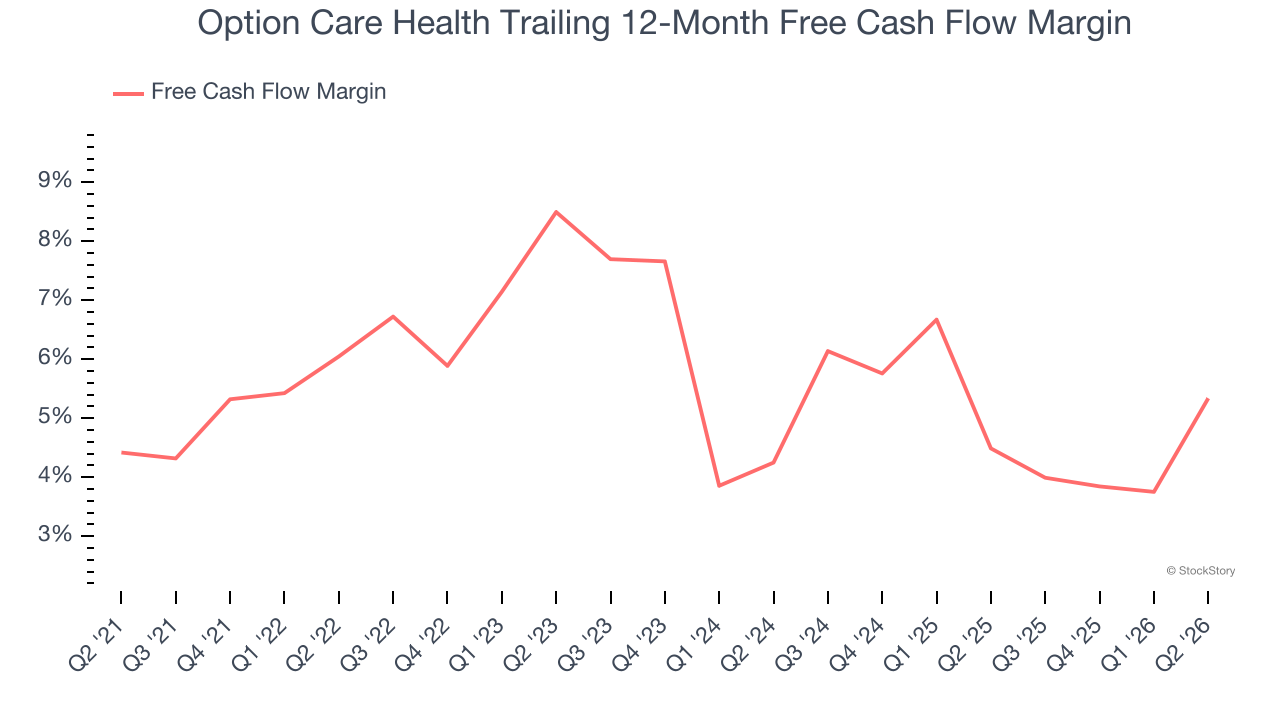
As you can see below, Option Care Health’s margin was unchanged over the last five years, showing it couldn’t improve. Its free cash flow margin for the trailing 12 months was 5.3%.
3. New Investments Aren’t Moving the Needle
ROIC, or return on invested capital, is a metric showing how much operating profit a company generates relative to the money it has raised (debt and equity).
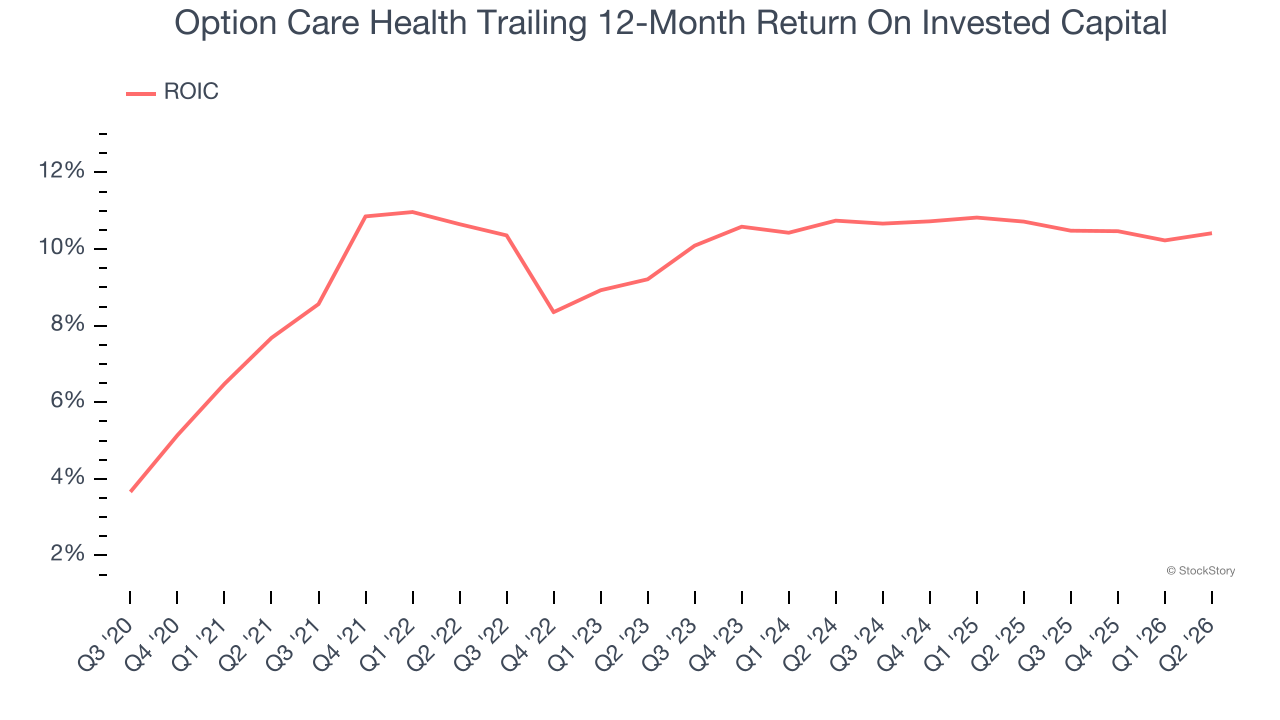
Uneventfully, Option Care Health’s ROIC has stayed the same over the last few years. Given the company’s underwhelming financial performance in other areas, we’d like to see its returns improve before recommending the stock.
Final Judgment
Option Care Health isn’t a terrible business, but it doesn’t pass our quality test. Following the recent decline, the stock trades at 12.3× forward P/E (or $23.95 per share). This valuation multiple is fair, but we don’t have much faith in the company. We’re pretty confident there are superior stocks to buy right now. We’d suggest looking at one of Charlie Munger’s all-time favorite businesses.
High-Quality Stocks for All Market Conditions
ONE MORE THING: Top 5 Growth Stocks. The biggest stock winners almost always had one thing in common before they ran. Revenue growing like crazy. Meta. CrowdStrike. Broadcom. Our AI flagged all three. They returned 315%, 314%, and 455%, respectively.
Find out which 5 stocks it’s flagging this month — FREE. Get Our Top 5 Growth Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Comfort Systems (+1,154% between June 2020 and June 2025). Find your next big winner with StockStory today.