Even though Oaktree Specialty Lending (currently trading at $12.43 per share) has gained 9.6% over the last six months, it has lagged the S&P 500’s 16.2% return during that period. This may have investors wondering how to approach the situation.
Is there a buying opportunity in Oaktree Specialty Lending, or does it present a risk to your portfolio? Check out our in-depth research report to see what our analysts have to say, it’s free.
Why Do We Think Oaktree Specialty Lending Will Underperform?
We don’t have much confidence in Oaktree Specialty Lending. Here are three reasons why there are better opportunities than OCSL, plus one stock we’d rather own.
1. Revenue Tumbling Downwards
We at StockStory place the most emphasis on long-term growth, but within financials, a stretched historical view may miss recent interest rate changes, market returns, and industry trends. Oaktree Specialty Lending’s recent performance marks a sharp pivot from its five-year trend as its revenue has shown annualized declines of 13.3% over the last two years. 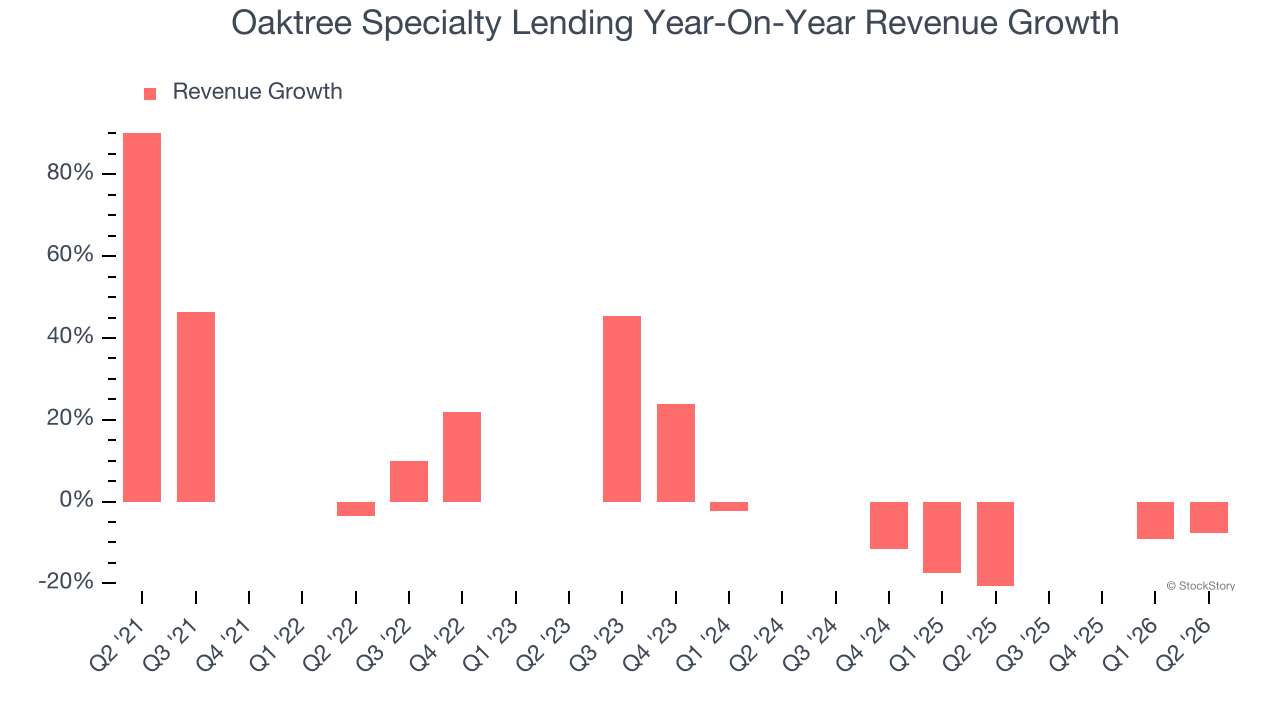 Note: Quarters not shown were determined to be outliers because they were impacted by outsized investment gains/losses that are not indicative of the recurring fundamentals of the business.
2. EPS Trending Down
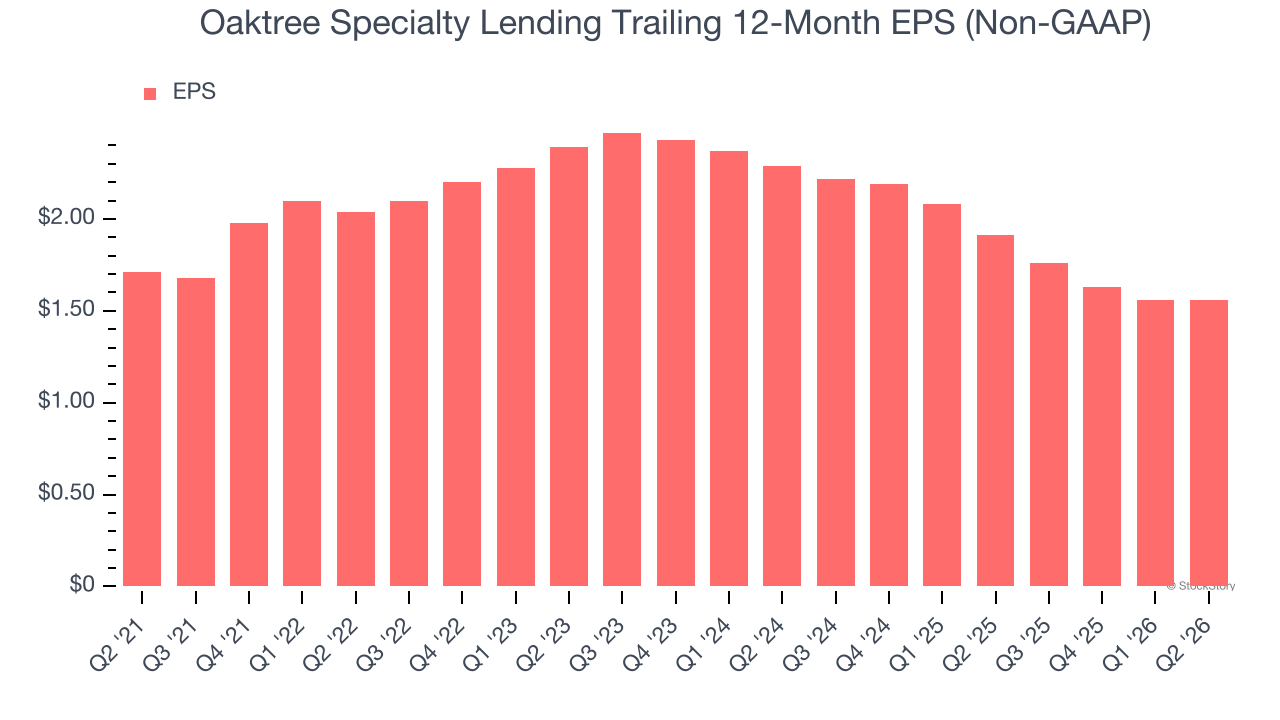
We track the long-term change in earnings per share (EPS) because it highlights whether a company’s growth is profitable.
Sadly for Oaktree Specialty Lending, its EPS declined by 1.8% annually over the last five years while its revenue grew by 9.1%. This tells us the company became less profitable on a per-share basis as it expanded.
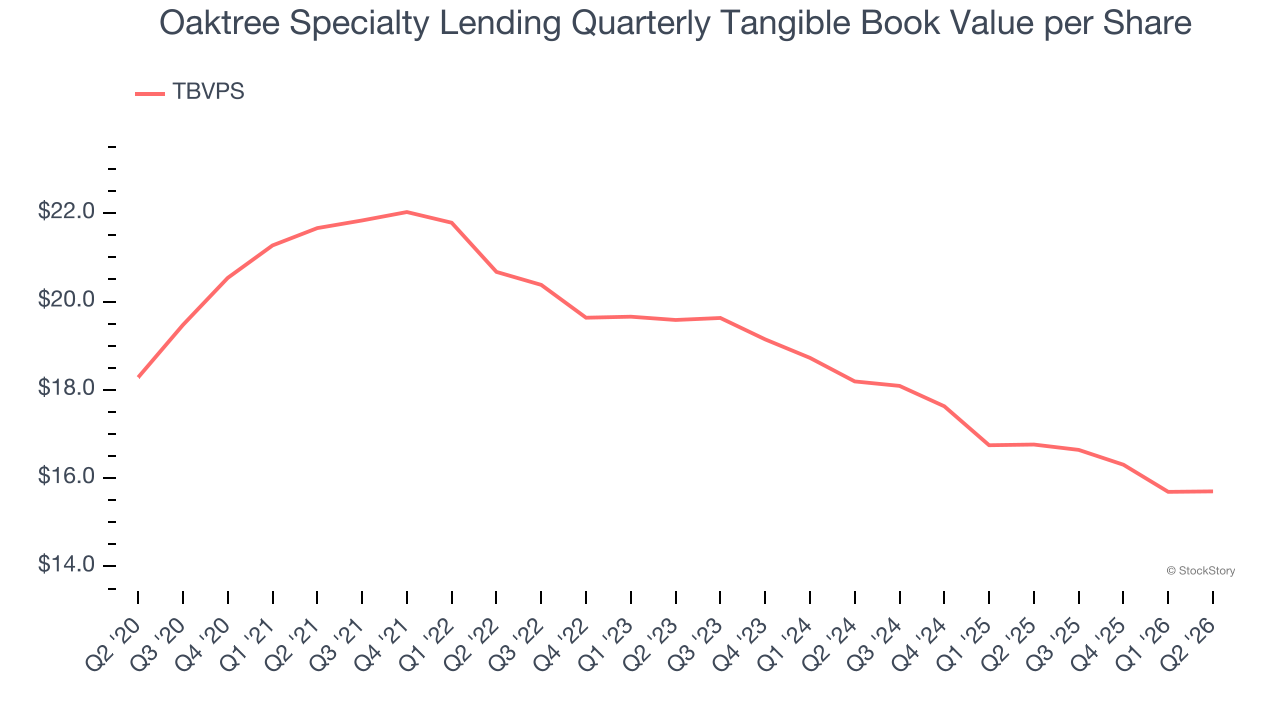
3. Declining TBVPS Reflects Erosion of Asset Value
In the financials industry, tangible book value per share (TBVPS) provides the clearest picture of shareholder value, as it focuses on concrete assets while excluding intangible items that may not hold value during challenging times.
To the detriment of investors, Oaktree Specialty Lending’s TBVPS declined at a 7.1% annual clip over the last two years.
Final Judgment
Oaktree Specialty Lending doesn’t pass our quality test. With its shares trailing the market in recent months, the stock trades at 9.1× forward P/E (or $12.43 per share). While this valuation is optically cheap, the potential downside is huge given its shaky fundamentals. There are more exciting stocks to buy at the moment. We’d recommend looking at one of our top digital advertising picks.
Stocks We Would Buy Instead of Oaktree Specialty Lending
ONE MORE THING: Top 6 Stocks for This Week. This market is separating quality stocks from expensive ones fast. AI is taking down whole sectors with no warning. In a rotation this fast, you need more than a list of good companies.
Our AI system flagged Palantir before it ran 1,662% between October 2022 and February 2026. AppLovin before it ran 753% between February 2024 and February 2026. Nvidia before it ran 1,178% between January 2023 and February 2026. Each week it produces 6 new names that pass the same tests. Get Our Top 6 Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Kadant (+214% between June 2020 and June 2025). Find your next big winner with StockStory today.