Over the past six months, Amdocs’s shares (currently trading at $59.50) have posted a disappointing 8.6% loss, well below the S&P 500’s 16.2% gain. This might have investors contemplating their next move.
Is there a buying opportunity in Amdocs, or does it present a risk to your portfolio? Get the full stock story straight from our expert analysts, it’s free.
Why Do We Think Amdocs Will Underperform?
Even with the cheaper entry price, we’re sitting this one out for now. Here are three reasons why DOX doesn’t excite us, plus one stock we’d rather own.
1. Long-Term Revenue Growth Disappoints
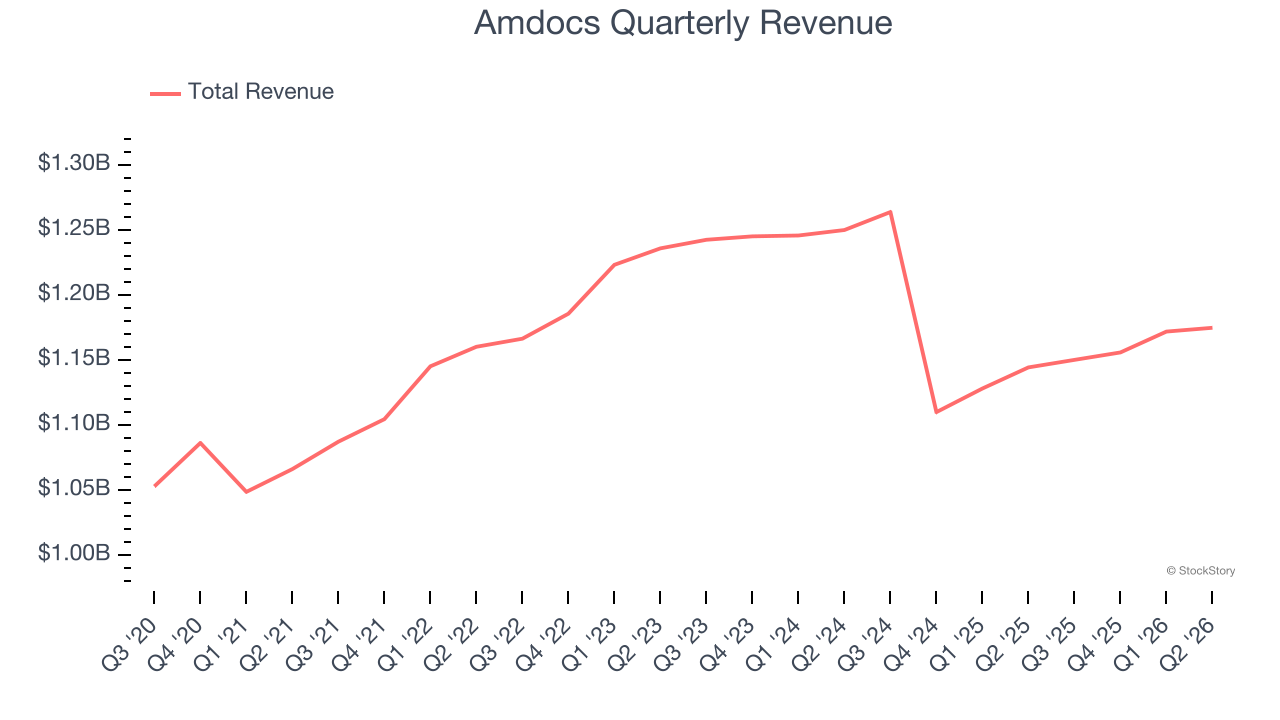
Reviewing a company’s long-term sales performance reveals insights into its quality. Any business can experience short-term success, but top-performing ones enjoy sustained growth for years. Over the last five years, Amdocs grew its sales at a sluggish 1.8% compounded annual growth rate. This was below our standards.
2. Projected Revenue Growth Is Slim
Forecasted revenues by Wall Street analysts signal a company’s potential. Predictions may not always be accurate, but accelerating growth typically boosts valuation multiples and stock prices while slowing growth does the opposite.
Over the next 12 months, sell-side analysts expect Amdocs’s revenue to rise by 3.4%. While this projection implies its newer products and services will spur better top-line performance, it is still below average for the sector.
3. New Investments Fail to Bear Fruit as ROIC Declines
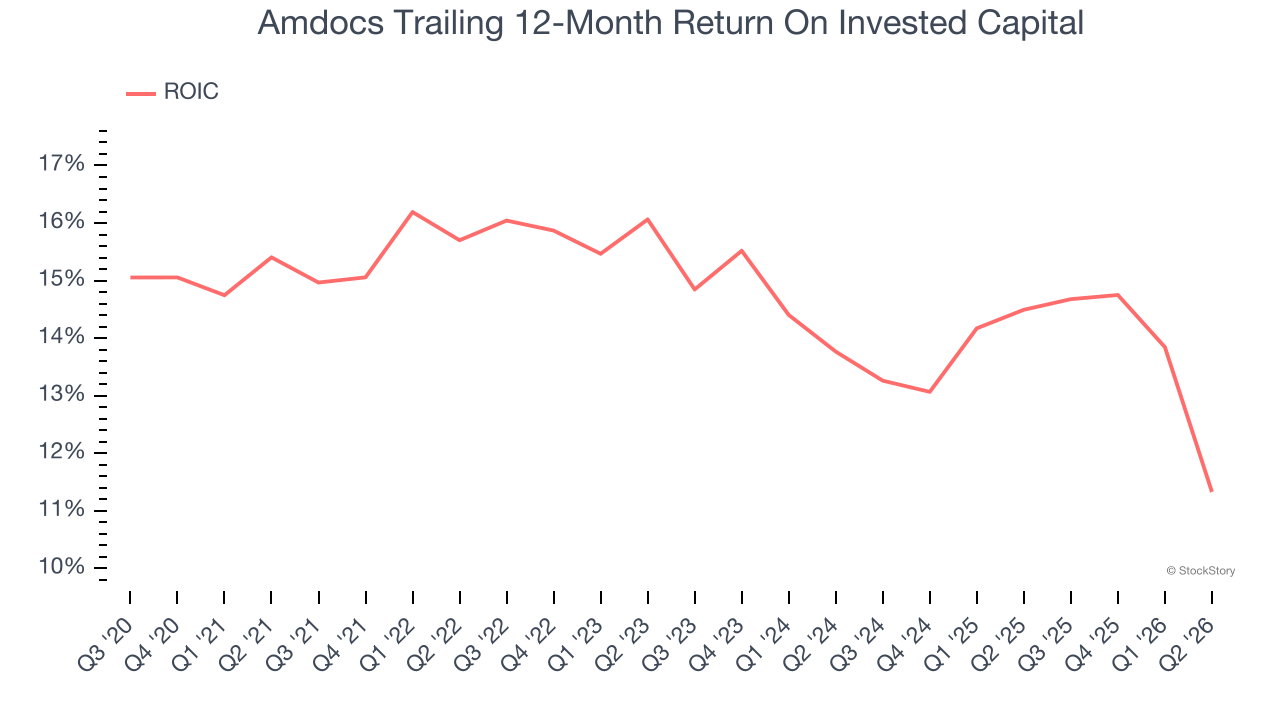
ROIC, or return on invested capital, is a metric showing how much operating profit a company generates relative to the money it has raised (debt and equity).
Over the last few years, Amdocs’s ROIC averaged 3 percentage point decreases each year. We like what management has done in the past, but its declining returns are perhaps a symptom of fewer profitable growth opportunities.
Final Judgment
We cheer for all companies making their customers lives easier, but in the case of Amdocs, we’ll be cheering from the sidelines. Following the recent decline, the stock trades at 7.5× forward P/E (or $59.50 per share). While this valuation is optically cheap, the potential downside is huge given its shaky fundamentals. There are better stocks to buy right now. We’d recommend looking at one of Charlie Munger’s all-time favorite businesses.
Stocks We Like More Than Amdocs
ALSO WORTH WATCHING: Top 5 Momentum Stocks. The best time to own a great stock is when the market is finally noticing it. These aren’t just high-quality businesses. Something is happening with them right now. Elite fundamentals meet near-term momentum — both boxes checked at the same time.
Find out which stocks our AI platform is flagging this week. See this week’s Strong Momentum stocks — FREE. Get Our Strong Momentum Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Tecnoglass (+1,552% between June 2020 and June 2025). Find your next big winner with StockStory today.