Over the past six months, ePlus has been a great trade, beating the S&P 500 by 5.1%. Its stock price has climbed to $92.23, representing a healthy 21.3% increase. This was partly thanks to its solid quarterly results, and the run-up might have investors contemplating their next move.
Is it too late to buy PLUS? Find out in our full research report, it’s free.
Why Does ePlus Spark Debate?
Starting as a financing company in 1990 before evolving into a full-service technology provider, ePlus (NASDAQ: PLUS) provides comprehensive IT solutions, professional services, and financing options to help organizations optimize their technology infrastructure and supply chain processes.
Two Positive Attributes:
1. Long-Term Revenue Growth Shows Strong Momentum
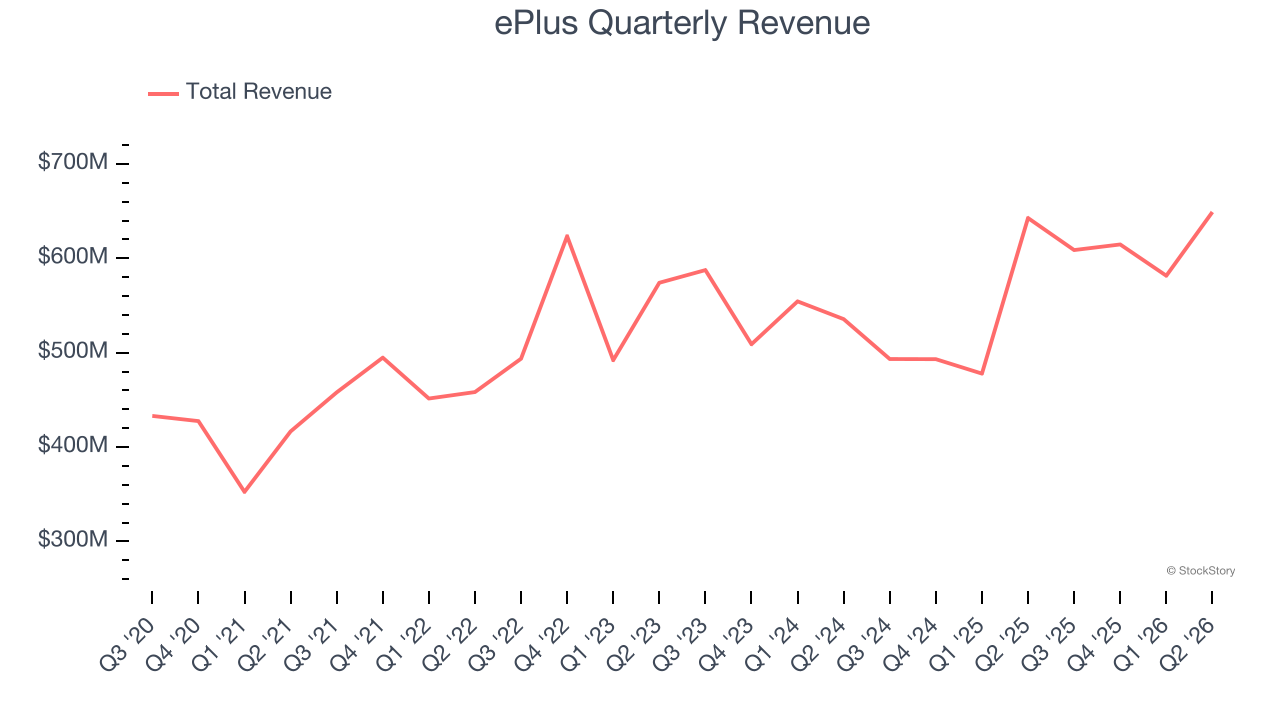
A company’s long-term performance is an indicator of its overall quality. Any business can have short-term success, but a top-tier one grows for years. Over the last five years, ePlus grew its sales at a solid 8.5% compounded annual growth rate. Its growth surpassed the average business services company and shows its offerings resonate with customers.
2. Increasing Free Cash Flow Margin Juices Financials
Free cash flow isn’t a prominently featured metric in company financials and earnings releases, but we think it’s telling because it accounts for all operating and capital expenses, making it tough to manipulate. Cash is king.
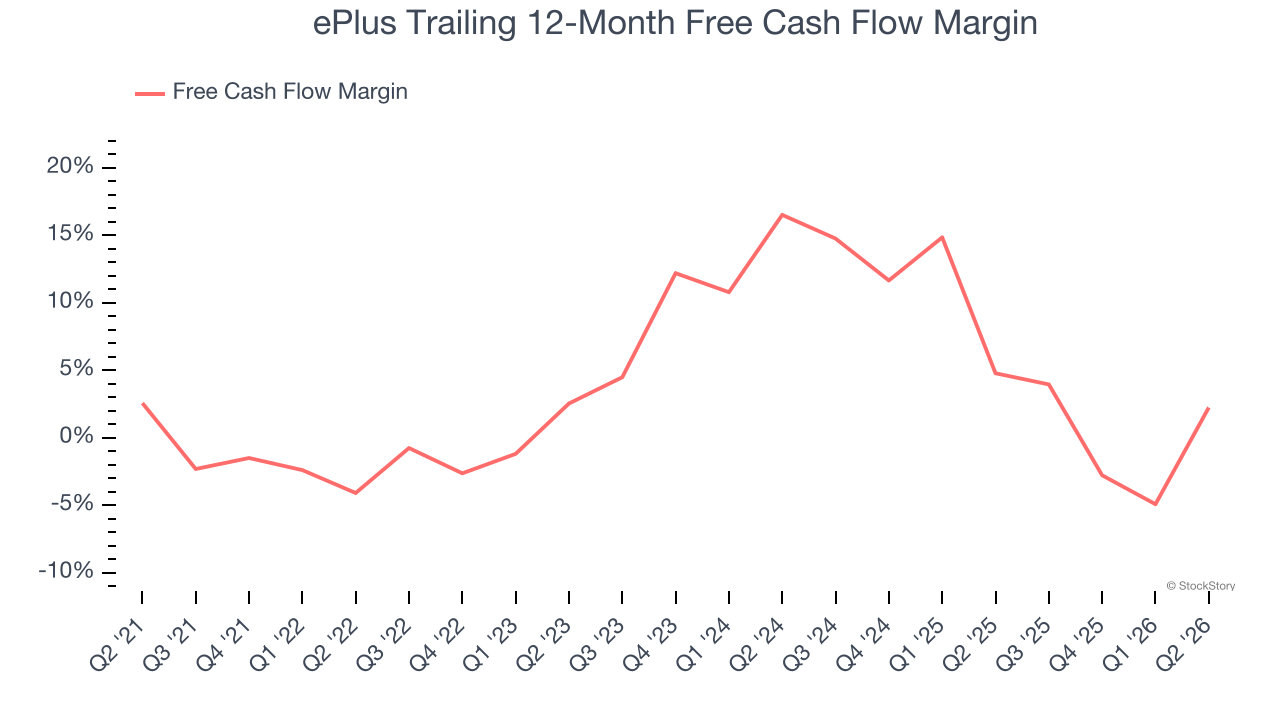
As you can see below, ePlus’s margin expanded by 6.3 percentage points over the last five years. The company’s improvement shows it’s heading in the right direction, and we can see it became a less capital-intensive business because its free cash flow profitability rose while its operating profitability fell. ePlus’s free cash flow margin for the trailing 12 months was 2.2%.
One Reason to Be Careful:
Recent EPS Growth Below Our Standards
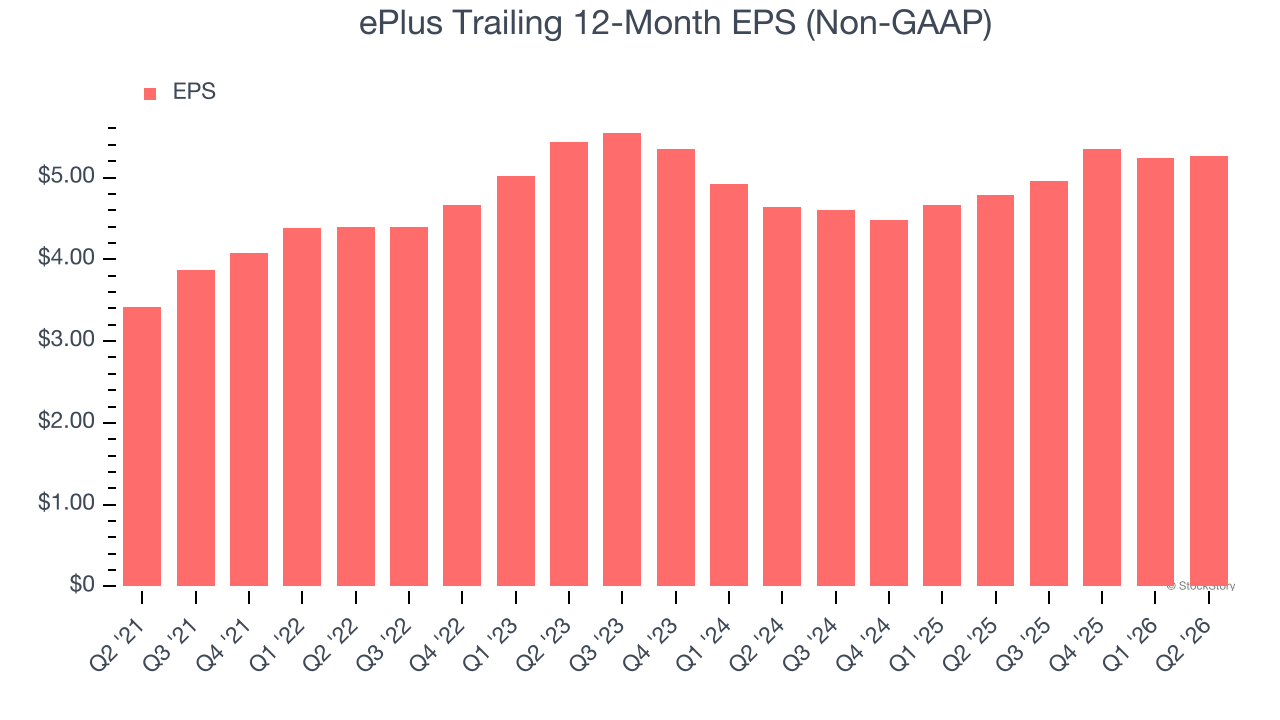
While long-term earnings trends give us the big picture, we also track EPS over a shorter period because it can provide insight into an emerging theme or development for the business.
ePlus’s unimpressive 6.5% annual EPS growth over the last two years aligns with its revenue trend. This tells us it maintained its per-share profitability as it expanded.
Final Judgment
ePlus’s positive characteristics outweigh the negatives, and with its shares outperforming the market lately, the stock trades at 16.5× forward P/E (or $92.23 per share). Is now a good time to buy? See for yourself in our in-depth research report, it’s free.
Stocks We Like Even More Than ePlus
ONE MORE THING: Top 6 Stocks for This Week. This market is separating quality stocks from expensive ones fast. AI is taking down whole sectors with no warning. In a rotation this fast, you need more than a list of good companies.
Our AI system flagged Palantir before it ran 1,662% between October 2022 and February 2026. AppLovin before it ran 753% between February 2024 and February 2026. Nvidia before it ran 1,178% between January 2023 and February 2026. Each week it produces 6 new names that pass the same tests. Get Our Top 6 Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Exlservice (+271% between June 2020 and June 2025). Find your next big winner with StockStory today.