Commercial real estate finance company Walker & Dunlop (NYSE: WD) fell short of the market’s revenue expectations in Q3 2026, with revenue falling 11.6% year on year to $298.4 million. Its non-GAAP profit of $0.92 per share was in line with analysts’ consensus estimates.
For more on Walker & Dunlop, read our free full research report.
Walker & Dunlop (WD) Q3 2026 highlights:
- Revenue $298.4 million vs S&P analysts’ consensus estimates of $333.3 million (11.6% year-on-year decline, 10.5% miss)
- Adjusted EPS $0.92 vs S&P analysts’ consensus estimates of $0.93 (in line)
- Market capitalization $1.32 billion
“Q3 2026 saw an 84 basis point increase in the Ten-Year Treasury rate which increased volatility and slowed down capital markets activity across the country. Despite these headwinds, our revenues remained resilient, with total debt financing volume down only 5% from Q3 2025," said Willy Walker, Chairman and CEO. "During the quarter we received notice from Fannie Mae that they have completed their fraud review of Walker & Dunlop, similar to Freddie Mac in Q2 2026, and we do not expect any further buybacks or indemnifications related to these investigations going forward. Importantly, we are taking action to address the legacy credit issues associated with these matters and put them firmly behind us. We reclassified all of the repurchased assets and non-performing notes to "held for sale," recognized a significant charge to Q3 earnings, and intend to dispose of these assets by early 2027. While these actions have a meaningful near-term impact on earnings, they reflect our commitment to proactively resolving credit issues, reducing risk on our balance sheet, and strengthening our financial position for the future. We believe that the completion of the GSE investigations and the sale of the repurchased loans, allows Walker & Dunlop to move beyond the borrower fraud issues that have consumed us, and our financial performance, for the past two years.”
Revenue growth
Net interest income and fee-based revenue are the two pillars supporting bank earnings. The former captures profit from the gap between lending rates and deposit costs, while the latter encompasses charges for banking services, credit products, wealth management and trading activities. Walker & Dunlop struggled to consistently increase demand as its $1.25 billion of revenue for the trailing 12 months was close to its revenue five years ago. That underwhelming result suggests it’s a low-quality business.
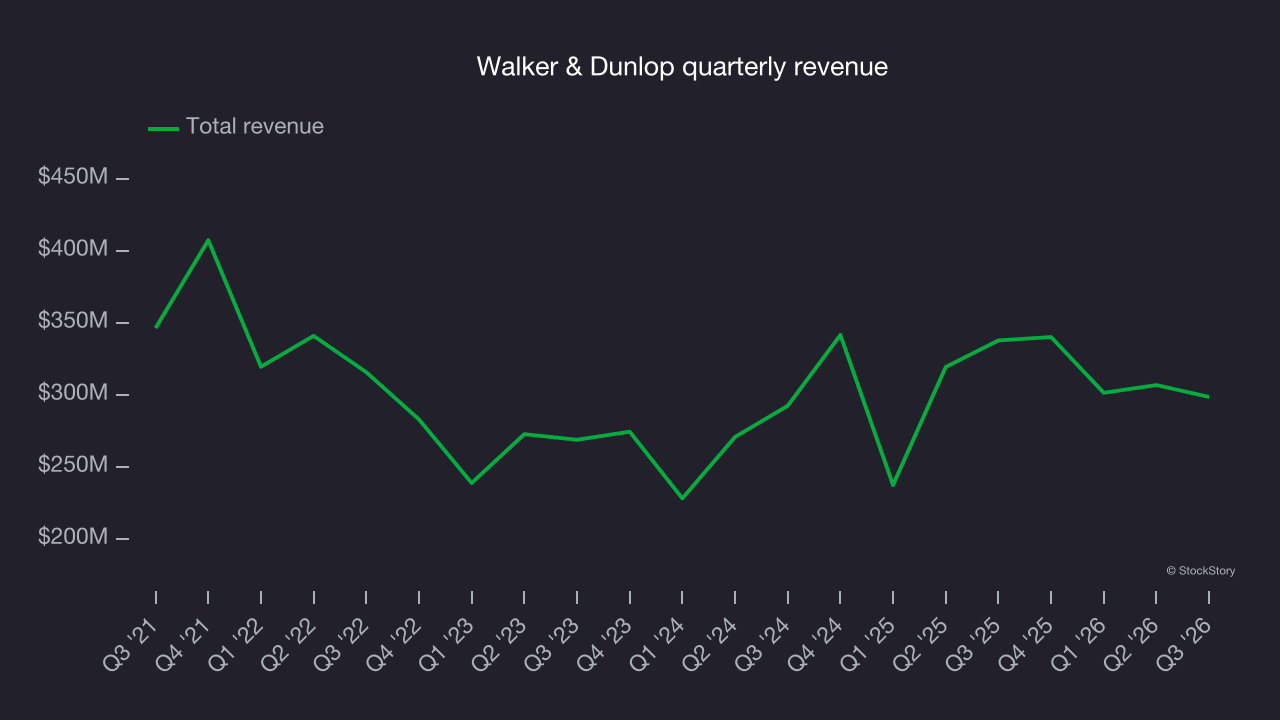
Long-term growth is the most important, but within financials, a half-decade historical view may miss recent interest rate changes and market returns. Walker & Dunlop’s annualized revenue growth of 8.2% over the last two years is above its five-year trend, a positive sign. 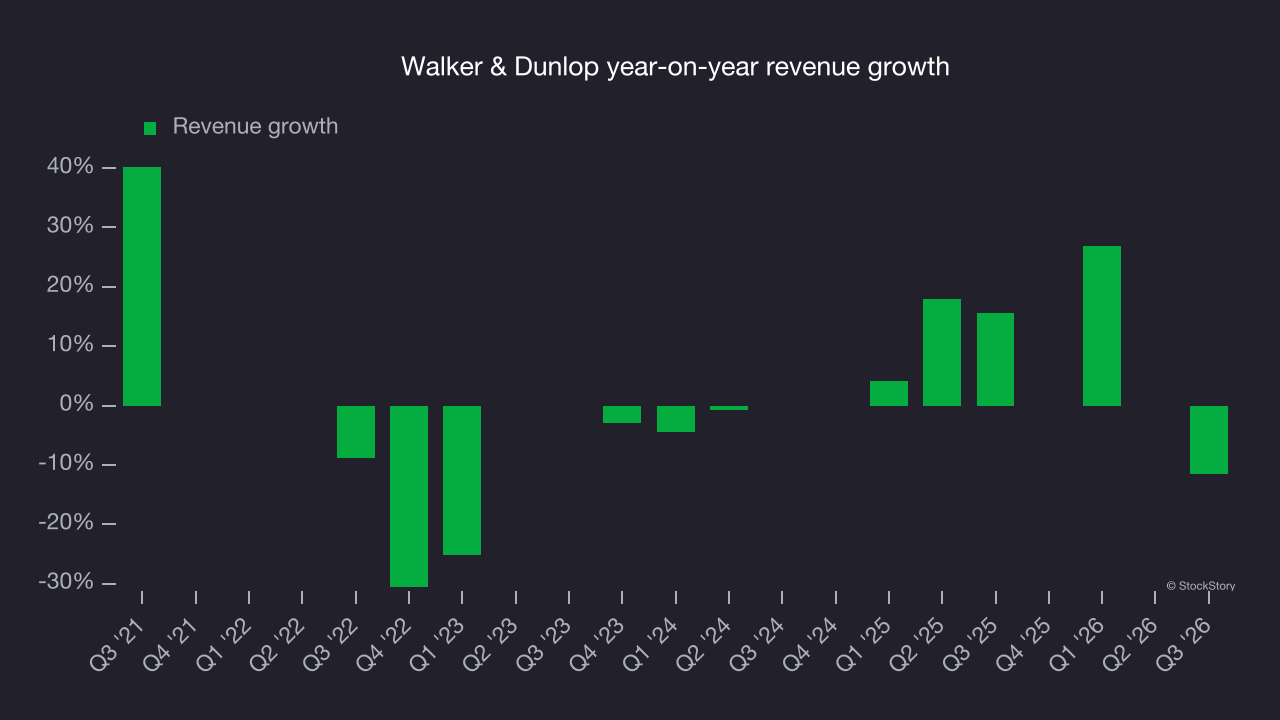 Note: Quarters not shown were determined to be outliers because they were impacted by outsized investment gains/losses that are not indicative of the recurring fundamentals of the business.
This quarter, Walker & Dunlop missed Wall Street’s consensus estimates and reported an uninspiring 11.6% year-on-year revenue decline, generating $298.4 million of revenue.
Net interest income made up -5% of the company’s total revenue during the last five years, meaning Walker & Dunlop is well diversified and has a variety of income streams driving its overall growth. Nevertheless, net interest income is critical to analyze for banks because investors consider it a higher-quality, more recurring revenue source.
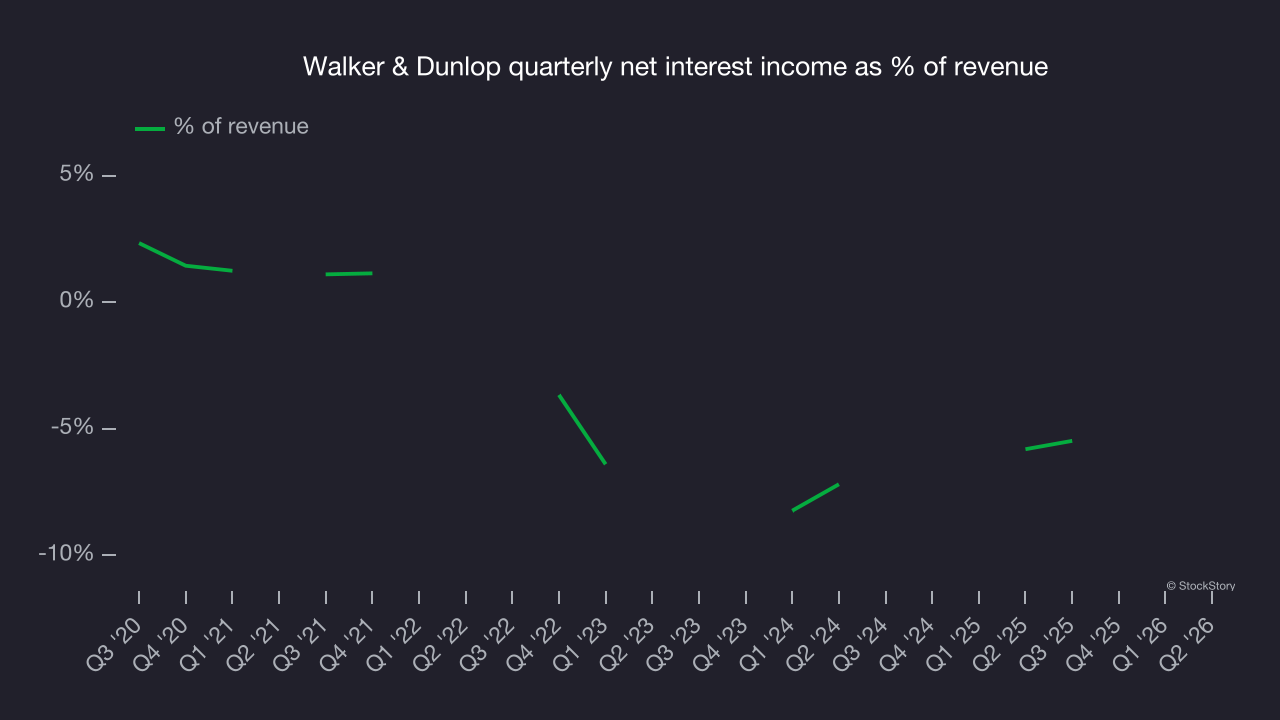 Note: Quarters not shown were determined to be outliers because they were impacted by outsized investment gains/losses that are not indicative of the recurring fundamentals of the business.
Key takeaways from Walker & Dunlop’s Q3 results
Walker & Dunlop’s revenue fell short of Wall Street’s consensus estimates, and EPS only met expectations, leaving few positives in a weaker quarter. Shares edged lower 1.9% to $37.60 immediately after the results.
Walker & Dunlop underperformed this quarter. In assessing whether that creates an investment opportunity, the latest results matter, but less than longer-term business quality and valuation. Read the full research report here (it’s free).