Clothing company Kontoor Brands (NYSE: KTB) missed Wall Street’s revenue expectations in Q3 2026 as revenue rose 2.8% year on year to $685.3 million. The company’s full-year revenue guidance of $2.68 billion at the midpoint came in 0.8% below analysts’ consensus estimates. Its non-GAAP profit of $2.06 per share was 57.2% above analysts’ consensus estimates.
For more on Kontoor Brands, read our free full research report.
Kontoor Brands (KTB) Q3 2026 highlights:
- Revenue $685.3 million vs S&P analysts’ consensus estimates of $691.9 million (2.8% year-on-year growth, 1% miss)
- Adjusted EPS $2.06 vs S&P analysts’ consensus estimates of $1.31 (57.2% beat)
- Adjusted EBITDA $117.9 million vs analysts’ consensus estimates of $111.8 million (17.2% margin, 5.5% beat)
- Revenue guidance The company reconfirmed its revenue guidance for the full year of $2.68 billion at the midpoint
- Operating margin 11.2%, up from 5.6% in the same quarter last year
- Free cash flow margin 6.9%, down from 8.5% in the same quarter last year
- Constant currency revenue rose 3% year on year (27% in the same quarter last year)
- Market capitalization $4.48 billion
“Our third quarter results were driven by growth in both Wrangler and Helly Hansen, strong earnings and gross margin expansion,” said Scott Baxter, Chief Executive Officer and Chairman of the Board of Directors. “Execution excellence remains a critical focus of our organization as we delivered strong business results, successfully completed the divestiture of Lee, advanced our integration of Helly Hansen, and realized additional synergies through optimization of our tax platform. Kontoor enters its next chapter as a more focused company anchored around two iconic brands with stronger growth profiles that position us well for the future.”
Revenue growth
A company’s long-term revenue performance is one signal of its overall quality. Any business can deliver a good quarter or two, but the best consistently grow over the long haul. Over the last five years, Kontoor Brands grew its revenue at a weak 1.9% compounded annual growth rate, falling short of our standards.
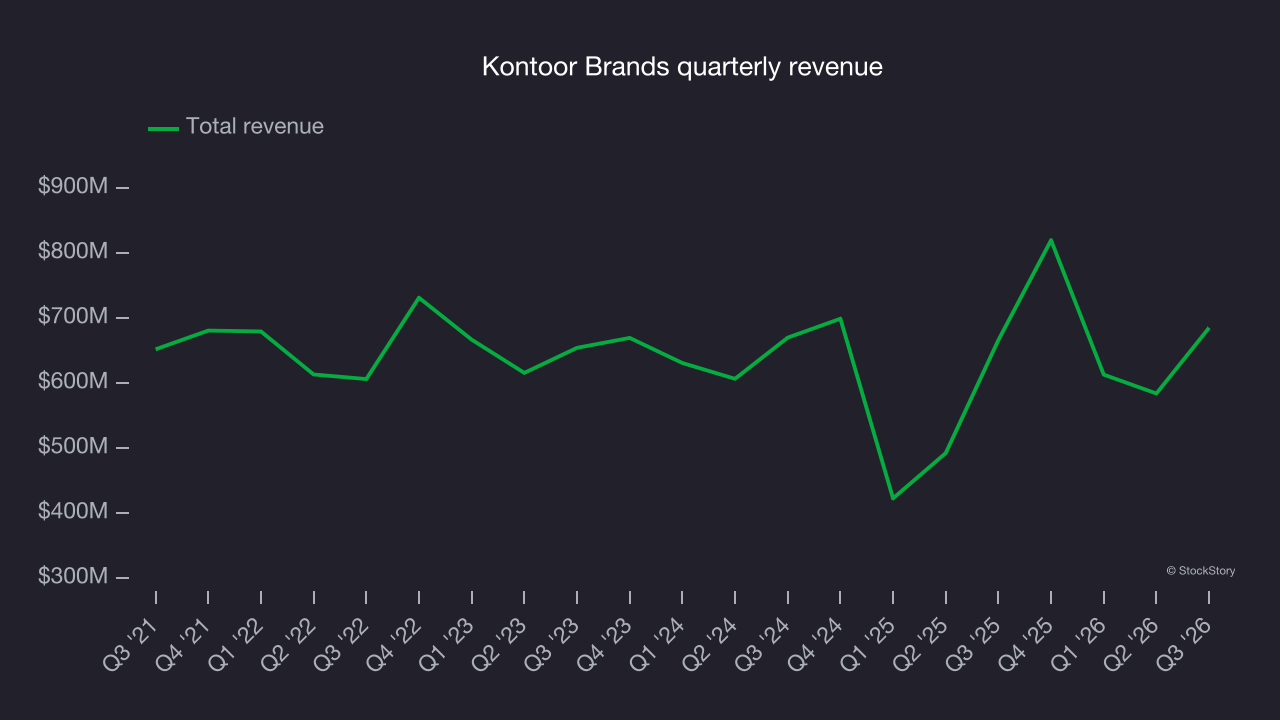
Long-term growth is the most important, but within consumer discretionary, product cycles are short and revenue can be hit-driven due to rapidly changing trends and consumer preferences. Kontoor Brands’s annualized revenue growth of 2.4% over the last two years aligns with its five-year trend, suggesting its demand was consistently weak. 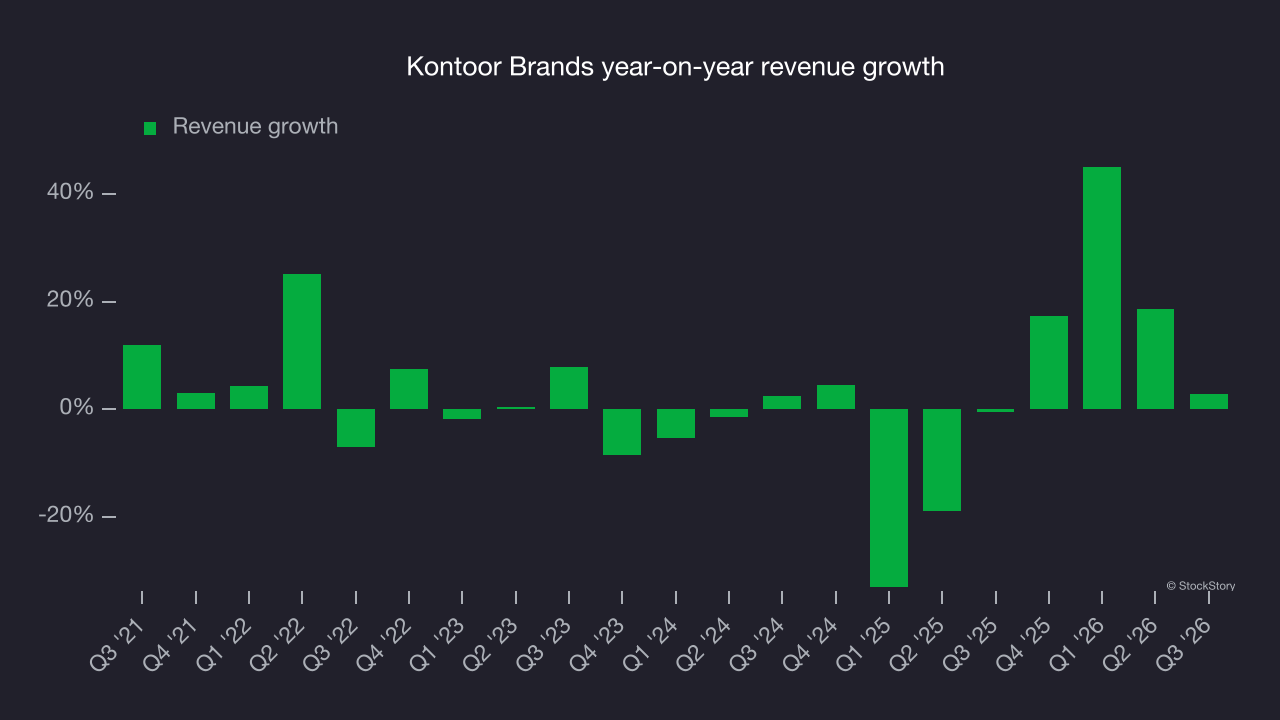
Constant currency revenue helps clarify the company’s revenue dynamics by excluding currency movements that are outside its control and not indicative of demand. Over the last two years, its constant currency revenue averaged 18% year-on-year growth. This outpaced reported revenue growth, indicating that foreign exchange rates have been a headwind for Kontoor Brands. 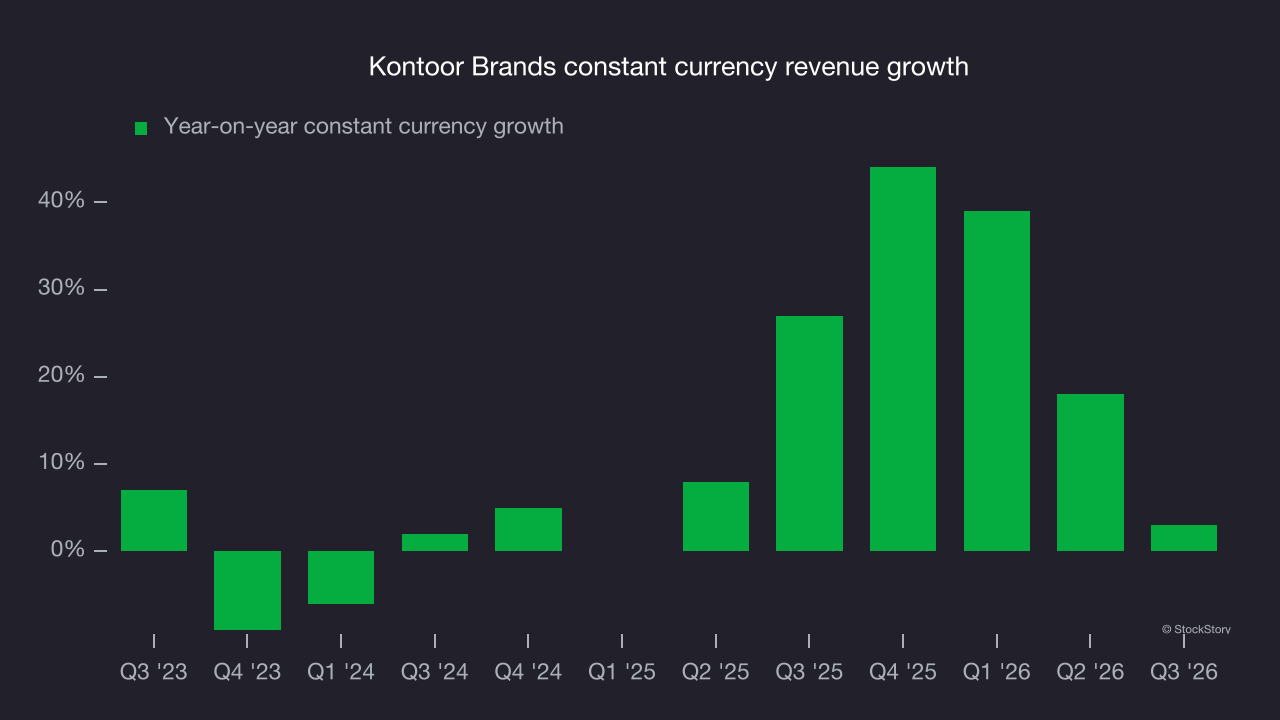
This quarter, Kontoor Brands’s revenue grew by 2.8% year on year to $685.3 million, falling short of Wall Street’s consensus estimates.
Looking ahead, sell-side analysts expect revenue to grow 3.2% over the next 12 months, according to S&P, similar to its two-year rate. This underwhelming projection suggests its newer products and services will not lead to better top-line performance yet.
Operating margin
Operating margin is a key measure of profitability. Think of it as net income – the bottom line – excluding the impact of taxes and interest on debt, which are less connected to business fundamentals.
Kontoor Brands’s operating margin has risen over the last 12 months and averaged 11.8% over the last two years. The company’s improved efficiency is a positive, but its suboptimal cost structure means its profitability remains inadequate for a consumer discretionary business.
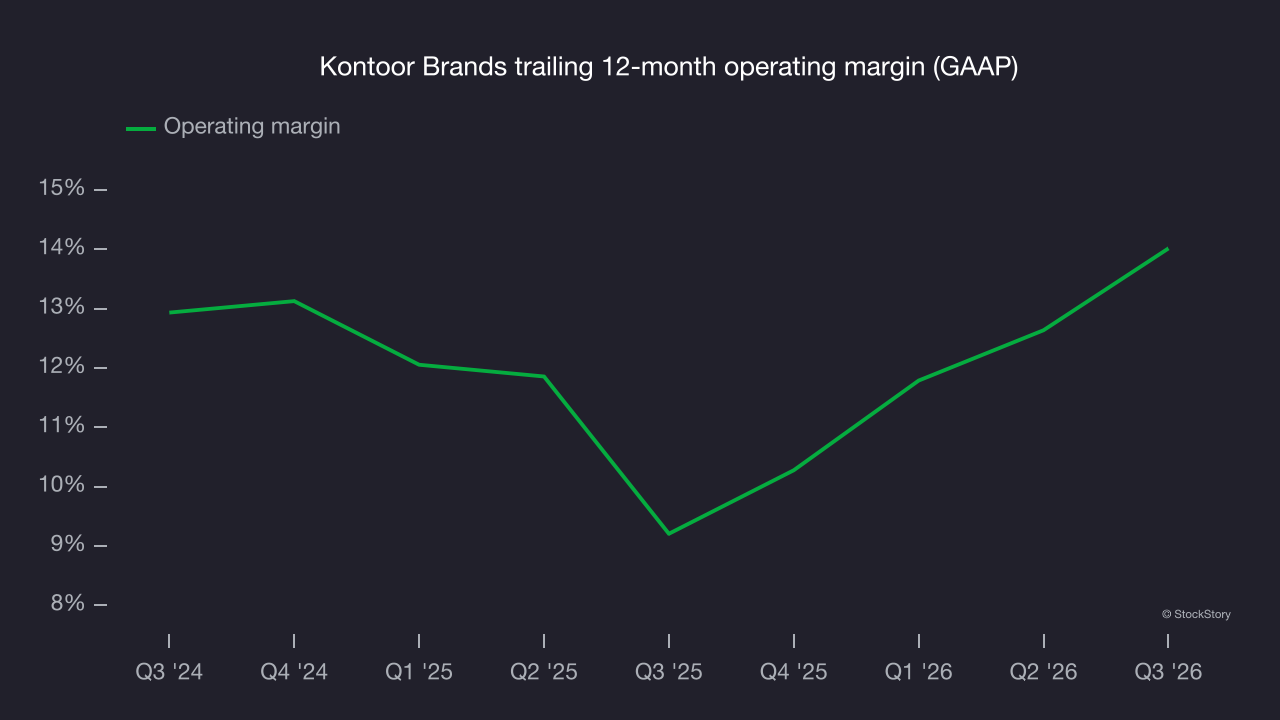
This quarter, Kontoor Brands generated an operating margin of 11.2%, up 5.6 percentage points year on year. This increase was a positive development and shows it was more efficient.
Earnings per share
We track the long-term change in earnings per share (EPS) for the same reason as long-term revenue growth. Compared to revenue, however, EPS highlights whether a company’s growth is profitable.
Kontoor Brands’s EPS grew at a 5% compounded annual growth rate over the last five years. This performance was better than its revenue growth but doesn’t tell us much about its business quality because its operating margin improvement lagged that of peers.
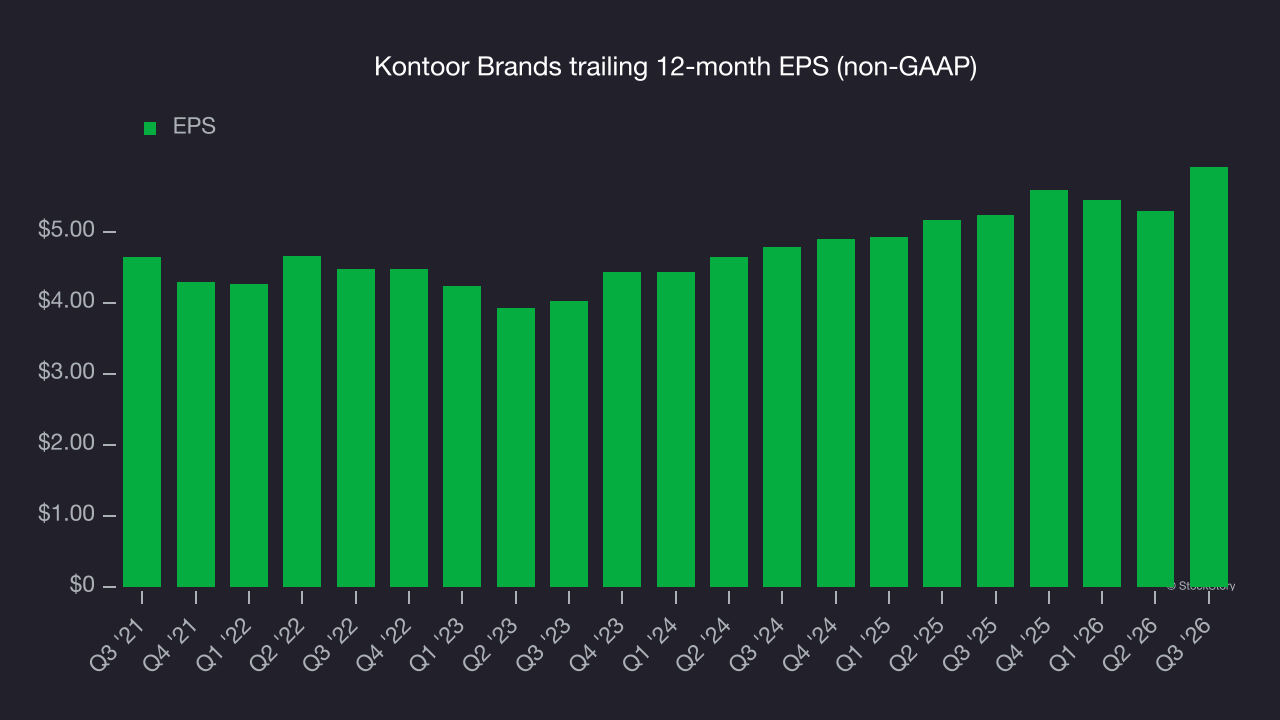
In Q3, Kontoor Brands reported adjusted EPS of $2.06, up from $1.44 in the same quarter last year. This result easily cleared analysts’ consensus estimates. Over the next 12 months, Wall Street expects Kontoor Brands’s full-year EPS to grow 5.5% from $5.91 to $6.23, according to S&P.
Key takeaways from Kontoor Brands’s Q3 results
Kontoor Brands delivered a mixed Q3: EPS and EBITDA beat Wall Street’s consensus estimates, but revenue came in slightly below expectations and full-year revenue guidance also fell slightly short. Shares remained flat at $81.48 immediately after the report.
Kontoor Brands’ latest quarter is only one part of assessing its longer-term business quality. Quality, when combined with valuation, can help determine if the stock is a buy. Read the full research report here (it’s free).