Fast food chain El Pollo Loco (NASDAQ: LOCO) met Wall Street’s revenue expectations in Q3 2026, with revenue up 3.9% year on year to $126.3 million. Its non-GAAP profit of $0.24 per share was in line with analysts’ consensus estimates.
For more on El Pollo Loco, read our free full research report.
El Pollo Loco (LOCO) Q3 2026 highlights:
- Revenue $126.3 million vs S&P analysts’ consensus estimates of $126.9 million (3.9% year-on-year growth, in line)
- Adjusted EPS $0.24 vs S&P analysts’ consensus estimates of $0.24 (in line)
- Adjusted EBITDA $17.12 million vs analysts’ consensus estimates of $17.51 million (13.6% margin, 2.2% miss)
- EBITDA guidance $69 million at the midpoint for the full year, below analysts’ consensus estimates of $69.82 million
- Operating margin 8.1%, down from 9.4% in the same quarter last year
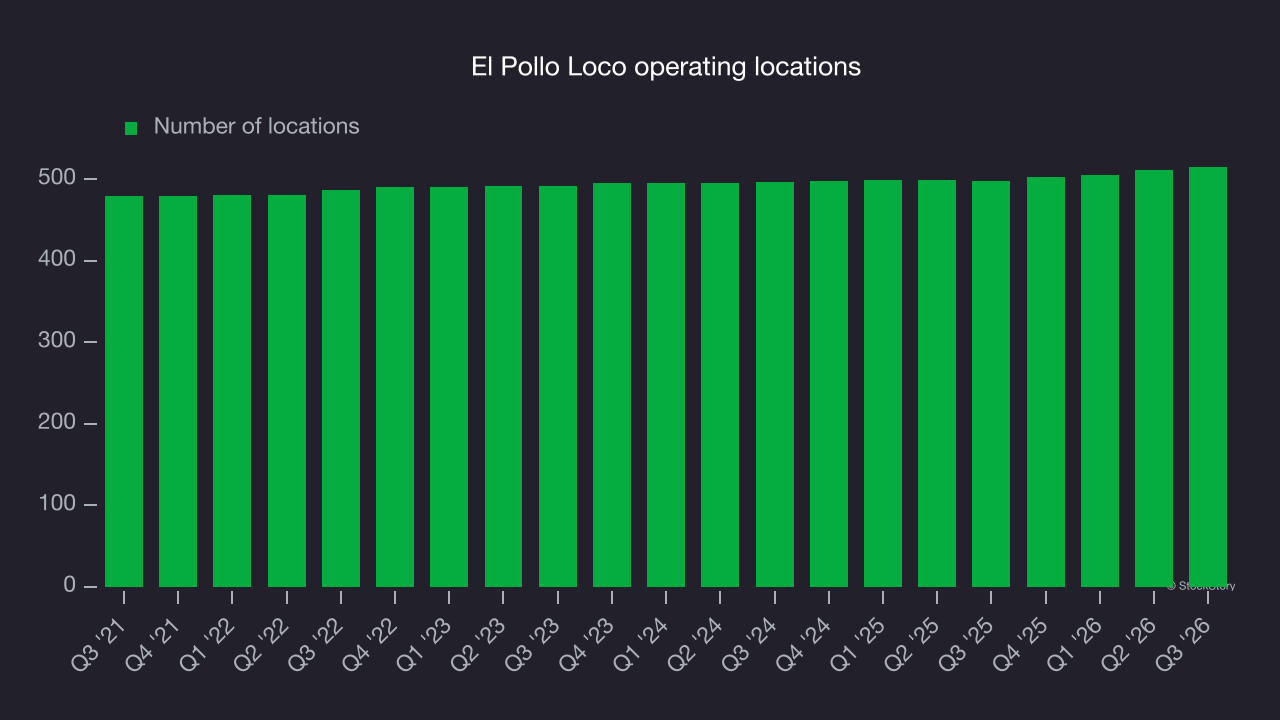
- Locations 515 at quarter end, up from 498 in the same quarter last year
- Same-store sales rose 5% year on year (-0.8% in the same quarter last year)
- Market capitalization $501.2 million
“We are thrilled to have delivered another strong quarter for El Pollo Loco. In addition to positive traffic growth, comparable sales were positive for the fourth straight quarter,” said Liz Williams, Chief Executive Officer of El Pollo Loco Holdings, Inc. “Our strategy continues to deliver results, our marketing and innovation brought fresh energy to the brand, while our quality, value and improved service delivered a better experience for our guests. As we look ahead, our goal remains the same: Build traffic that lasts, protect the margin discipline and strong unit economics we’ve built, and bring El Pollo Loco to new communities, one great restaurant at a time.”
Revenue growth
Reviewing a company’s long-term revenue performance reveals insights into its quality. Any business can have short-term success, but a top-tier one grows for years.
With $505.6 million in revenue over the past 12 months, El Pollo Loco is a small restaurant chain, which sometimes brings disadvantages compared to larger competitors benefiting from better brand awareness and economies of scale.
El Pollo Loco’s 2% annualized revenue growth over the last seven years was weak as it barely increased revenue at existing, established dining locations.
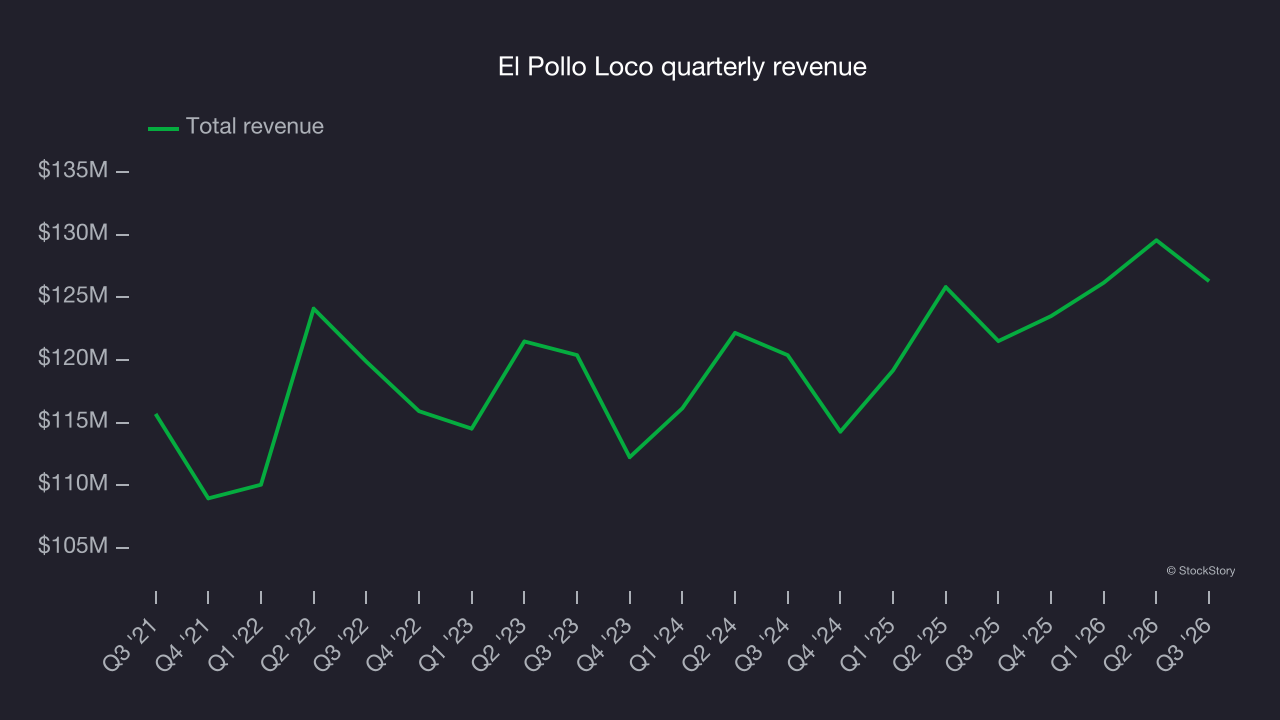
This quarter, El Pollo Loco grew its revenue by 3.9% year on year, and its $126.3 million in revenue was in line with Wall Street’s consensus estimates.
Looking ahead, sell-side analysts expect revenue to grow 1.7% over the next 12 months, according to S&P, similar to its seven-year rate. This projection is underwhelming and suggests its newer menu offerings will not accelerate its top-line performance yet.
Restaurant performance
Number of restaurants
The number of dining locations a restaurant chain operates is a critical driver of how quickly company-level revenue can grow.
El Pollo Loco operated 515 locations in the latest quarter. It has generally opened new restaurants over the last two years and averaged 1.3% annual growth, faster than the broader restaurant sector.
When a chain opens new restaurants, it usually means it’s investing for growth because there’s healthy demand for its meals and there are markets where its concepts have few or no locations.
Same-store sales
A company’s restaurant base only paints one part of the picture. When demand is high, it makes sense to open more. But when demand is low, it’s prudent to close some locations and use the money in other ways. Same-store sales provide a deeper understanding of this issue because they measure organic growth at restaurants open for at least a year.
Demand at El Pollo Loco’s existing dining locations has been relatively stable over the last two years but trailed that of most restaurant chains. On average, the company’s same-store sales have grown by 2% per year. This performance suggests it should consider improving its foot traffic and efficiency before expanding its restaurant base.
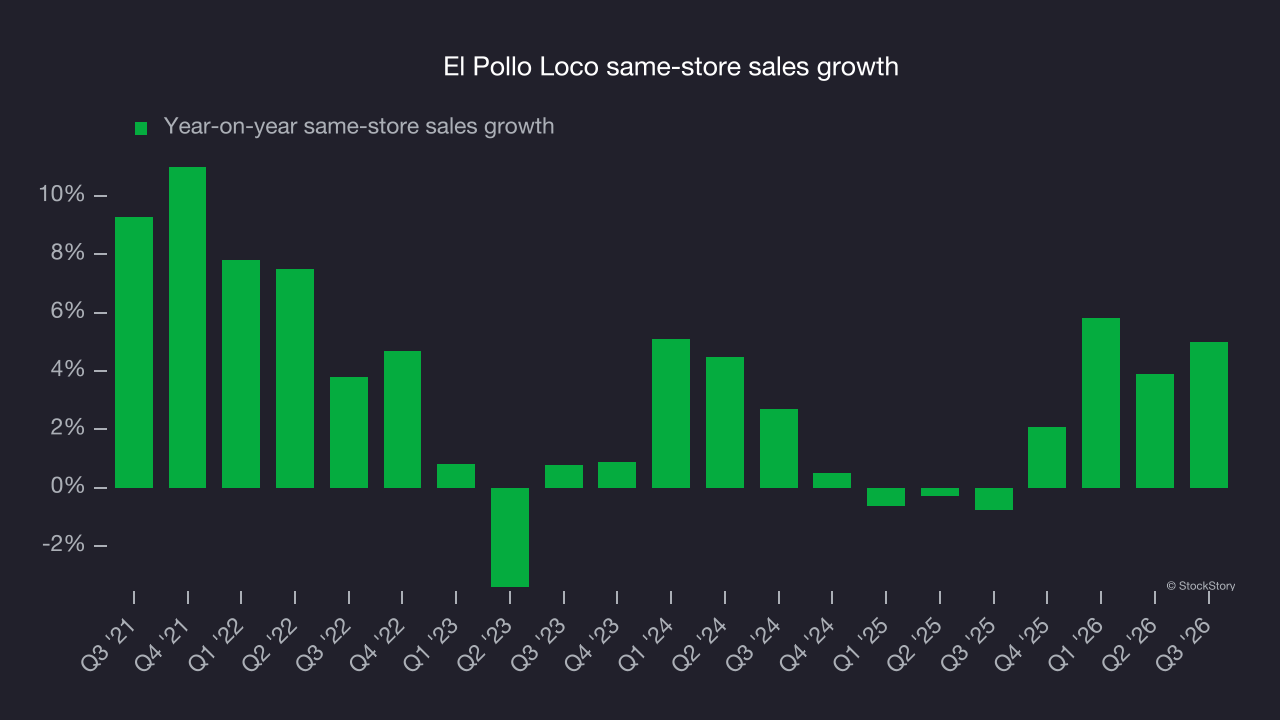
In the latest quarter, El Pollo Loco’s same-store sales rose 5% year on year. This growth marked an acceleration from its historical levels, a positive sign.
Key takeaways from El Pollo Loco’s Q3 results
El Pollo Loco’s EBITDA miss and full-year EBITDA guidance slightly below Wall Street’s consensus estimates made for a softer quarter, despite same-store sales topping analysts’ consensus expectations. Shares fell 3.7% to $15.87 immediately after the results.
When deciding whether to buy the stock, consider valuation, business quality and the latest earnings. Read the full research report here (it’s free).