Biotechnology company United Therapeutics (NASDAQ: UTHR) reported Q3 2026 results topping the market’s revenue expectations, with revenue up 4.1% year on year to $832.5 million. Its GAAP profit of $5.71 per share was 5.5% below analysts’ consensus estimates.
For more on United Therapeutics, read our free full research report.
United Therapeutics (UTHR) Q3 2026 highlights:
- Revenue $832.5 million vs S&P analysts’ consensus estimates of $782.6 million (4.1% year-on-year growth, 6.4% beat)
- EPS (GAAP) $5.71 vs analysts’ consensus estimates of $6.04 (5.5% miss)
- Operating margin 37%, down from 48.6% in the same quarter last year
- Market capitalization $25.79 billion
“United Therapeutics is entering a period of extraordinary growth. We are advancing a portfolio of new therapies designed to exponentially increase the number of patients we can serve,” said Martine Rothblatt, Ph.D., Chairperson and Chief Executive Officer of United Therapeutics.
Revenue growth
A company’s long-term revenue performance can indicate its overall quality. Any business can experience short-term success, but top-performing ones sustain growth for years. United Therapeutics’s 14% annualized revenue growth over the last five years was solid. Its growth beat the average healthcare company and shows its offerings resonate with customers.
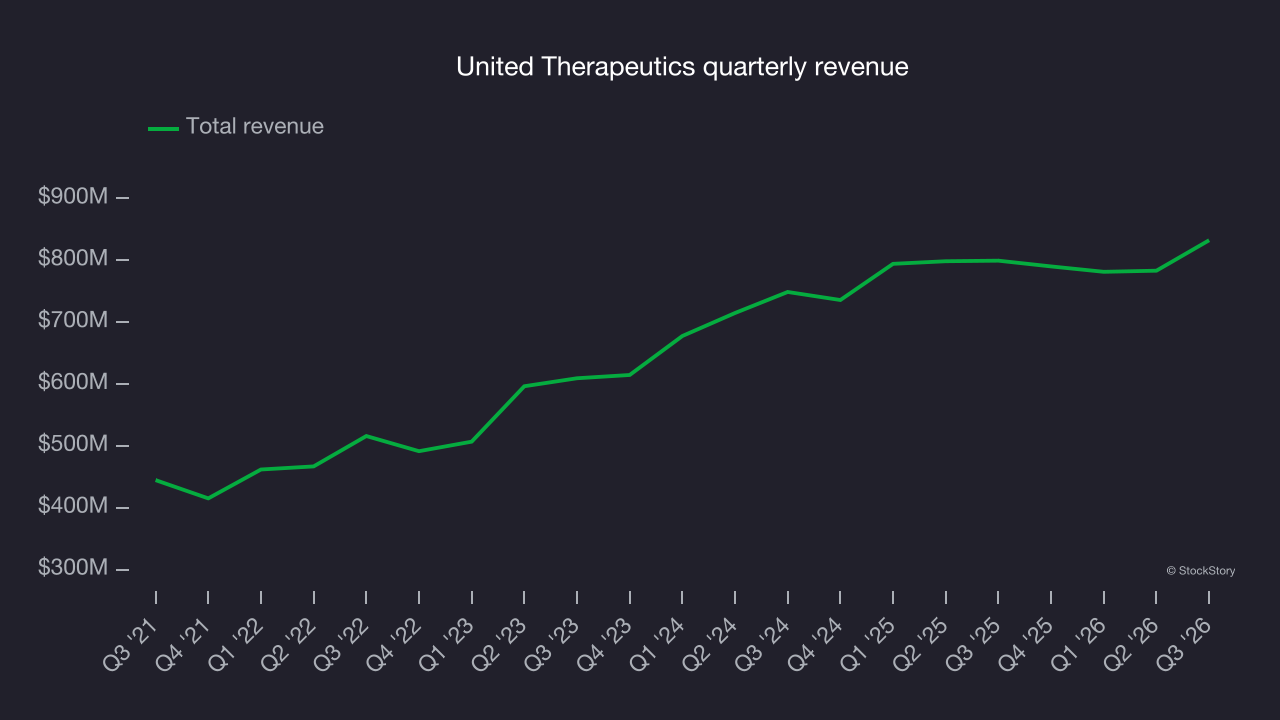
Long-term growth matters most, but within healthcare, a half-decade historical view may miss recent innovations or disruptive industry trends. United Therapeutics’s annualized revenue growth of 7.5% over the last two years is below its five-year trend, but the results were still respectable. 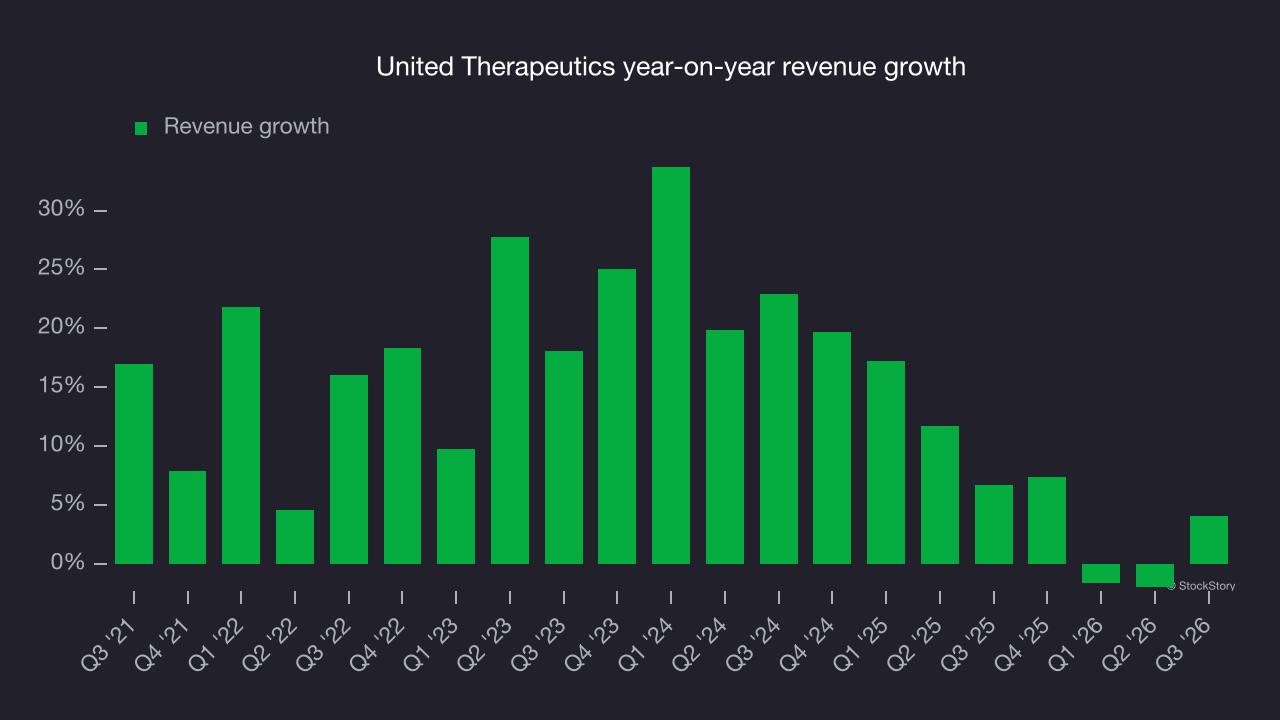
This quarter, United Therapeutics reported modest year-on-year revenue growth of 4.1% but beat Wall Street’s consensus estimates by 6.4%.
Looking ahead, sell-side analysts expect revenue to grow 4.5% over the next 12 months, according to S&P, a deceleration versus the last two years. This projection is underwhelming and implies its products and services will see some demand headwinds. Still, the company is performing well on other measures of financial health.
Adjusted operating margin
United Therapeutics has performed well over the last five years. It demonstrated high profitability for a healthcare business, with an average adjusted operating margin of 52.2%.
United Therapeutics’s adjusted operating margin decreased by 10.6 percentage points over the last five years. The company’s two-year trajectory also shows it failed to return profitability to its peak, as its margin fell by 7.2 percentage points. This was a poor performance, showing that expenses were rising and it couldn’t pass those costs on to customers.
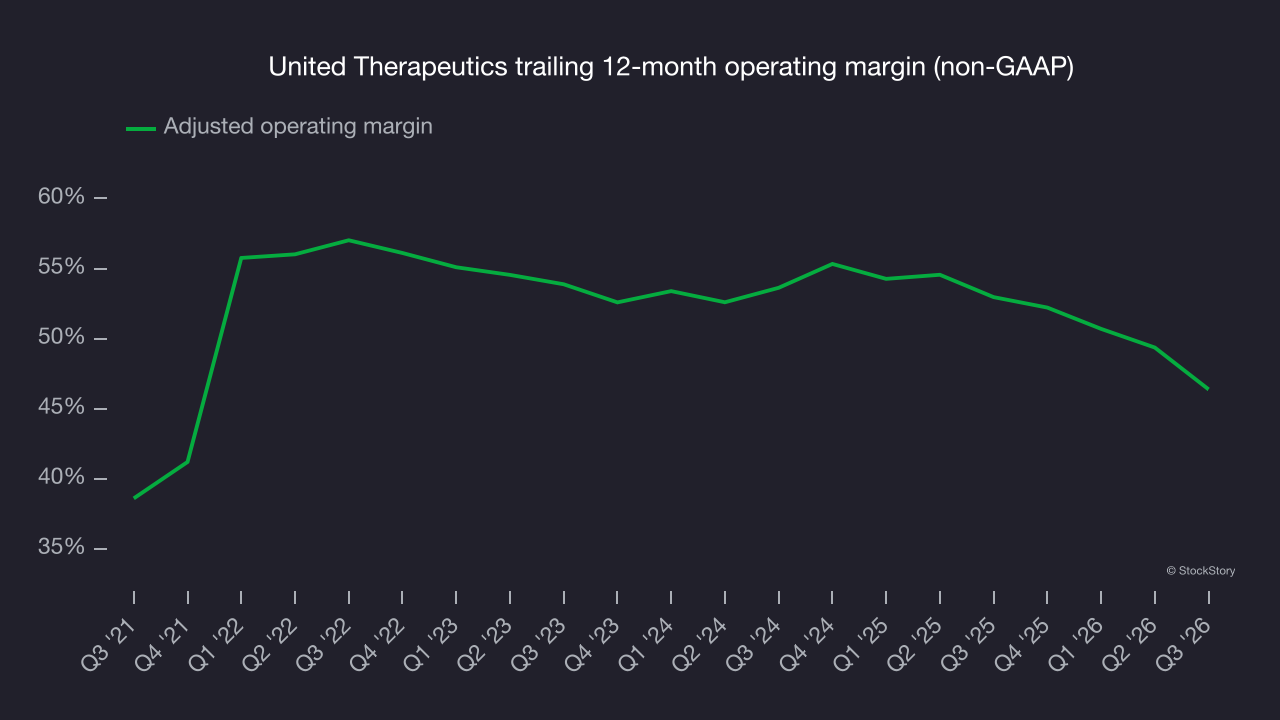
This quarter, United Therapeutics generated an adjusted operating margin of 41.9%, down 11.6 percentage points year on year. This contraction shows it was less efficient because its expenses grew faster than its revenue.
Earnings per share
Revenue trends explain a company’s historical growth, but the long-term change in earnings per share, or EPS, points to the profitability of that growth. For example, a company could inflate its revenue through excessive spending on advertising and promotions.
United Therapeutics’s EPS grew at a 21.9% compounded annual growth rate over the last five years, higher than its 14% annualized revenue growth. However, this alone doesn’t tell us much about its business quality because its adjusted operating margin didn’t improve.
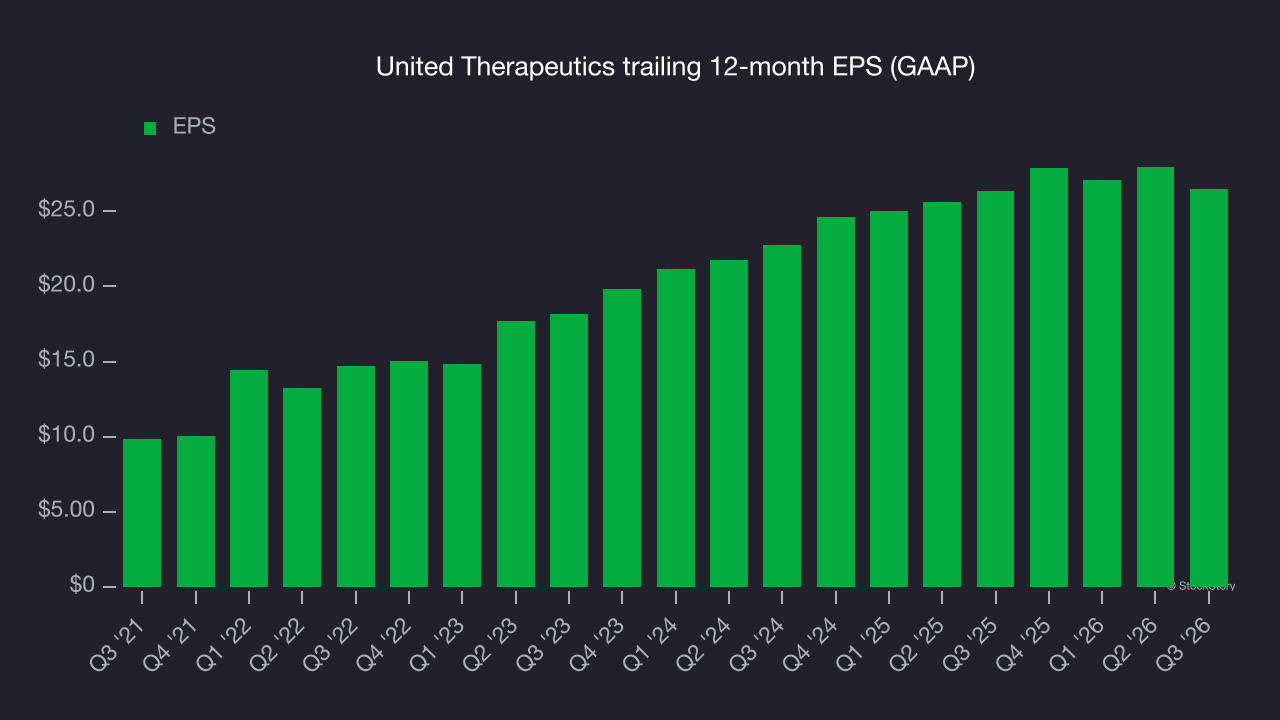
A closer look at United Therapeutics’s earnings helps explain the drivers of its performance. A five-year view shows that United Therapeutics has repurchased its stock, shrinking its share count by 4.8%. This indicates its EPS outperformed its revenue not because of increased operational efficiency but because of financial engineering, as buybacks boost per share earnings. 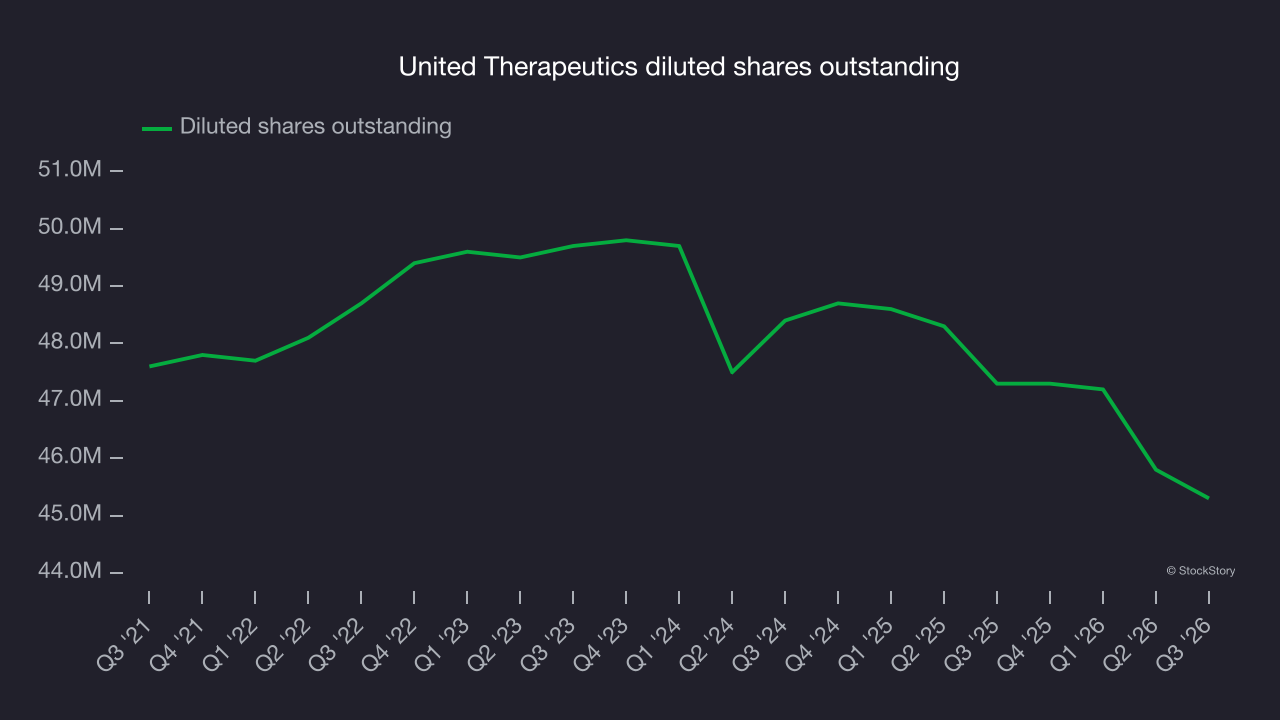
In Q3, United Therapeutics reported EPS of $5.71, down from $7.16 in the same quarter last year. This result missed analysts’ consensus estimates, but long-term EPS growth matters more than short-term movements. Over the next 12 months, Wall Street expects United Therapeutics’s full-year EPS to grow 10.1% from $26.51 to $29.19, according to S&P.
Key takeaways from United Therapeutics’s Q3 results
United Therapeutics delivered a sizable revenue beat against analysts’ consensus estimates, but EPS missed. The quarter had some key positives despite that earnings shortfall. Shares surged 5.9% to $636.59 immediately after the results.
The latest quarter matters when deciding whether United Therapeutics is a buy at its current price, but longer-term fundamentals and valuation matter much more. For more on United Therapeutics, read the full research report here (it’s free).