General contracting company Tutor Perini (NYSE: TPC) announced better-than-expected revenue in Q3 2026, with revenue up 21.5% year on year to $1.72 billion. Its non-GAAP profit of $1.83 per share was 36.6% above analysts’ consensus estimates.
For more on Tutor Perini, read our free full research report.
Tutor Perini (TPC) Q3 2026 highlights:
- Revenue $1.72 billion vs S&P analysts’ consensus estimates of $1.63 billion (21.5% year-on-year growth, 5.7% beat)
- Adjusted EPS $1.83 vs S&P analysts’ consensus estimates of $1.34 (36.6% beat)
- Adjusted EPS guidance Management raised its full-year adjusted EPS guidance to $6 at the midpoint, a 13.2% increase
- Operating margin 7.3%, up from 2.9% in the same quarter last year
- Free cash flow margin 16.9%, similar to the same quarter last year
- Backlog $20.35 billion at quarter end, down 5.9% year on year
- Market capitalization $4.36 billion
“Tutor Perini delivered another quarter of excellent results, highlighted by record operating cash flow, revenue, operating income and earnings, as well as solid operating margins across all segments. Our results demonstrated the continued momentum in our business, as well as the significant earnings and cash flow potential embedded in our near-record backlog. As a result of our record performance and continued favorable outlook, we are raising our full-year 2026 adjusted EPS guidance to $5.90 to $6.10,” commented Gary Smalley, Tutor Perini's Chief Executive Officer and President.
Revenue growth
A company’s long-term revenue performance is one signal of its overall quality. Any business can experience short-term success, but top-performing ones sustain growth for years. Over the last five years, Tutor Perini grew its revenue at a tepid 4.8% compounded annual growth rate. That was an underwhelming result compared to the rest of the industrials sector, but there are still things to like about Tutor Perini.
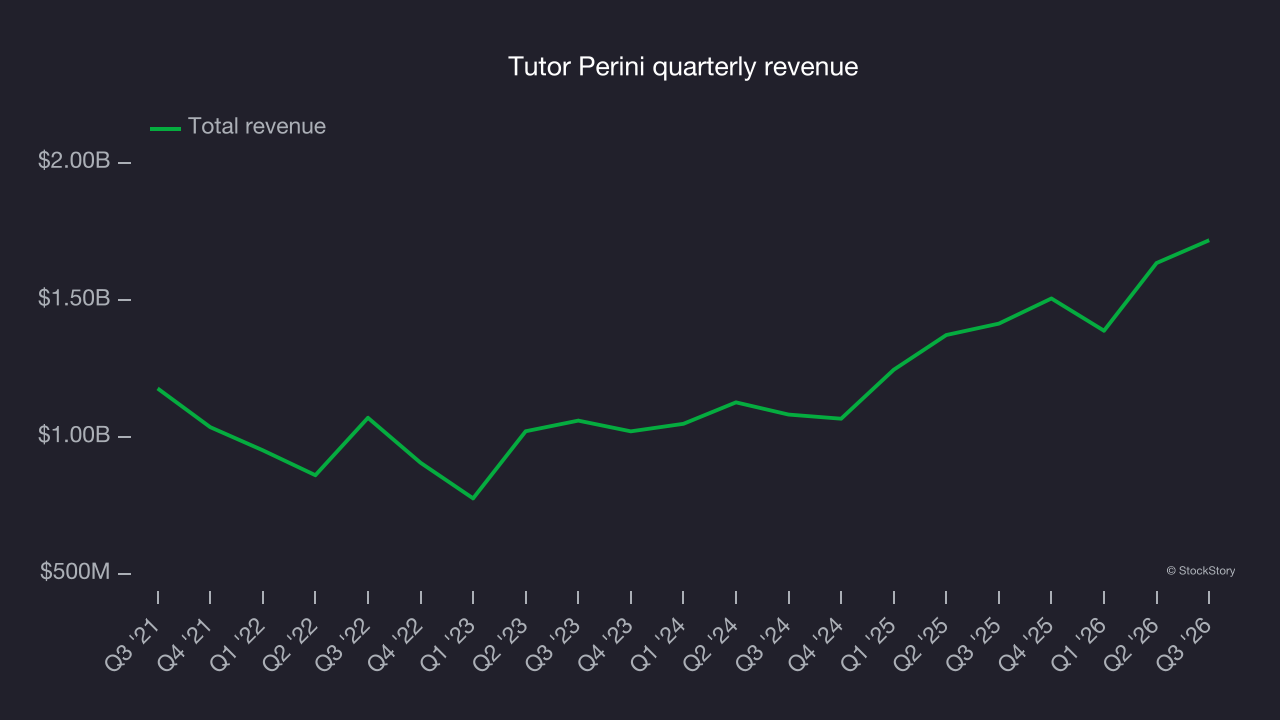
Long-term growth is the most important, but within industrials, a half-decade historical view may miss new industry trends or demand cycles. Tutor Perini’s annualized revenue growth of 20.9% over the last two years is above its five-year trend, suggesting its demand recently accelerated. 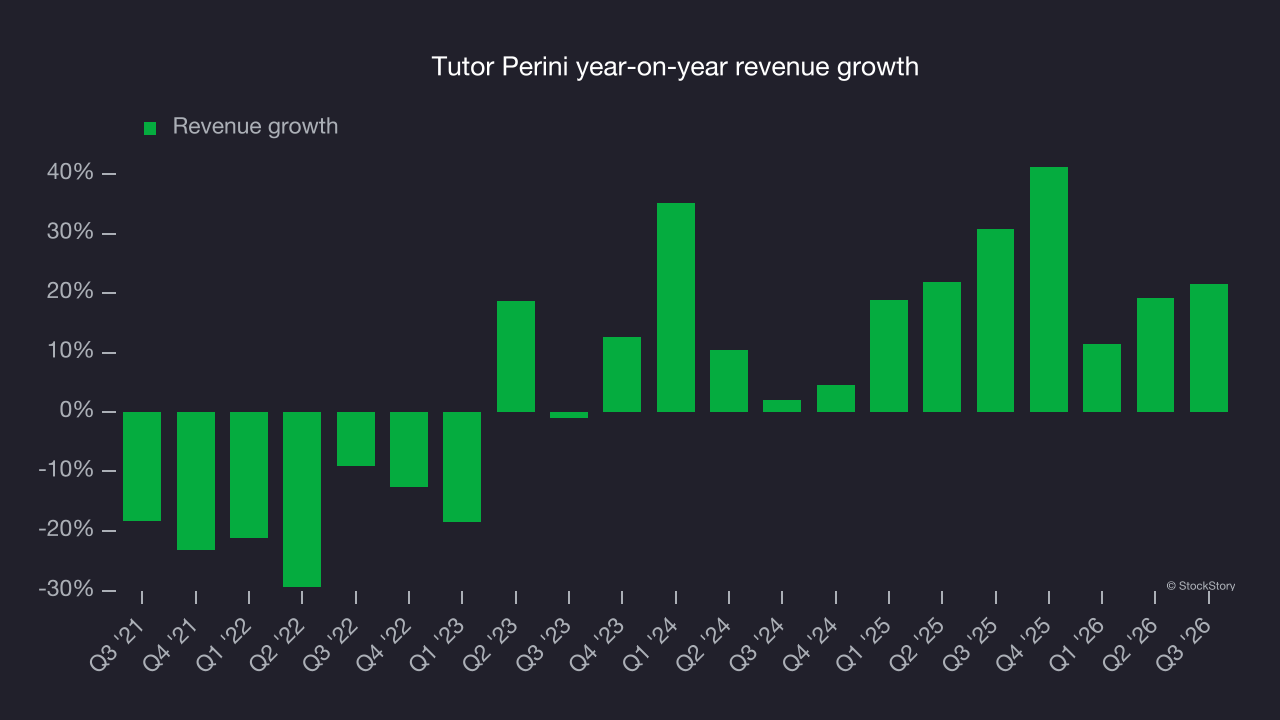
The company’s backlog, or the value of its outstanding orders that have not yet been executed or delivered, helps explain its revenue dynamics. Tutor Perini’s backlog reached $20.35 billion in the latest quarter and averaged 11% year-on-year growth over the last two years. Revenue growth outpaced backlog growth, indicating that the company fulfilled orders at a faster rate than it added new orders to the backlog. This implies Tutor Perini was operating efficiently but raises questions about the health of its revenue pipeline. 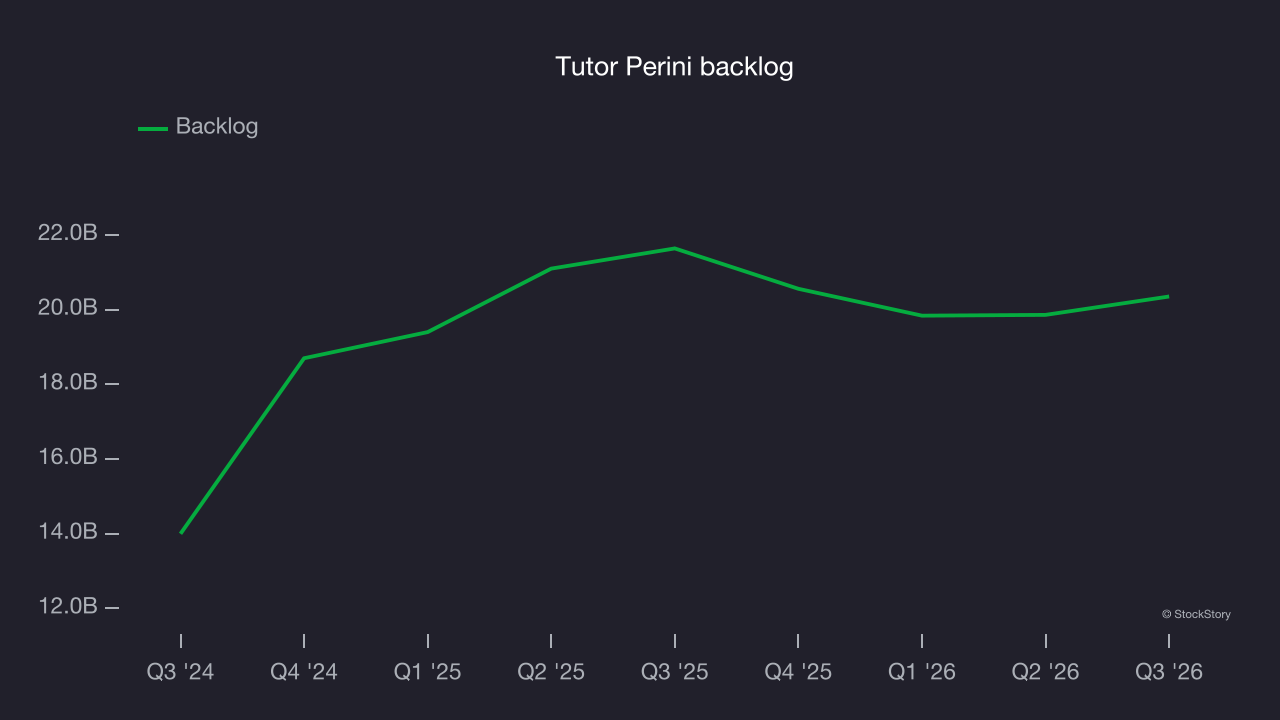
This quarter, Tutor Perini reported strong year-on-year revenue growth of 21.5%, and its $1.72 billion in revenue topped Wall Street’s consensus estimates by 5.7%.
Looking ahead, sell-side analysts expect revenue to grow 11% over the next 12 months, according to S&P, a deceleration versus the last two years. Still, this projection is healthy and implies the market is forecasting success for its products and services.
Operating margin
Tutor Perini was roughly breakeven when averaging the last five years of quarterly operating profits, inadequate for an industrials business. That outcome is unsurprising given its low gross margin baseline.
On the positive side, Tutor Perini’s operating margin rose by 6.9 percentage points over the last five years, as its revenue growth provided operating leverage.
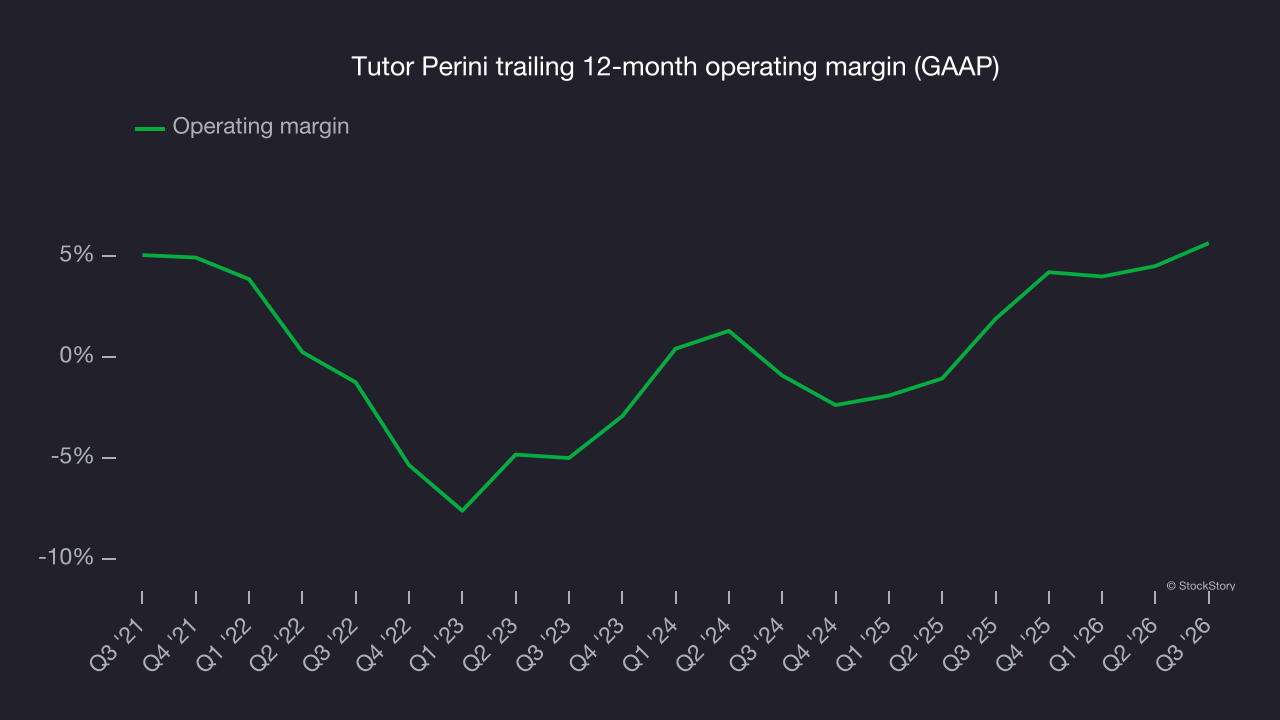
In Q3, Tutor Perini generated an operating margin of 7.3%, up 4.4 percentage points year on year. The increase was encouraging, and the larger rise in operating margin than in gross margin suggests it was more efficient with expenses such as marketing, research and development and administrative overhead.
Earnings per share
We track the long-term change in earnings per share, or EPS, for the same reason as long-term revenue growth. Compared to revenue, however, EPS highlights whether a company’s growth is profitable.
Tutor Perini’s EPS grew at a 21.9% compounded annual growth rate over the last five years, higher than its 4.8% annualized revenue growth. This indicates the company became more profitable on a per-share basis as it expanded.
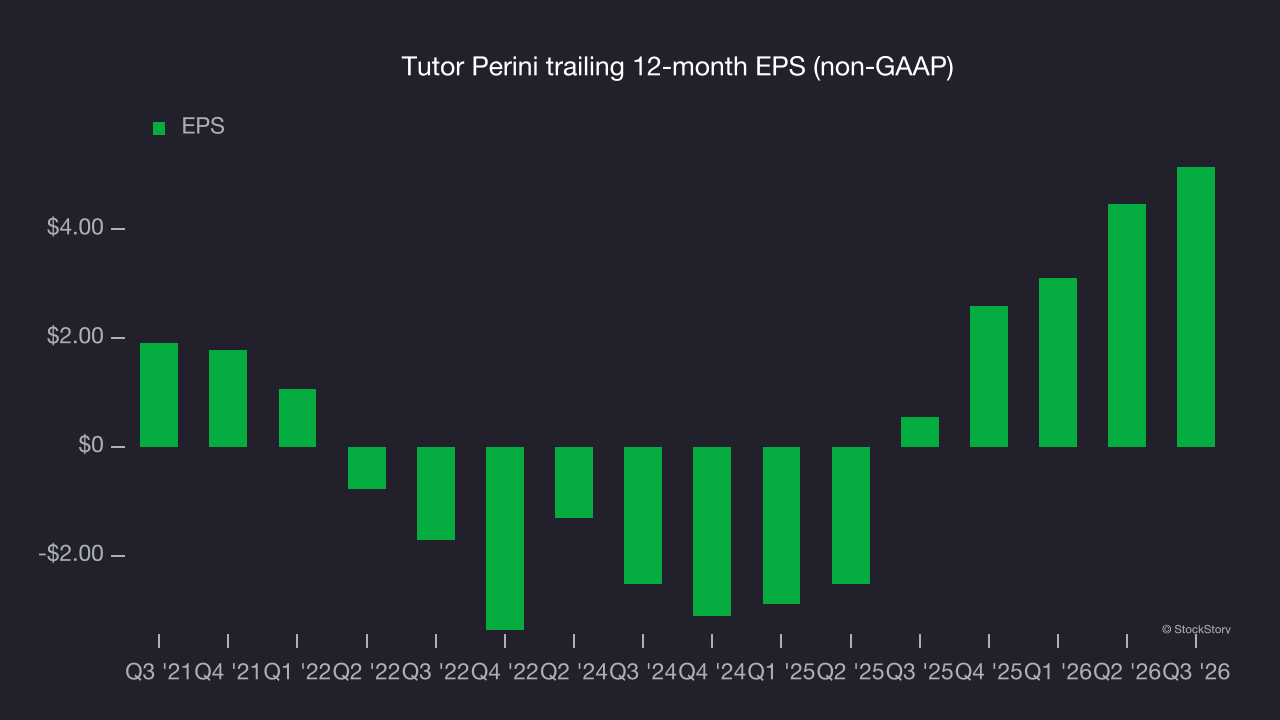
A closer look at Tutor Perini’s earnings helps explain its performance. As mentioned earlier, Tutor Perini’s operating margin expanded by 6.9 percentage points over the last five years. This was the most relevant factor, aside from the revenue impact, behind its higher earnings; interest expenses and taxes can also affect EPS but reveal less about a company’s fundamentals.
As with revenue, we analyze EPS over a shorter period to see if we are missing a change in the business.
Tutor Perini’s two-year annual EPS growth of 101% was higher than its five-year trend. That acceleration is a positive sign, especially given the already high base.
In Q3, Tutor Perini reported adjusted EPS of $1.83, up from $1.15 in the same quarter last year. The figure came in well above analysts’ consensus estimates, a positive result for shareholders. Over the next 12 months, Wall Street expects Tutor Perini’s full-year EPS to grow 9.2% from $5.14 to $5.61, according to S&P.
Key takeaways from Tutor Perini’s Q3 results
A wide revenue beat and better-than-expected EPS made this a good quarter for Tutor Perini. Revenue topped Wall Street’s consensus estimates by a wide margin, and earnings also exceeded analysts’ consensus expectations. Investors were likely hoping for more, as shares edged lower 1.2% to $81.88 immediately after the release.
Should you invest in Tutor Perini? What happened in the latest quarter matters, but not as much as longer-term business quality and valuation when deciding whether to invest in this stock. Read our full research report here for more on these factors (it’s free).