What a brutal six months it’s been for Stewart Information Services. The stock has dropped 34.4% and now trades at $44.74, rattling many shareholders. This was partly due to its softer quarterly results and may have investors wondering how to approach the situation.
Is now the time to buy Stewart Information Services, or should you be careful about including it in your portfolio? Dive into our full research report to see our analyst team’s opinion, it’s free.
Why is Stewart Information Services not exciting?
Even with the cheaper entry price, we’re cautious about Stewart Information Services. Here are three reasons you should be careful with STC, plus one stock we’d rather own.
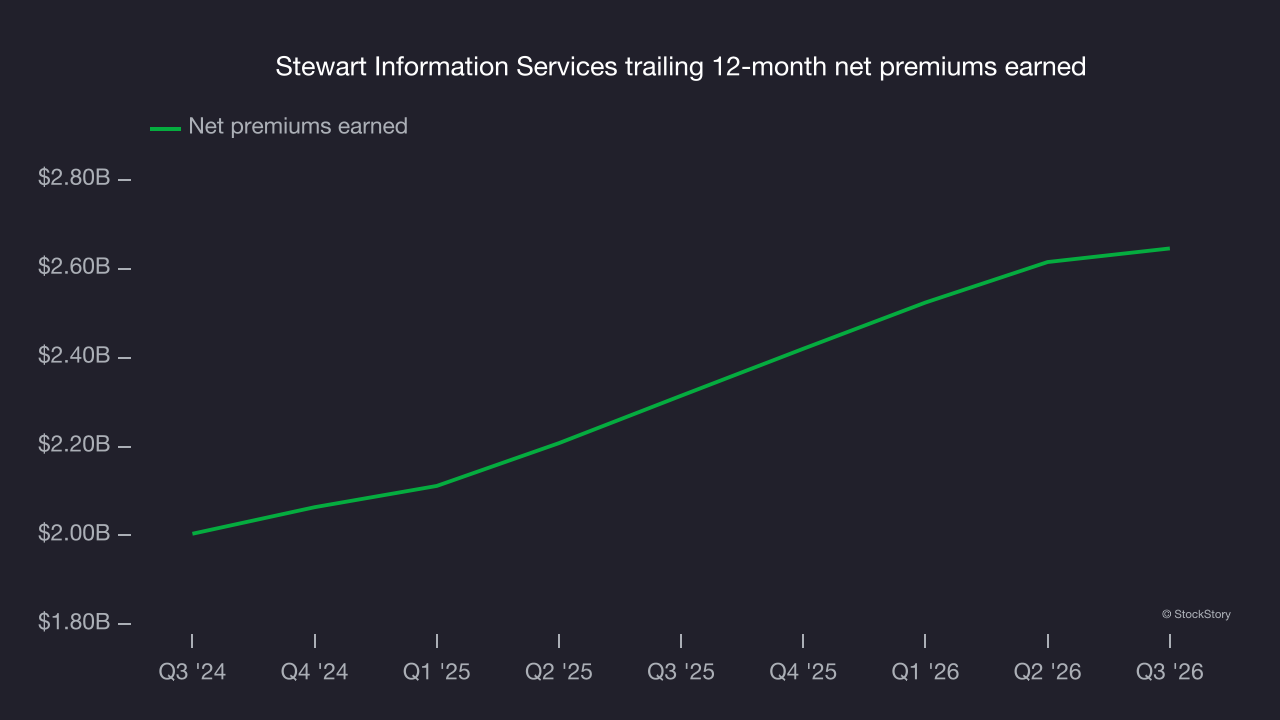
1. Declining net premiums earned reflect weakness
When insurers sell policies, they protect themselves from extremely large losses or an outsized accumulation of losses with reinsurance (insurance for insurance companies). Net premiums earned are therefore net of what’s ceded to reinsurers as a risk mitigation and transfer strategy.
Stewart Information Services’s net premiums earned has declined by 1.3% annually over the last five years, much worse than the broader insurance industry. This shows that policy underwriting underperformed its other business lines.
2. EPS trending down
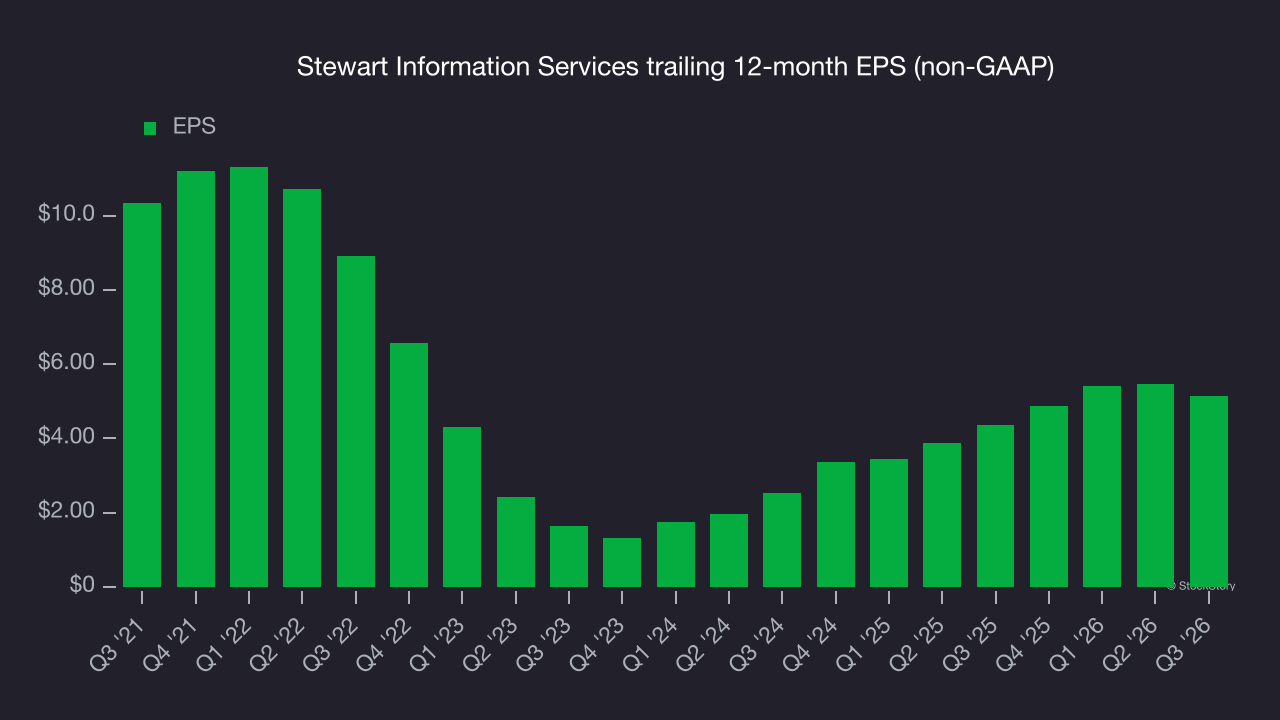
Analyzing the long-term change in earnings per share (EPS) shows whether a company’s incremental sales were profitable — for example, revenue could be inflated through excessive spending on advertising and promotions.
Sadly for Stewart Information Services, its EPS declined by 13% annually over the last five years while its revenue grew by 1.9%. This tells us the company became less profitable on a per-share basis as it expanded.
Final judgment
Stewart Information Services isn’t a terrible business, but it doesn’t pass our quality test. Following the recent decline, the stock trades at 0.8× forward P/B (or $44.74 per share). While this valuation is fair, the upside isn’t great compared to the potential downside. We’re fairly confident there are better investments elsewhere. We’d suggest looking at an all-weather company that owns household favorite Taco Bell.
High-quality stocks for all market conditions
WHILE YOU’RE HERE: Top 9 Market-Beating Stocks. The best stocks don’t just beat the market once. They do it again. And again. Robust revenue growth, rising free cash flow, returns on capital that leave their competition in the dust. The market has already rewarded these businesses.
But our AI platform says the party isn’t over. Find out which 9 stocks made the cut this week — FREE. Get Our Top 9 Market-Beating Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Comfort Systems (+1,154% between June 2020 and June 2025). Find your next big winner with StockStory today.