Building and construction materials manufacturer Owens Corning (NYSE: OC) fell short of the market’s revenue expectations in Q3 2026, with revenue falling 7.3% year on year to $2.49 billion. Next quarter’s revenue guidance of $2.1 billion underwhelmed, coming in 5.6% below analysts’ consensus estimates. Its non-GAAP profit of $2.44 per share was 19.9% below analysts’ consensus estimates.
For more on Owens Corning, read our free full research report.
Owens Corning (OC) Q3 2026 highlights:
- Revenue $2.49 billion vs S&P analysts’ consensus estimates of $2.62 billion (7.3% year-on-year decline, 5.2% miss)
- Adjusted EPS $2.44 vs S&P analysts’ consensus estimates of $3.05 (19.9% miss)
- Adjusted EBITDA $489 million vs analysts’ consensus estimates of $554.1 million (19.6% margin, 11.7% miss)
- Revenue guidance $2.1 billion at the midpoint for Q4 2026, below analysts’ consensus estimates of $2.23 billion
- Operating margin -6.1%, up from -12.2% in the same quarter last year
- Free cash flow margin 25%, down from 28% in the same quarter last year
- Market capitalization $9.31 billion
“During the quarter, challenging residential market conditions were further impacted by a second consecutive year of weak storm activity and rapidly rising transportation and input material costs. Despite these pressures, our team demonstrated disciplined commercial and operational execution, delivering a resilient margin and strong cash flow,” said Chair and Chief Executive Officer Brian Chambers. “Our performance reflects the fundamentally stronger company we have built, and we remain focused on executing our strategy and leveraging our unique OC Advantages™ to create additional long-term value for our customers and shareholders.”
Revenue growth
A company’s long-term revenue performance is one signal of its overall quality. Any business can deliver a good quarter or two, but the best consistently grow over the long term. Over the last five years, Owens Corning grew its revenue at a sluggish 3.1% compounded annual growth rate, falling short of the industrials sector benchmark.
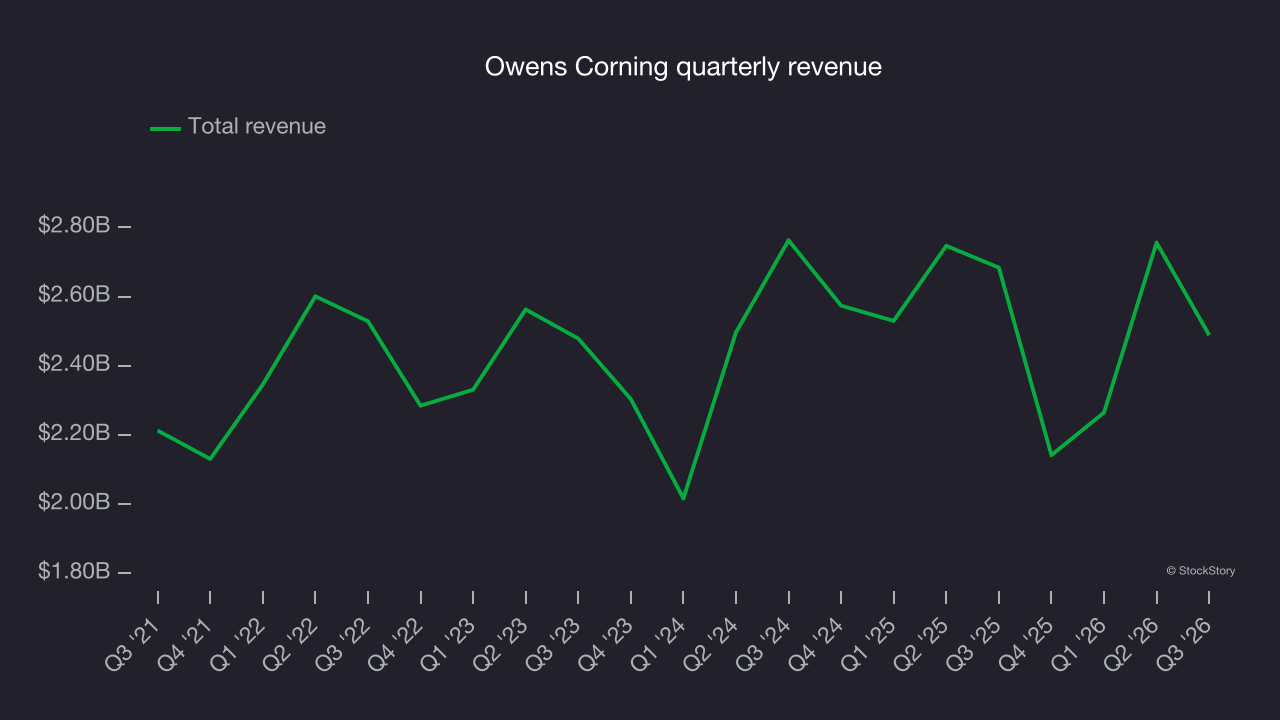
Long-term growth matters most, but within industrials, a half-decade historical view may miss cycles, industry trends or a company capitalizing on catalysts such as a new contract win or a successful product line. Owens Corning’s recent performance shows its demand has slowed as its revenue was flat over the last two years. 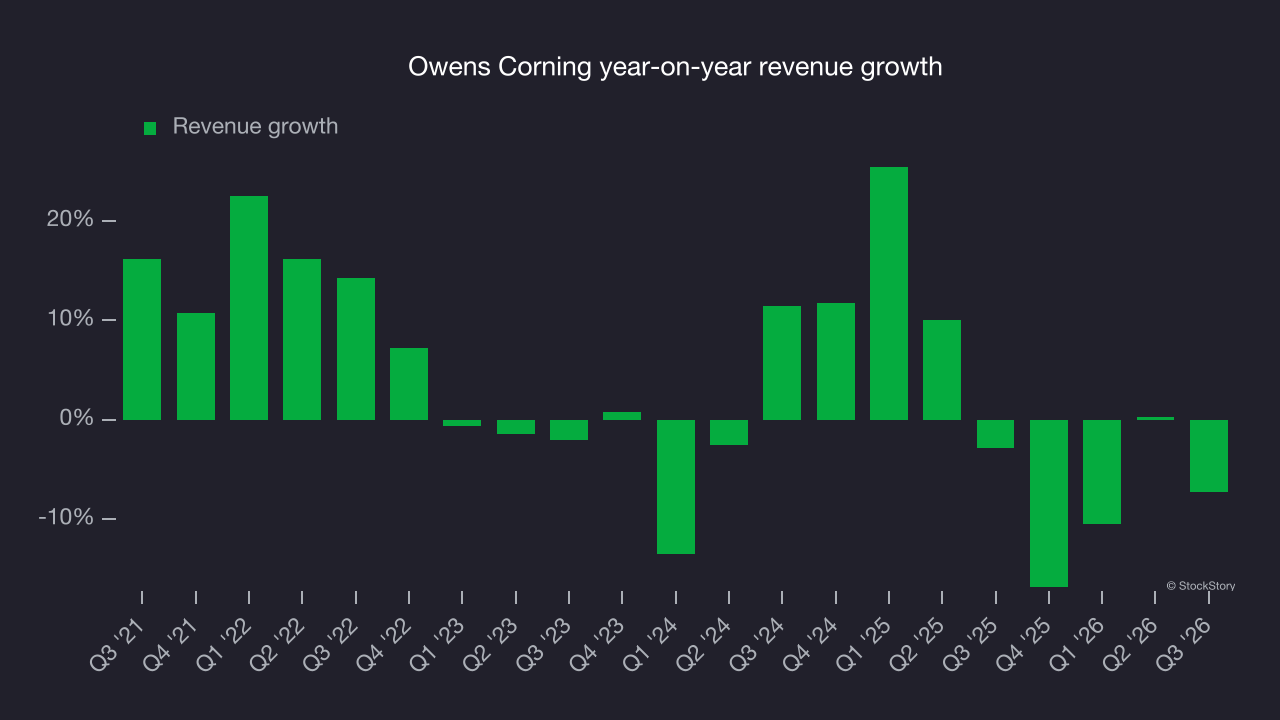
This quarter, Owens Corning missed Wall Street’s consensus estimates and reported an uninspiring 7.3% year-on-year revenue decline, generating $2.49 billion of revenue. Company management is guiding for a 2% year-on-year decline in revenue next quarter.
Looking further ahead, sell-side analysts expect revenue to grow 4.3% over the next 12 months, according to S&P. While this projection indicates its newer products and services will improve revenue performance, it is still below the sector average.
Operating margin
Operating margin is a key measure of profitability. Think of it as net income, the bottom line, excluding the impact of taxes and interest on debt, which are less connected to business fundamentals.
Owens Corning has been an efficient company over the last five years. It was one of the more profitable businesses in the industrials sector, with an average operating margin of 12.5%. This result was particularly impressive given its low gross margin, which is mostly a factor of what it sells and requires substantial shifts to change meaningfully. Companies have more control over their operating margins, and high operating margins alongside low gross margins indicate well-managed operations.
Analyzing the trend in its profitability, Owens Corning’s operating margin decreased by 17 percentage points over the last five years. This raises questions about the company’s expense base because its revenue growth should have given it leverage on its fixed costs, resulting in better economies of scale and profitability.
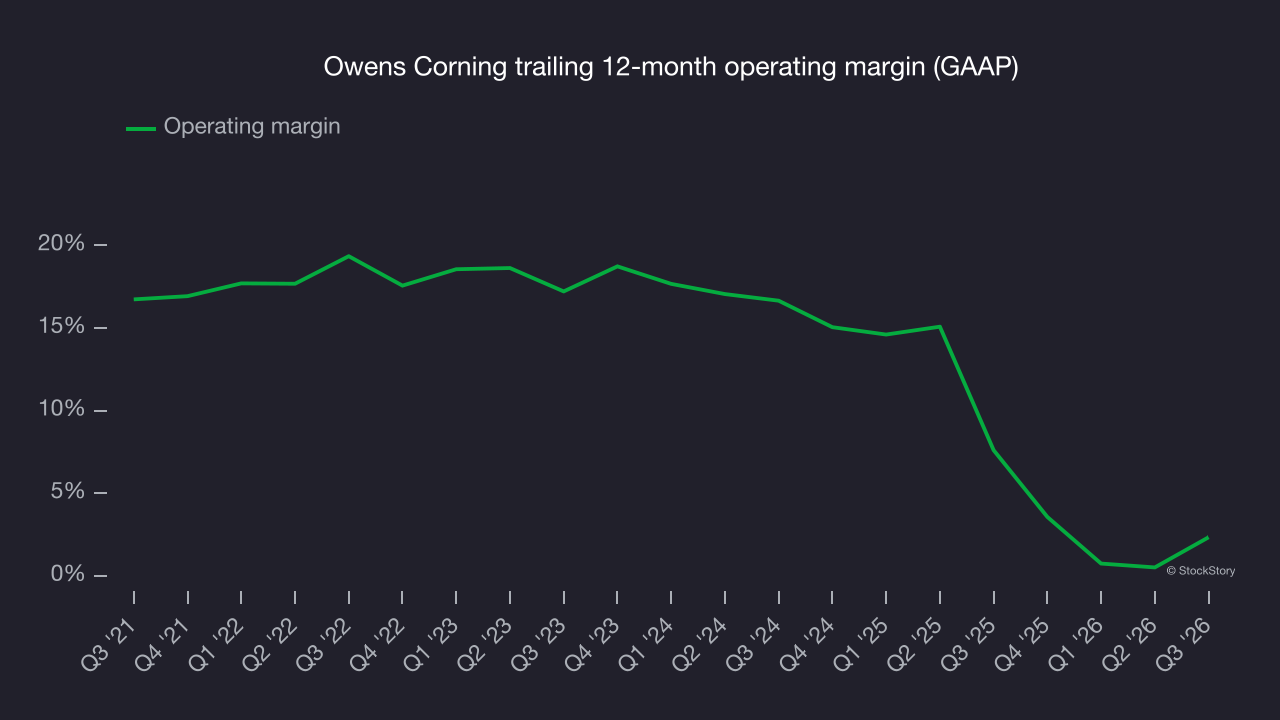
This quarter, Owens Corning generated an operating margin of negative 6.1%, up 6.1 percentage points year on year. The increase was solid and, with revenue and gross margin declining, suggests improved efficiency from cuts to operating expenses such as marketing, administrative overhead and research and development.
Earnings per share
Revenue trends explain a company’s historical growth, but the long-term change in earnings per share, or EPS, points to the profitability of that growth. For example, a company could inflate its revenue through excessive spending on advertising and promotions.
Owens Corning’s flat EPS over the last five years was below its 3.1% annualized revenue growth. This indicates the company became less profitable on a per-share basis as it expanded due to non-fundamental factors such as interest expenses and taxes.
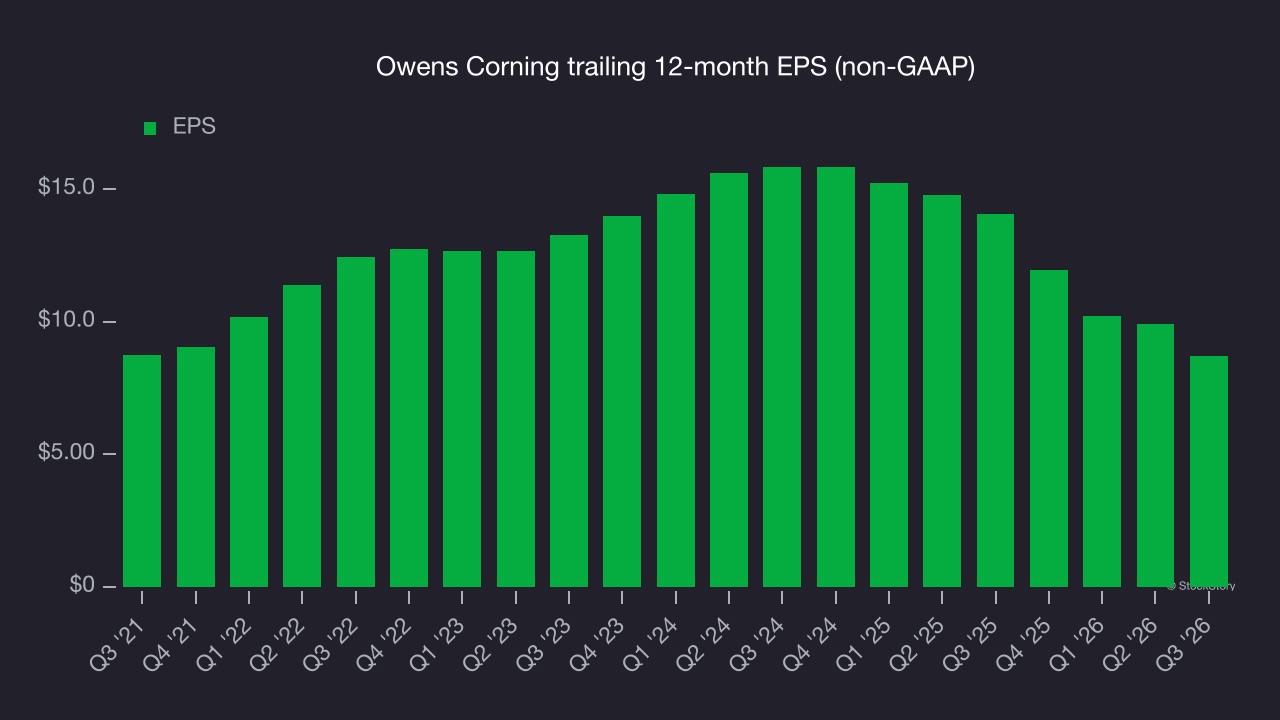
A closer look at Owens Corning’s earnings helps explain the drivers of its performance. As mentioned earlier, Owens Corning’s operating margin expanded this quarter but declined by 17 percentage points over the last five years. This was the most relevant factor (aside from the revenue impact) behind its lower earnings; interest expenses and taxes can also affect EPS but don’t tell us as much about a company’s fundamentals.
As with revenue, we analyze EPS over a more recent period because it can provide insight into an emerging theme or development for the business.
For Owens Corning, its two-year annual EPS declines of 25.9% show its recent history drove its underperformance over the last five years. The results were poor across both periods.
In Q3, Owens Corning reported adjusted EPS of $2.44, down from $3.67 in the same quarter last year. This result missed analysts’ consensus estimates. Over the next 12 months, Wall Street expects Owens Corning’s full-year EPS to grow 20.5% from $8.69 to $10.47, according to S&P.
Key takeaways from Owens Corning’s Q3 results
Owens Corning’s Q3 left little to like: revenue fell short of Wall Street’s consensus estimates, and its revenue guidance for next quarter also missed expectations. It was a weaker quarter overall. Shares fell 3.5% to $113.87 immediately after the report.
Owens Corning’s latest quarter was underwhelming. One earnings report doesn’t define a company’s quality, though, so assessing the stock at its current price requires a broader view. If you’re making that decision, consider valuation, business quality and the latest earnings. For more on those factors, read our full research report here (it’s free).