Financial technology company NCR Atleos (NYSE: NATL) missed Wall Street’s revenue expectations in Q3 2026, with revenue falling 2% year on year to $1.1 billion. Its non-GAAP profit of $1.35 per share was 13.9% above analysts’ consensus estimates.
For more on NCR Atleos, read our full research report for free.
NCR Atleos (NATL) Q3 2026 highlights:
- Revenue $1.1 billion vs S&P analysts’ consensus estimates of $1.14 billion (2% year-on-year decline, 3.3% miss)
- Pre-tax profit $129 million (11.7% margin)
- Adjusted EPS $1.35 vs S&P analysts’ consensus estimates of $1.19 (13.9% beat)
- Market capitalization $3.45 billion
Andy Wamser, Chief Financial Officer, added, “As we close out the third quarter, our results continue to reflect disciplined execution against our internal plan. We have been able to deliver strong financial results with year-over-year Adjusted EBITDA and EPS growth of 10% and 24%, respectively. Our strong financial performance to date has driven higher free cash flow with no borrowings on our revolving credit facility and further reduction in net leverage. We remain focused on delivering stronger earnings and cash flow conversion as we close out the year, enabling further net leverage reduction ahead of the anticipated transaction.”
Revenue growth
A company’s long-term performance is an indicator of its overall quality. Any business can experience short-term success, but top-performing ones enjoy sustained growth for years. NCR Atleos’s revenue grew at a weak 1.4% annualized rate over the last four years, falling short of our standards.
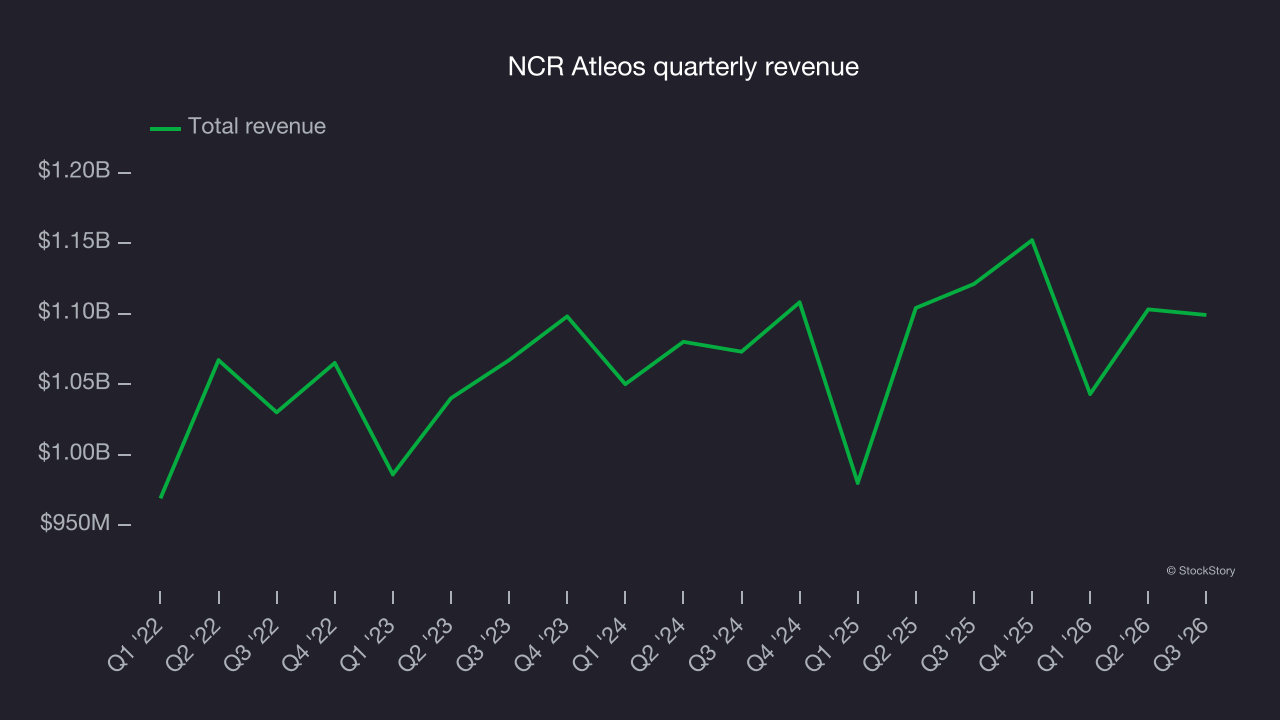
Long-term growth is the most important, but within financials, a stretched historical view may miss recent interest rate changes and market returns. NCR Atleos’s annualized revenue growth of 1.1% over the last two years aligns with its four-year trend, suggesting its demand was consistently weak. 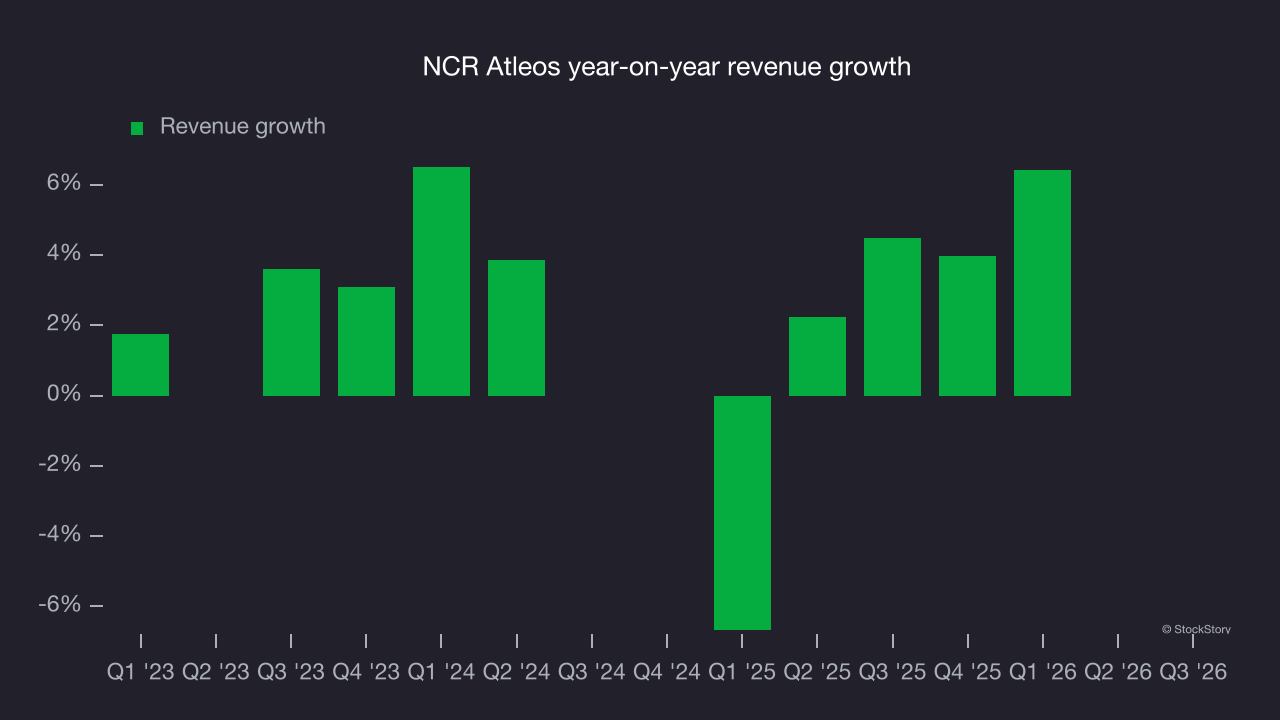 Note: Quarters not shown were determined to be outliers because they were impacted by outsized investment gains/losses that are not indicative of the recurring fundamentals of the business.
This quarter, NCR Atleos missed Wall Street’s consensus estimates and reported an uninspiring 2% year-on-year revenue decline, generating $1.1 billion in revenue.
Key takeaways from NCR Atleos’s Q3 results
NCR Atleos’s Q3 results were mixed: EBITDA beat analysts’ consensus estimates by a wide margin and EPS also topped Wall Street’s consensus, but revenue missed expectations. Shares remained flat at $46.64 immediately after the release.
When evaluating NCR Atleos at its current price, consider the bigger picture of valuation, business quality and the latest earnings. Read the full research report here (it’s free).