Vacation ownership company Marriott Vacations (NYSE: VAC) fell short of the market’s revenue expectations in Q3 2026, but revenue rose 8.2% year on year to $1.37 billion. Its non-GAAP profit of $2.64 per share was 2% above analysts’ consensus estimates.
For more on Marriott Vacations, read our full research report for free.
Marriott Vacations (VAC) Q3 2026 highlights:
- Revenue $1.37 billion vs S&P analysts’ consensus estimates of $1.41 billion (8.2% year-on-year growth, 3.1% miss)
- Adjusted EPS $2.64 vs S&P analysts’ consensus estimates of $2.59 (2% beat)
- Adjusted EBITDA $216 million vs analysts’ consensus estimates of $216 million (15.8% margin, in line)
- Adjusted EPS guidance Management raised its full-year adjusted EPS guidance to $8.90 at the midpoint, a 2.9% increase
- EBITDA guidance $820 million at the midpoint for the full year, in line with analysts’ consensus estimates
- Guests fell 19,208 year on year
- Market capitalization $4.08 billion
“We are very pleased with our third quarter financial results, as they demonstrate the substantive momentum in our business, on the heels of our strong second quarter. Further, they reflect the continued success of the strategies we began implementing in the second quarter as part of the transformation now underway. By way of example, VPG increased to an industry leading $4,822, 30% above last year, and our operating discipline drove 27% Adjusted EBITDA growth,” said Matt Avril, Chief Executive Officer. “Our emphasis on differentiating Owner experiences such as our Inner Circle by Aflac events platform - which features curated regional and national entertainment - are fueling our sales success.”
Revenue growth
A company’s long-term revenue performance can indicate its overall quality. Even a bad business can perform well for one or two quarters, but a top-tier one grows for years. Marriott Vacations’s revenue grew at a weak 8.3% annualized rate over the last five years, falling short of the consumer discretionary sector benchmark.
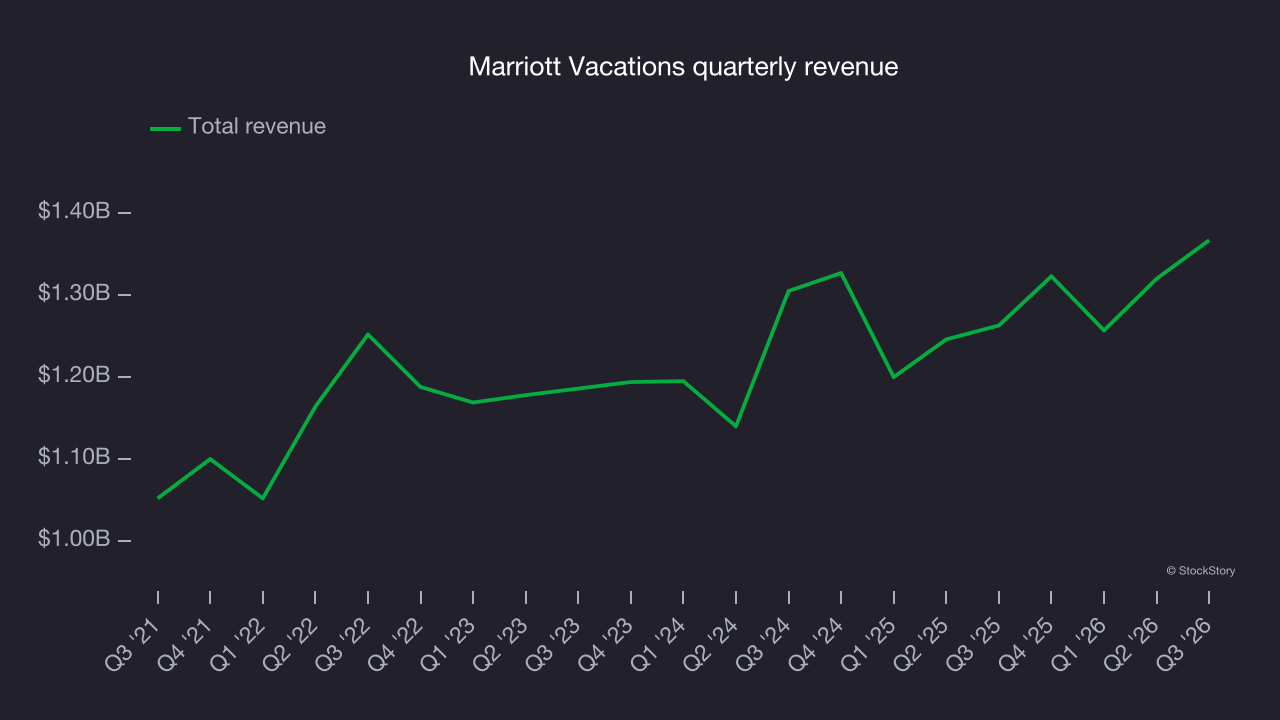
Long-term growth matters most, but within consumer discretionary, a stretched historical view may miss a company riding a successful new property or trend. Marriott Vacations’s recent performance shows its demand has slowed as its annualized revenue growth of 4.4% over the last two years was below its five-year trend. Decelerating revenue growth in the sector warrants caution, as it could signal changing consumer tastes aided by low switching costs. 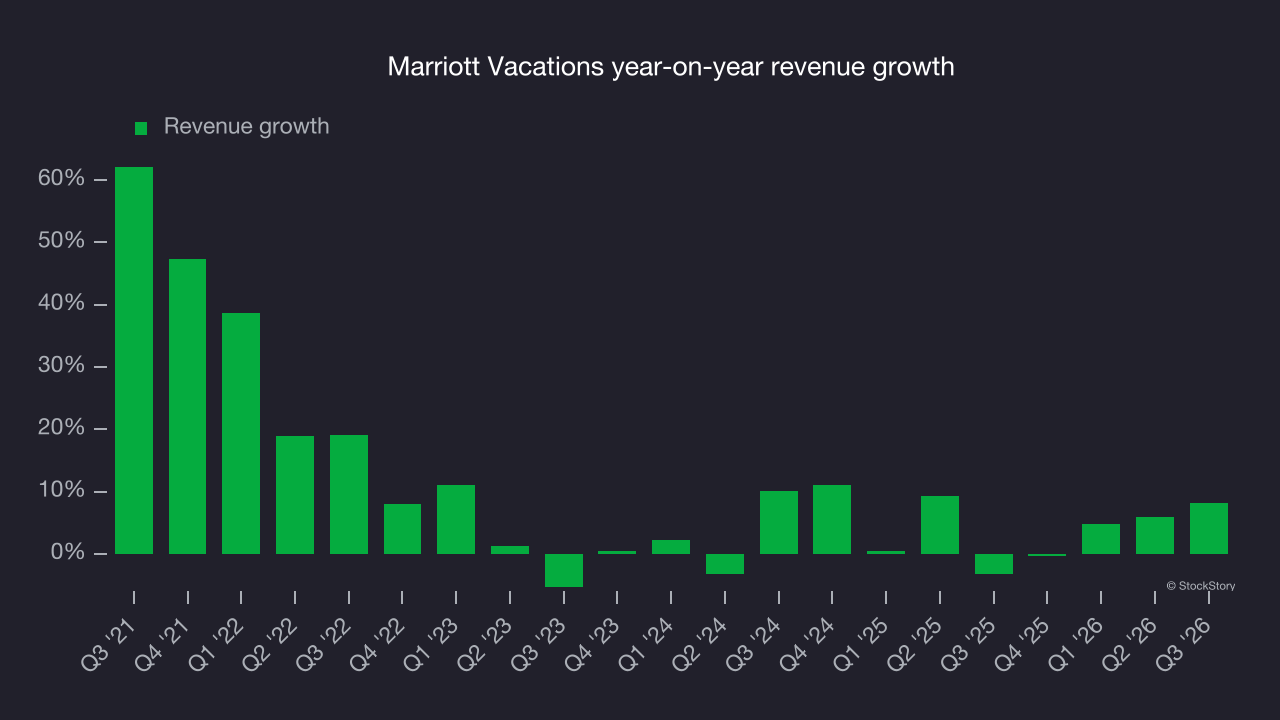
This quarter, Marriott Vacations’s revenue grew by 8.2% year on year to $1.37 billion, missing Wall Street’s consensus estimates.
Looking ahead, sell-side analysts expect revenue to grow 6.4% over the next 12 months, according to S&P. While this projection implies its newer products and services will fuel better top-line performance, it is still below average for the sector.
Operating margin
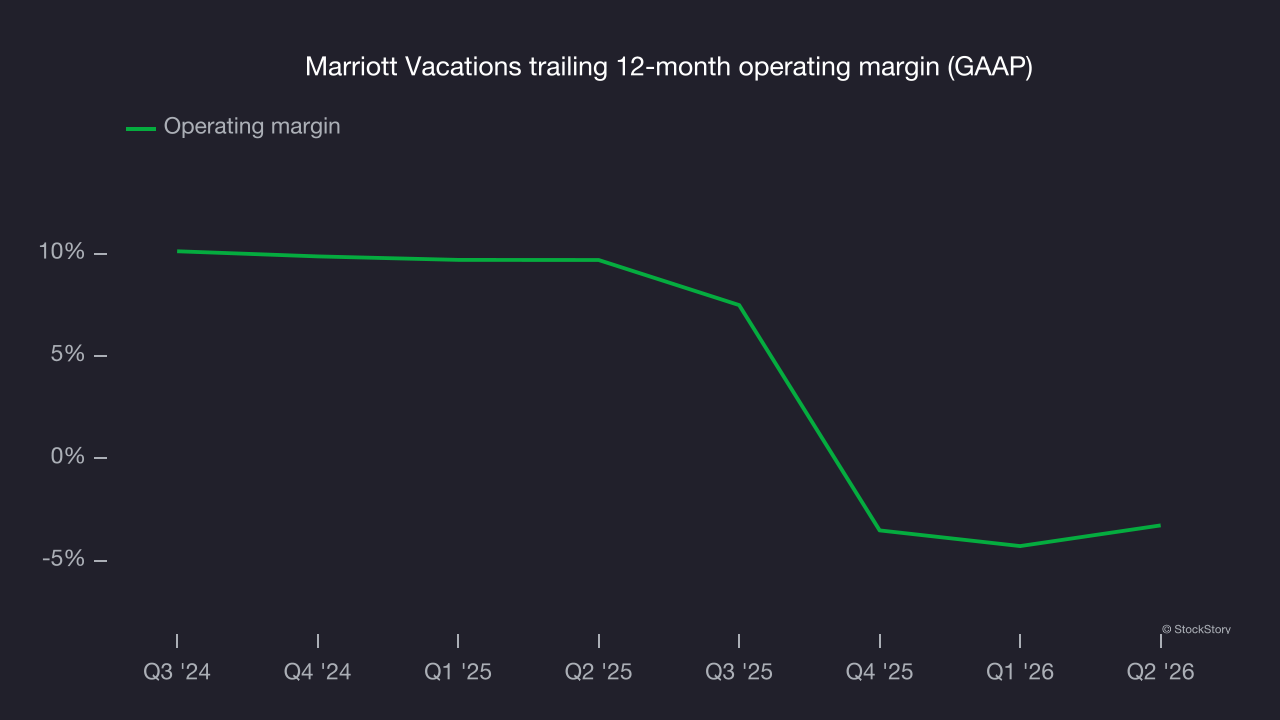
in line with the same quarter last year. This indicates the company’s overall cost structure has been relatively stable.
Earnings per share
Revenue trends explain a company’s historical growth, but the long-term change in earnings per share (EPS) points to the profitability of that growth. For example, a company could inflate its revenue through excessive spending on advertising and promotions.
Marriott Vacations’s EPS grew at a 33.3% compounded annual growth rate over the last five years, higher than its 8.3% annualized revenue growth. However, this alone doesn’t tell us much about its business quality because its operating margin didn’t improve.
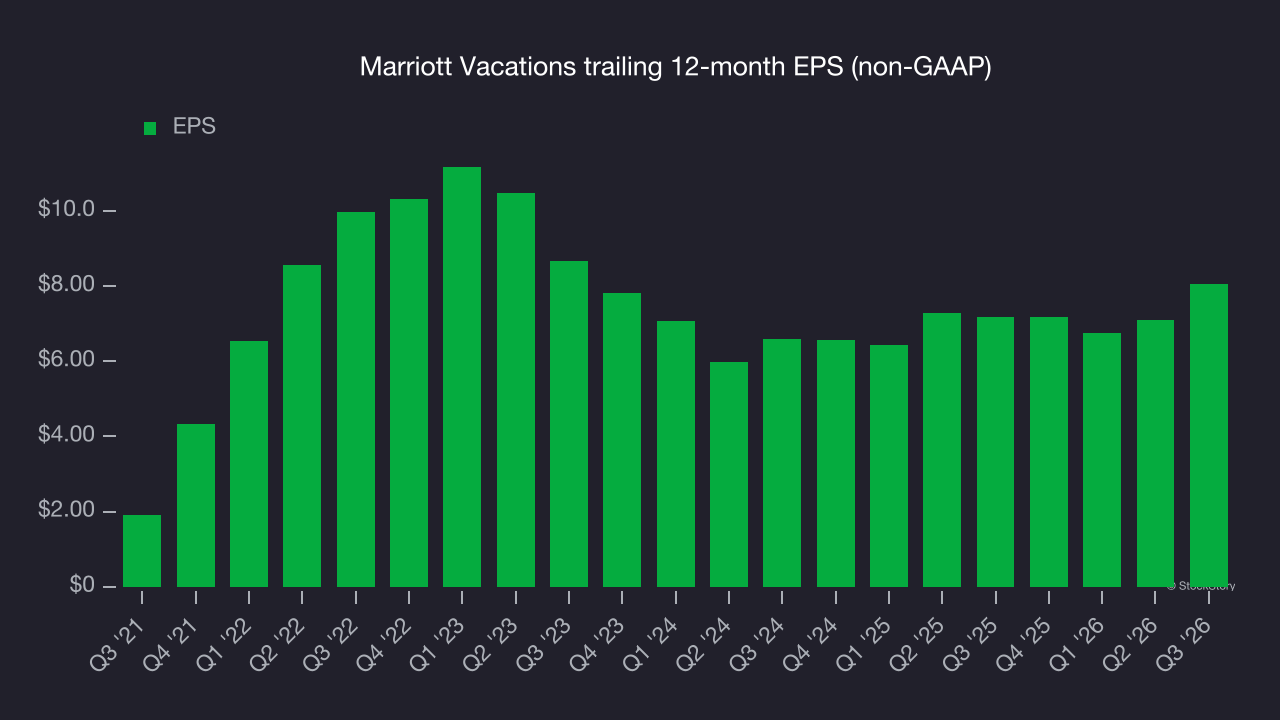
In Q3, Marriott Vacations reported adjusted EPS of $2.64, up from $1.69 in the same quarter last year. This result beat analysts’ consensus estimates by 2%. Over the next 12 months, Wall Street expects Marriott Vacations’s full-year EPS to grow 20.2% from $8.05 to $9.68, according to S&P.
Key takeaways from Marriott Vacations’s Q3 results
There was little to highlight on the positive side of Marriott Vacations’ weaker quarter. Shares remained flat at $118.59 immediately after the release.
Deciding whether to buy the stock means considering the bigger picture of valuation, business quality and the latest earnings. For more, read our full research report here (it’s free).