Insurance and technology company HCI Group (NYSE: HCI) fell short of the market’s revenue expectations in Q3 2026, but revenue rose 13.2% year on year to $244.9 million. Its GAAP profit of $6.45 per share was 58.9% above analysts’ consensus estimates.
For more on HCI Group, read our free full research report.
HCI Group (HCI) Q3 2026 highlights:
- Net premiums earned $219.1 million vs analysts’ consensus estimates of $227.6 million (12.4% year-on-year growth, 3.7% miss)
- Revenue $244.9 million vs analysts’ consensus estimates of $251.7 million, according to S&P (13.2% year-on-year growth, 2.7% miss)
- Pre-tax profit $116.3 million (47.5% margin)
- EPS (GAAP) $6.45 vs analysts’ consensus estimates of $4.06 (58.9% beat)
- Book value per share $90.15 vs analysts’ consensus estimates of $89.97 (42.2% year-on-year growth, in line)
- Market capitalization $2.51 billion
Revenue growth
Insurance companies generate revenue three ways. The first is the core insurance business itself, represented in the income statement as premiums earned. The second source is investment income from investing the “float” (premiums collected but not yet paid out as claims) in assets such as fixed-income assets and equities. The third is fees from policy administration, annuities and other value-added services. HCI Group’s revenue grew at a strong 21.8% compounded annual growth rate over the last five years. Its growth surpassed the average insurance company and shows its offerings resonate with customers.
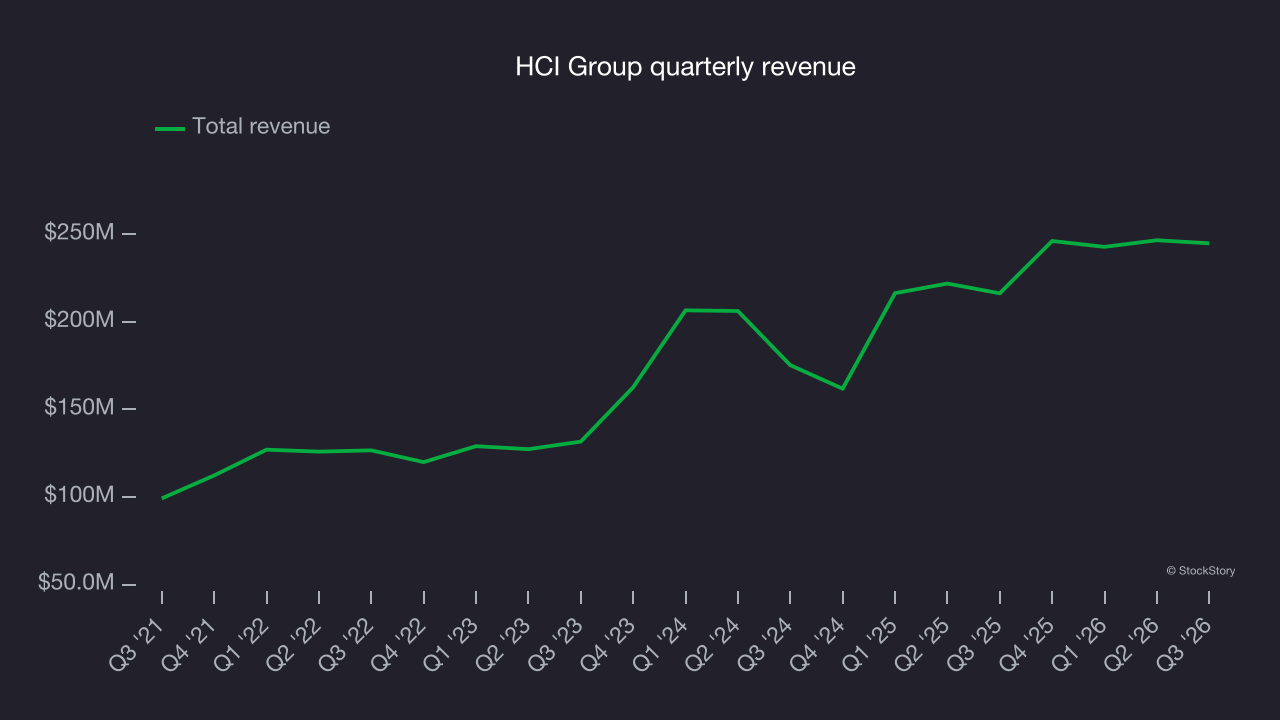
Long-term growth matters most, but within financials, a half-decade historical view may miss recent interest rate changes, market returns and industry trends. HCI Group’s annualized revenue growth of 14.3% over the last two years is below its five-year trend, but the results still suggest healthy demand. 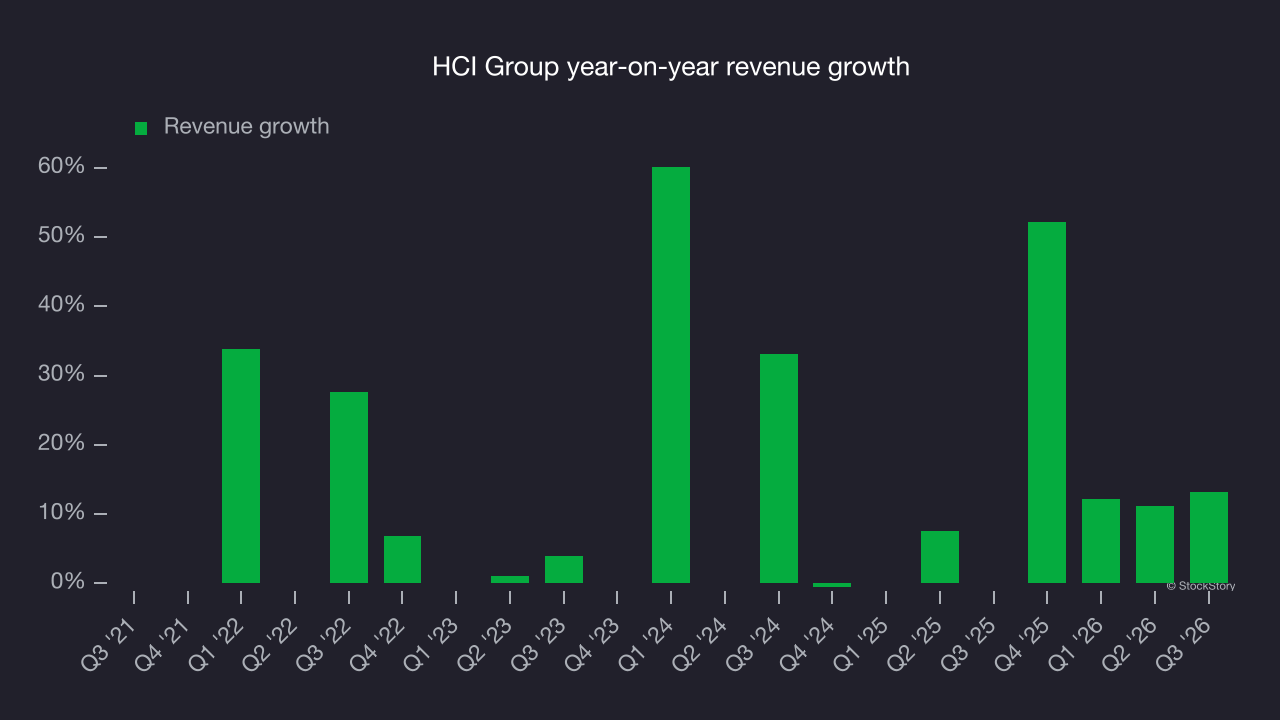 Note: Quarters not shown were determined to be outliers because they were impacted by outsized investment gains/losses that are not indicative of the recurring fundamentals of the business.
This quarter, HCI Group’s revenue grew by 13.2% year on year to $244.9 million but fell short of Wall Street’s consensus estimates.
Net premiums earned made up 90.8% of the company’s total revenue during the last five years, meaning HCI Group depends heavily on its underwriting activities because non-insurance operations contribute little to revenue.
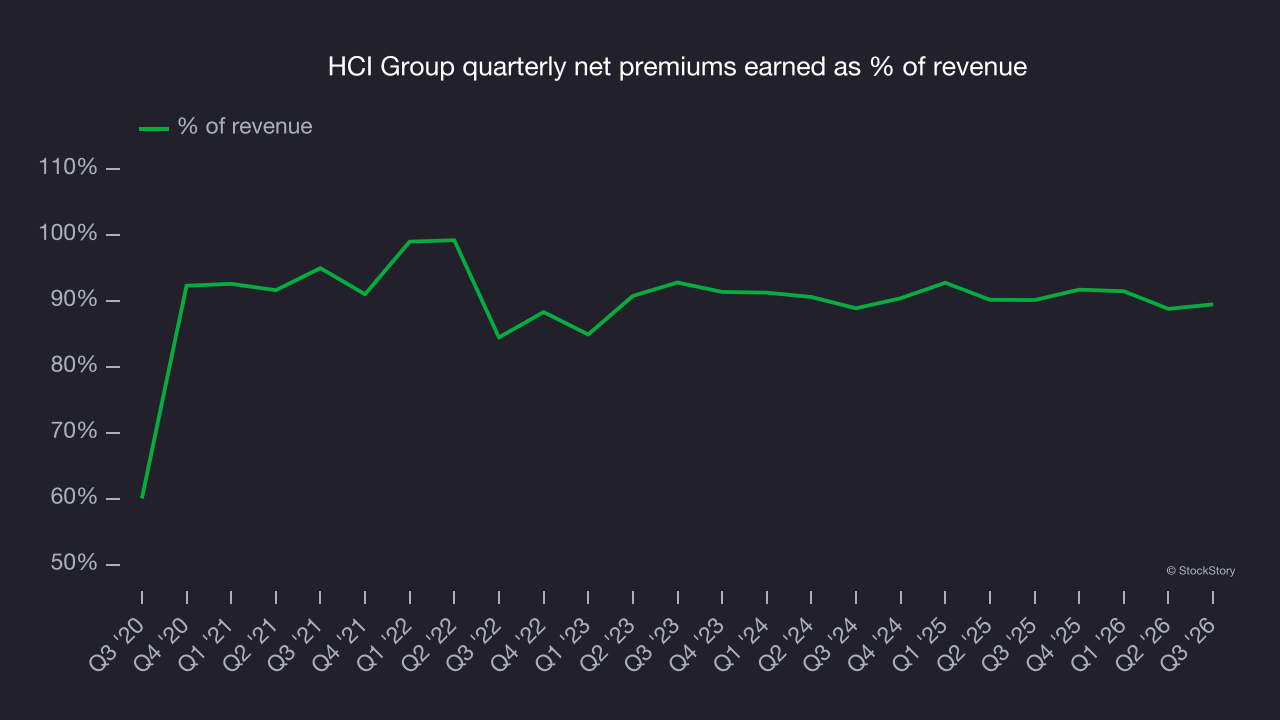
Markets consistently prioritize net premiums earned growth over investment and fee income, recognizing its superior quality as a core indicator of the company’s underwriting success and market penetration.
Book value per share (BVPS)
Insurers are balance sheet businesses, collecting premiums upfront and paying out claims over time. Premiums collected but not yet paid out, often referred to as the float, are invested and create an asset base supported by a liability structure. Book value per share, or BVPS, captures this dynamic by measuring these assets (investment portfolio, cash and reinsurance recoverables) less liabilities (claim reserves, debt and future policy benefits). BVPS is essentially the residual value for shareholders.
BVPS is therefore an important metric to track for insurers and sheds light on business quality because it reflects long-term capital growth and is harder to manipulate than more commonly used metrics like EPS.
HCI Group’s BVPS grew at a strong 24.3% annual rate over the last five years. BVPS growth has also accelerated recently, growing by 44% annually over the last two years from $43.45 to $90.15 per share.
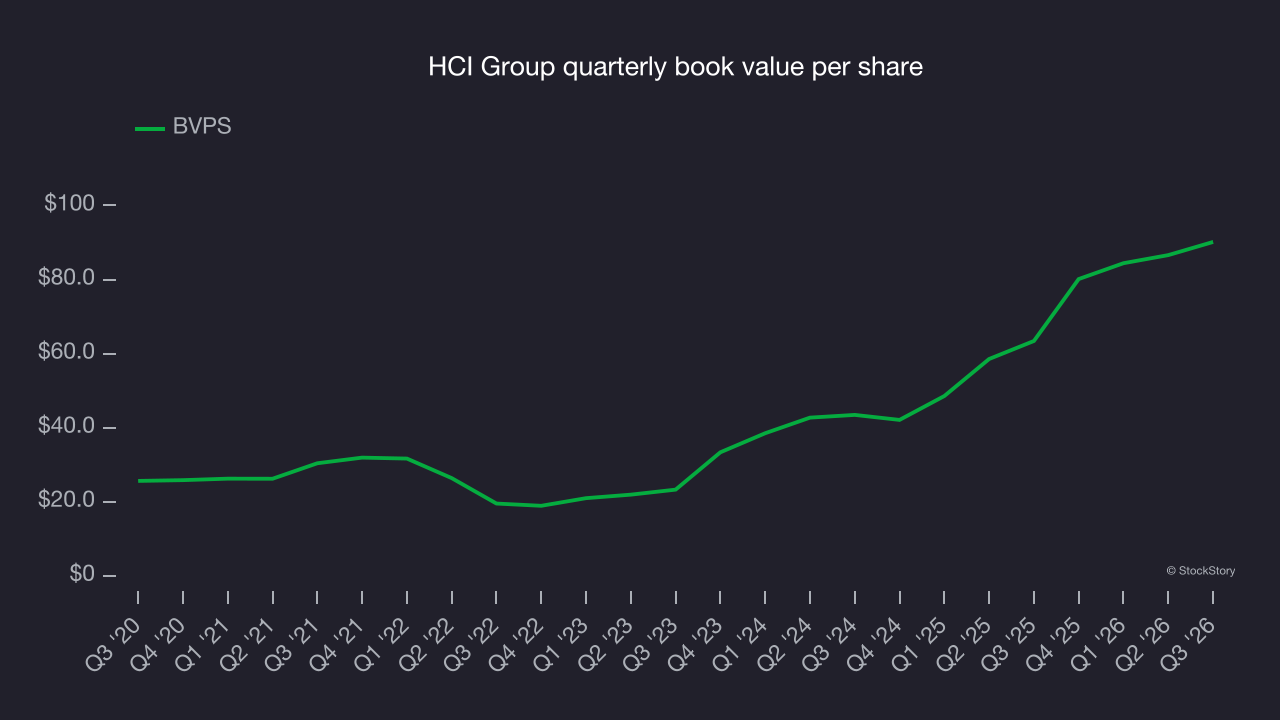
Over the next 12 months, consensus estimates call for HCI Group’s BVPS to grow by 8.9% to $89.97, a mediocre growth rate.
Key takeaways from HCI Group’s Q3 results
HCI Group’s Q3 results were mixed: EPS beat analysts’ consensus estimates, but net premiums earned missed expectations and revenue fell short of Wall Street’s consensus. The earnings beat was a key positive in an otherwise uneven quarter. Shares remained flat at $202 immediately after the results.
Evaluating an investment in HCI Group means considering its valuation, business quality and latest quarterly results. Read the full research report here (it’s free).