Wells Fargo trades at $85.27 per share and has stayed right on track with the overall market, gaining 7.7% over the last six months. At the same time, the S&P 500 has returned 4.7%.
Is now the time to buy Wells Fargo, or should you be careful about including it in your portfolio? Dive into our full research report to see our analyst team’s opinion, it’s free.
Why do we think Wells Fargo will underperform?
We’re cautious about Wells Fargo. Here are three reasons we avoid WFC, plus one stock we’d rather own.
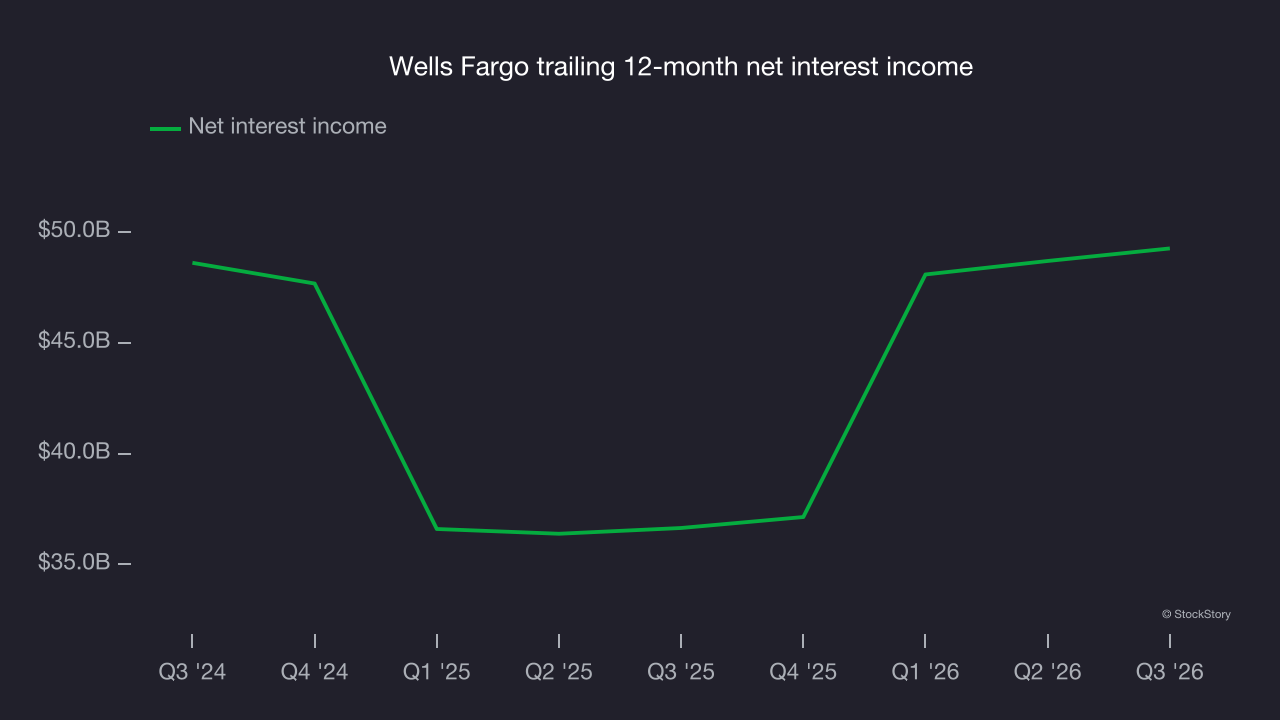
1. Net interest income points to soft demand
While banks generate revenue from multiple sources, investors view net interest income as a cornerstone — its predictable, recurring characteristics stand in sharp contrast to the volatility of one-time fees.
Wells Fargo’s net interest income has grown at a 6.5% annualized rate over the last five years, worse than the broader banking industry.
2. Low net interest margin reveals weak loan book profitability
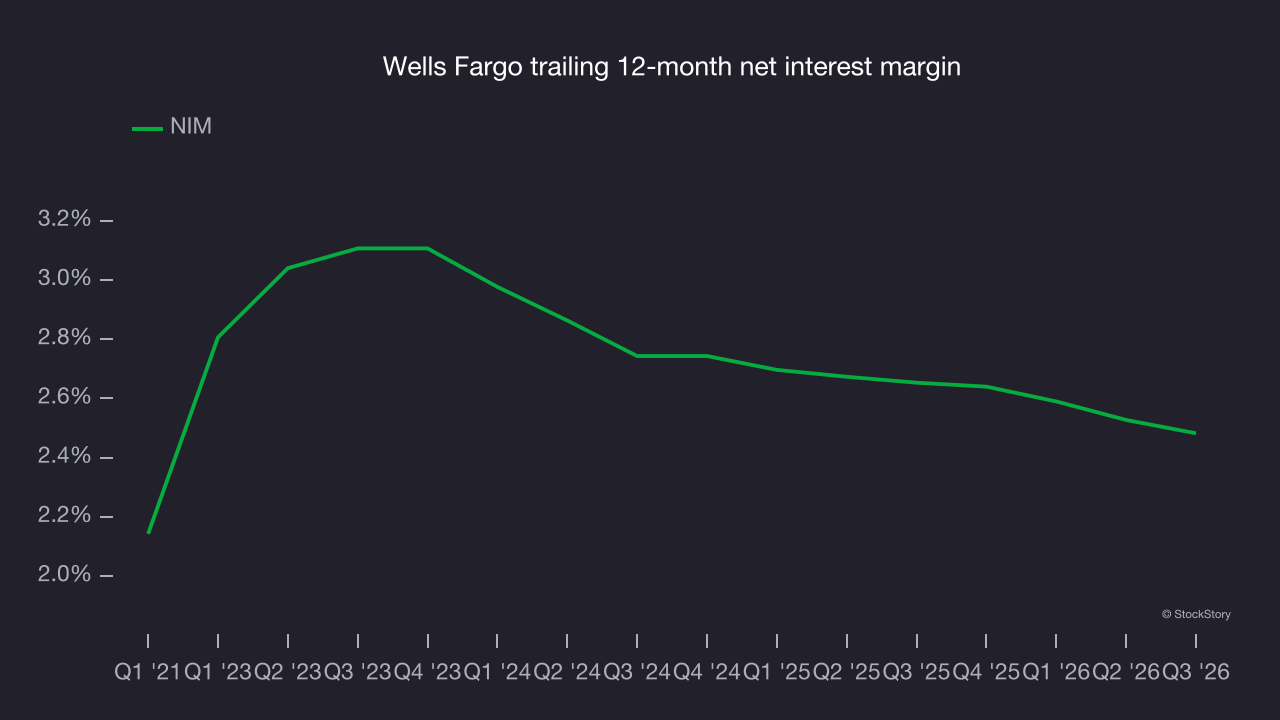
Net interest margin (NIM) represents how much a bank earns in relation to its outstanding loans. It’s one of the most important metrics to track because it shows how a bank’s loans are performing and whether it has the ability to command higher premiums for its services.
Over the past two years, we can see that Wells Fargo’s net interest margin averaged a poor 2.6%, indicating the company has weak loan book economics.
3. Substandard TBVPS growth indicates limited asset expansion
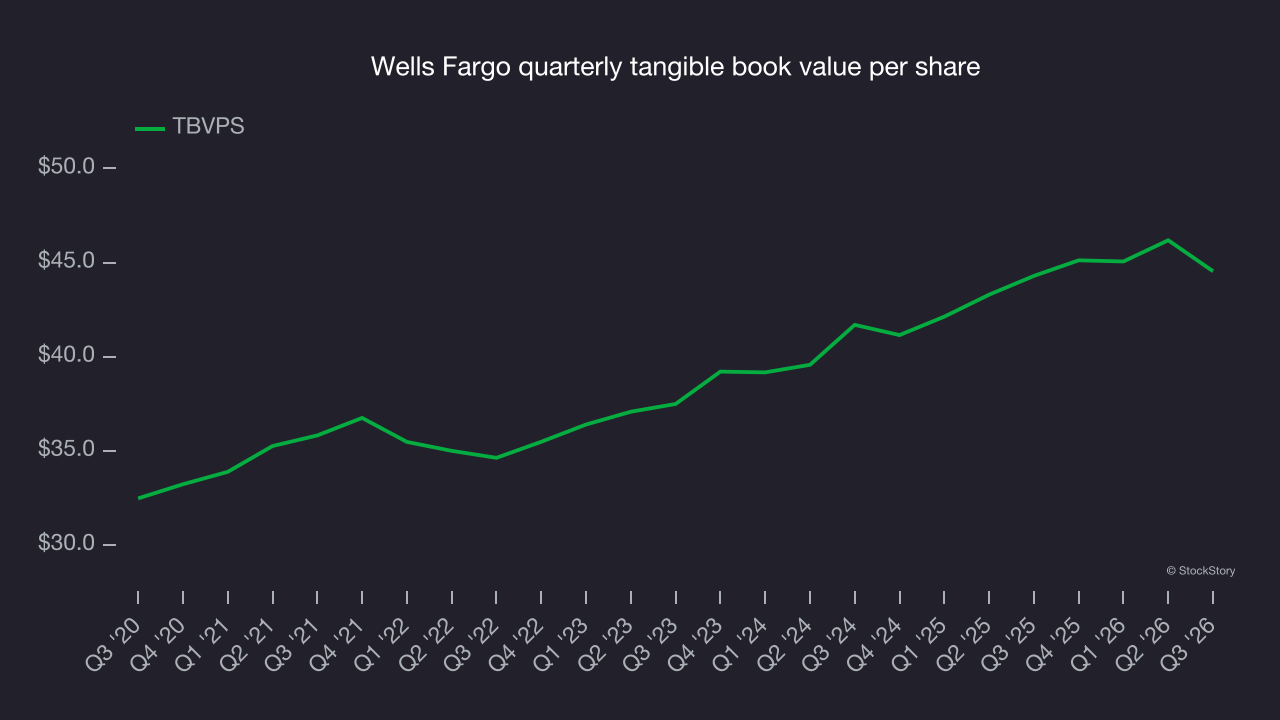
For banks, tangible book value per share (TBVPS) is a crucial metric that measures the actual value of shareholders’ equity, stripping out goodwill and other intangible assets that may not be recoverable in a worst-case scenario.
Wells Fargo’s TBVPS increased by a meager 4.5% annually over the last five years, and its recent performance paints an even worse picture as growth has decelerated a bit to a sluggish 3.4% over the past two years (from $41.69 to $44.54 per share).
Final judgment
We cheer for all companies supporting the economy, but in the case of Wells Fargo, we’ll be cheering from the sidelines. That said, the stock currently trades at 1.6× forward P/B (or $85.27 per share). This multiple tells us a lot of good news is priced in - we think there are better stocks to buy right now. We’d suggest looking at the Amazon and PayPal of Latin America.
Stocks we like more than Wells Fargo
ONE MORE THING: Top 5 Growth Stocks. The biggest stock winners almost always had one thing in common before they ran. Revenue growing like crazy. Meta. CrowdStrike. Broadcom. Our AI flagged all three. They returned 315%, 314%, and 455%, respectively.
Find out which 5 stocks it’s flagging this month — FREE. Get Our Top 5 Growth Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Comfort Systems (+1,154% between June 2020 and June 2025). Find your next big winner with StockStory today.