Online platform company Coupang (NYSE: CPNG) reported Q3 2026 results beating Wall Street’s revenue expectations, with revenue up 7.5% year on year to $9.96 billion. Its non-GAAP loss of $0.18 per share was significantly below analysts’ consensus estimates.
For more on Coupang, read our free full research report.
Coupang (CPNG) Q3 2026 highlights:
- Revenue $9.96 billion vs S&P analysts’ consensus estimates of $9.74 billion (7.5% year-on-year growth, 2.3% beat)
- Adjusted EPS -$0.18 vs S&P analysts’ consensus estimates of -$0.01 (significant miss; -$501 million of net income would have been -$321 million excluding $180 million of tax-affected loss related to the FC fire)
- Adjusted EBITDA $116 million vs analysts’ consensus estimates of $192.1 million (1.2% margin, 39.6% miss)
- Operating margin -4.5%, down from 1.7% in the same quarter last year
- Free cash flow -$72 million, down from $51 million in the previous quarter
- Active customers 25.2 million, up 500,000 year on year
- Market capitalization $26.42 billion
Revenue growth
Examining a company’s long-term performance can provide clues about its quality. Any business can report a good quarter or two, but many enduring ones grow for years. Coupang’s 16% annualized revenue growth over the last three years was solid. Its growth beat the average consumer internet company and shows its offerings resonate with customers.
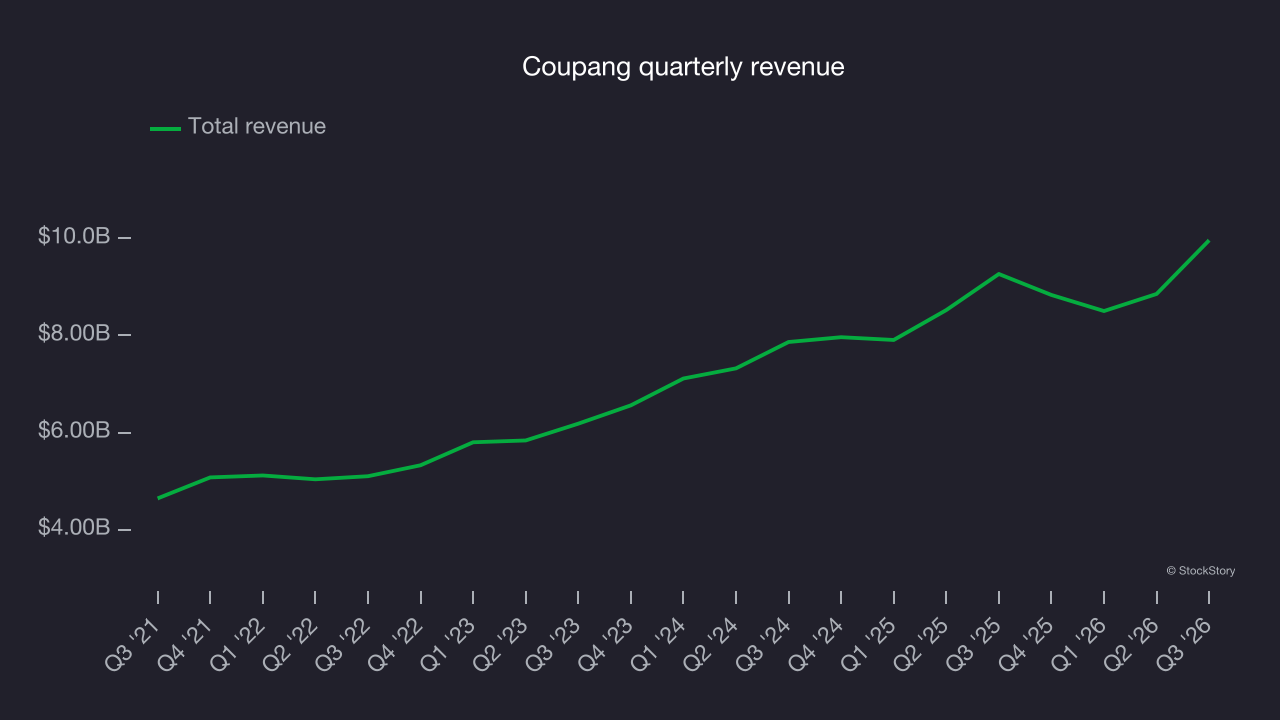
This quarter, Coupang reported year-on-year revenue growth of 7.5%, and its $9.96 billion of revenue exceeded Wall Street’s consensus estimates by 2.3%.
Looking ahead, sell-side analysts expect revenue to grow 12.9% over the next 12 months, according to S&P, a deceleration versus the last three years. Its growth trajectory remains satisfactory given its scale and suggests the market is pricing in success for its products and services.
Active customers
Buyer growth
As an online retailer, Coupang generates revenue growth by expanding its number of users and the average order size in dollars.
Over the last two years, Coupang’s active customers, a key performance metric for the company, increased by 6.6% annually to 25.2 million in the latest quarter. This growth rate is slightly below average for a consumer internet business and is largely a function of its already large scale and high market penetration. To accelerate growth, Coupang likely needs to innovate with new products.
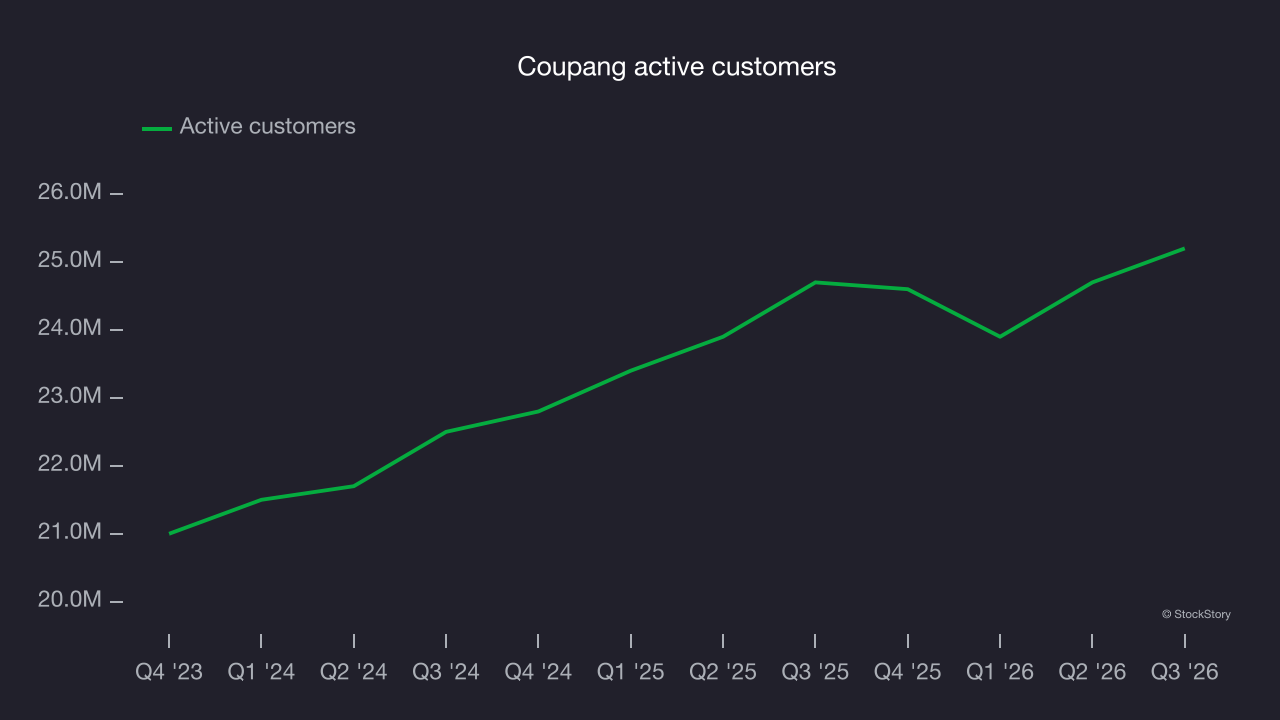
In Q3, Coupang added 500,000 active customers, leading to 2% year-on-year growth. The quarterly print was lower than its two-year result, suggesting its new initiatives aren’t accelerating buyer growth just yet.
Revenue per buyer
Average revenue per buyer, or ARPB, is a critical metric to track because it measures how much customers spend per order.
Coupang’s ARPB growth has been decent over the last two years, averaging 5.1%. Its ability to increase monetization while growing its active customers demonstrates the value of its platform.
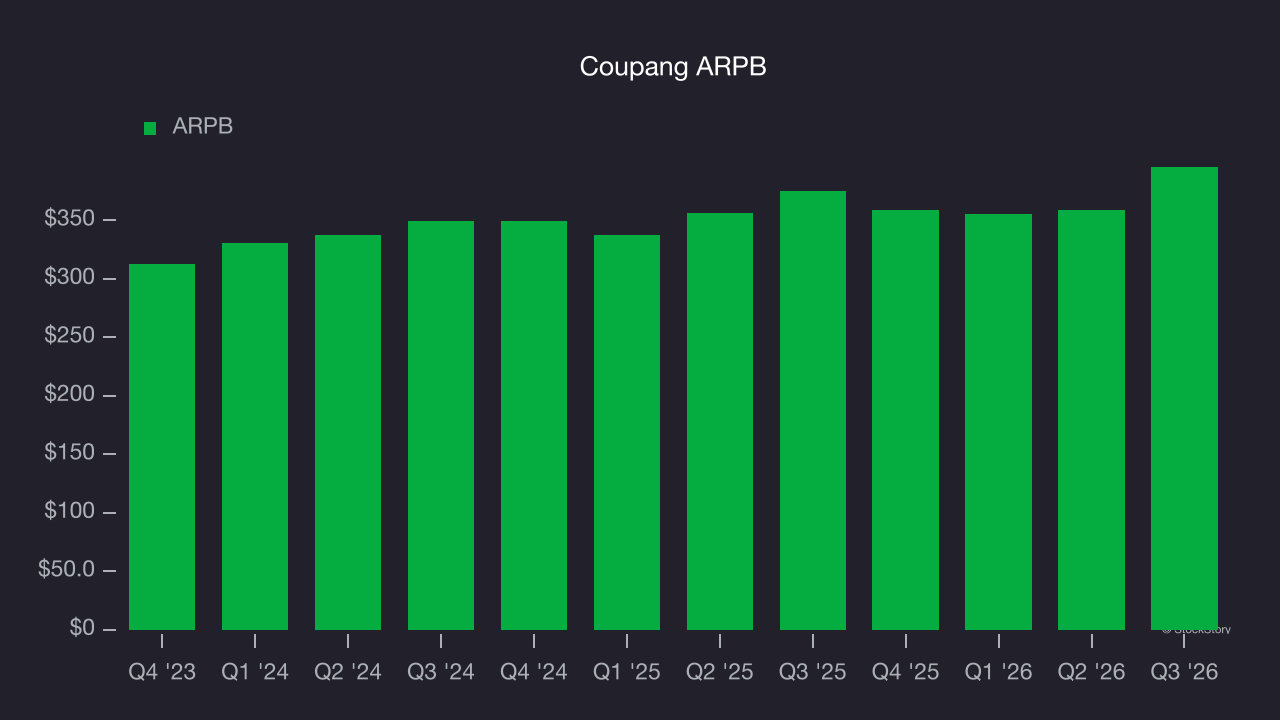
This quarter, Coupang’s ARPB came in at $395.32. It grew by 5.4% year on year, faster than its active customers.
Key takeaways from Coupang’s Q3 results
Coupang’s revenue beat analysts’ consensus estimates in Q3, but an EBITDA miss made for a softer quarter overall. Shares edged higher 1.7% to $15.51 immediately after the results.
When deciding whether to invest in Coupang at its current price, consider its valuation, business quality and what happened in the latest quarter. Read the full research report here (it’s free).