Construction materials company Vulcan Materials (NYSE: VMC) will be announcing earnings results this Thursday before the bell. Here’s what you need to know.
Vulcan Materials beat analysts’ revenue expectations last quarter, reporting revenues of $2.16 billion, up 2.5% year on year. It was a strong quarter for the company, with full-year EBITDA guidance beating analysts’ expectations and a beat of analysts’ EPS estimates. It reported 59.9 million tons shipped, up 1% year on year.
Is Vulcan Materials a buy or sell going into earnings? Read our full analysis here, it’s free for active Edge members.
This quarter, the market is expecting Vulcan Materials’s revenue to decline 2.5% year on year, a reversal from the 14.4% increase it recorded in the same quarter last year.
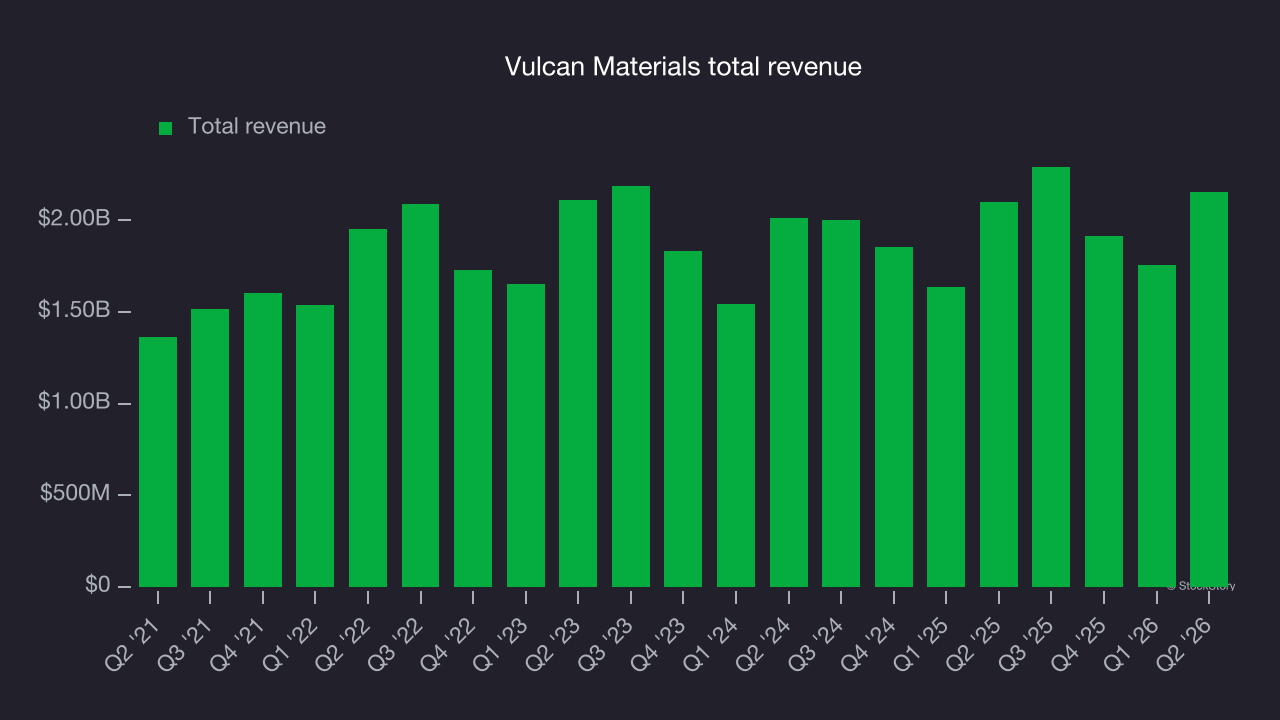
Analysts covering the company have generally reconfirmed their estimates over the last 30 days, suggesting they anticipate the business will stay the course heading into earnings. Vulcan Materials has missed Wall Street’s revenue estimates multiple times over the last two years.
Looking at Vulcan Materials’s peers in the building materials segment, some have already reported their Q3 results, giving us a hint as to what we can expect. Valmont delivered year-on-year revenue growth of 5.5%, missing analysts’ expectations by 1.3%, and Sherwin-Williams reported revenues up 7.9%, topping estimates by 1.3%. Valmont’s stock price was unchanged following the results.
Read our full analysis of Valmont’s results here and Sherwin-Williams’s results here.
In the last twelve months or so, the market has shifted its attention from one area of macro importance to the next (AI disintermediation and AI capex spending to geopolitical conflict, rates, and whether the economy is on solid footing or not). While some of the building materials stocks have shown solid performance in this choppy environment, the group has generally underperformed, with share prices down 2.7% on average over the last month. Vulcan Materials is up 6.6% during the same time and is heading into earnings with an average analyst price target of $307.26 (compared to the current share price of $262.50).
ONE MORE THING: 3 Hidden Platforms Growing 3X Faster than Amazon, Google, and PayPal. Amazon, Google, and Meta all followed the same playbook: Dominate an ignored market. Build an unbeatable moat. Scale until you’re unstoppable.
These three platforms are running that exact playbook right now. The early investors in Amazon made fortunes. The early investors in these could do the same. Get All 3 Stocks Here for FREE.