Health insurance company UnitedHealth (NYSE: UNH) reported Q3 2026 results beating Wall Street’s revenue expectations, but sales were flat year on year at $112.7 billion. Its non-GAAP profit of $4.69 per share was 13.3% above analysts’ consensus estimates.
Is now the time to buy UnitedHealth? Find out by accessing our full research report, it’s free.
UnitedHealth (UNH) Q3 2026 Highlights:
- Revenue: $112.7 billion vs analyst estimates of $111.4 billion (flat year on year, 1.2% beat)
- Adjusted EPS: $4.69 vs analyst estimates of $4.14 (13.3% beat)
- Adjusted EPS guidance for the full year is $20.50 at the midpoint, beating analyst estimates by 3.2%
- Operating Margin: 5.8%, up from 3.8% in the same quarter last year
- Market Capitalization: $339.8 billion
“Our third quarter results reflect the discipline and execution our teams are bringing to every part of our business, as we continue evolving UnitedHealth Group to deliver a simpler, more supportive experience for patients and the clinicians who care for them,” said Stephen Hemsley, chief executive officer of UnitedHealth Group.
Company Overview
With over 100 million people served across its various businesses and a workforce of more than 400,000, UnitedHealth Group (NYSE: UNH) operates a health insurance business and Optum, a healthcare services division that provides everything from pharmacy benefits to primary care.
Revenue Growth
A company’s long-term sales performance can indicate its overall quality. Any business can put up a good quarter or two, but the best consistently grow over the long haul. Thankfully, UnitedHealth’s 10% annualized revenue growth over the last five years was decent. Its growth was slightly above the average healthcare company and shows its offerings resonate with customers.
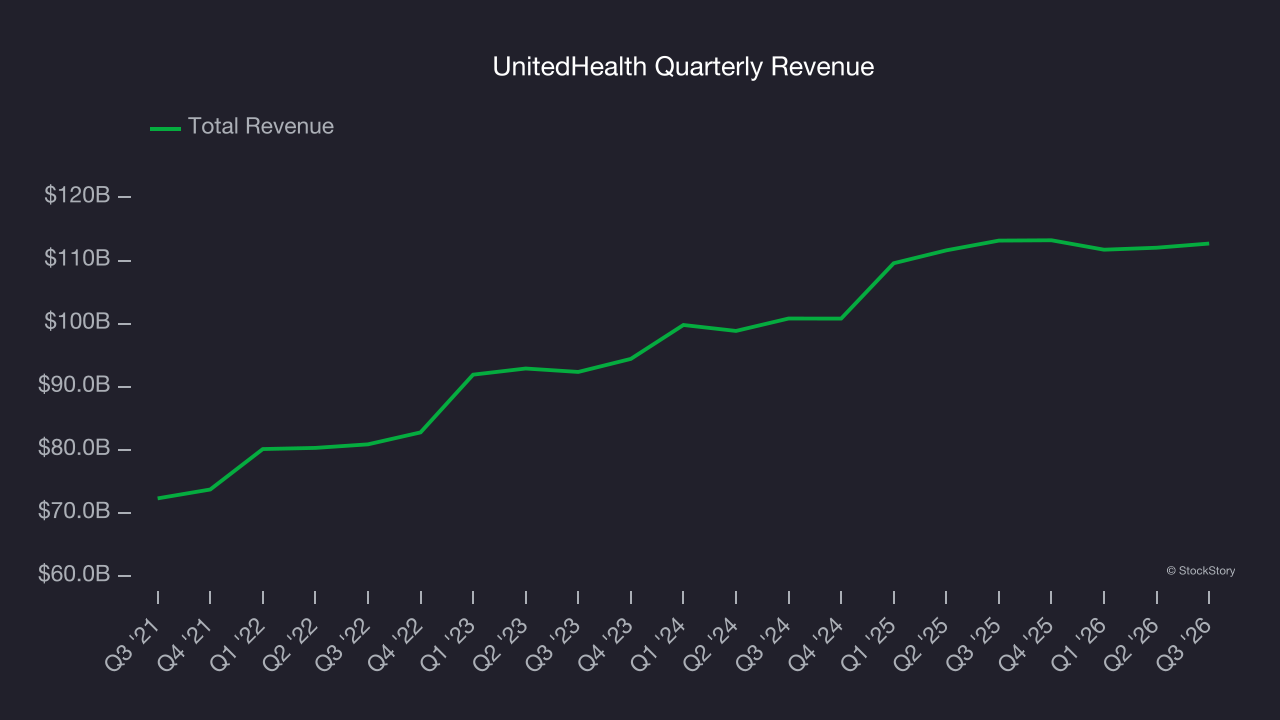
We at StockStory place the most emphasis on long-term growth, but within healthcare, a half-decade historical view may miss recent innovations or disruptive industry trends. UnitedHealth’s recent performance shows its demand has slowed as its annualized revenue growth of 6.8% over the last two years was below its five-year trend. We’re wary when companies in the sector see decelerations in revenue growth, as it could signal changing consumer tastes aided by low switching costs. 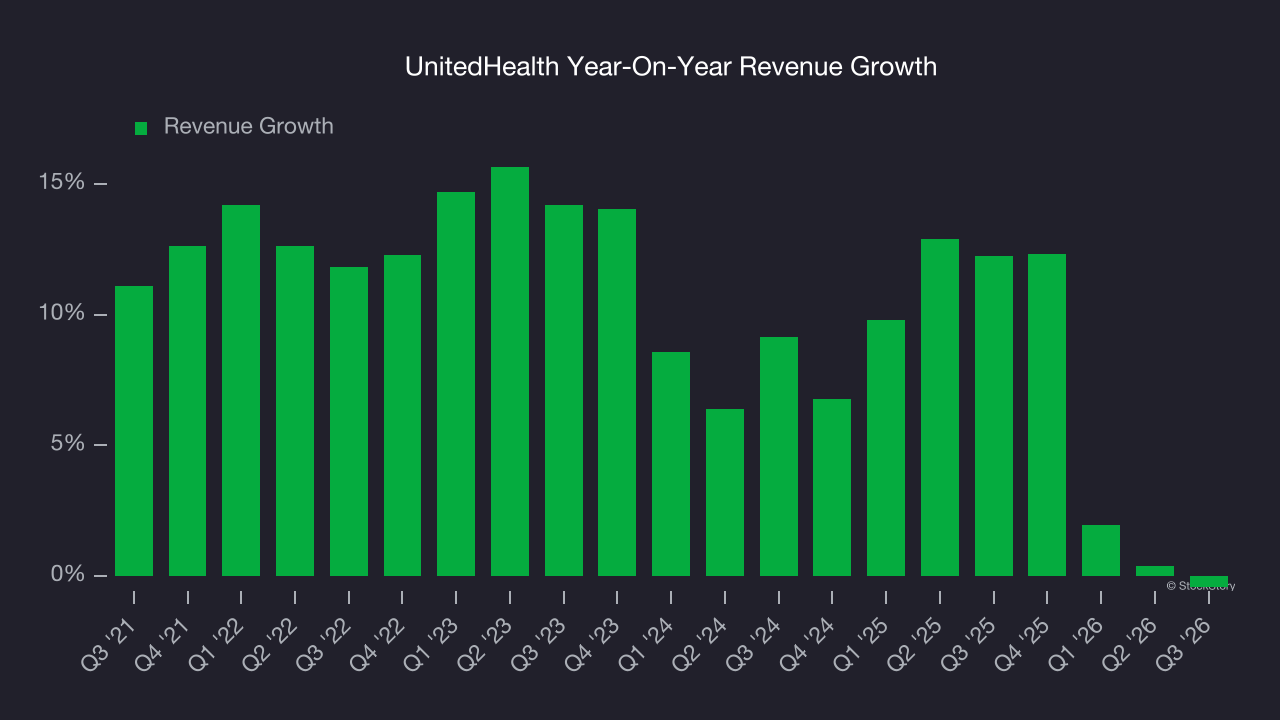
This quarter, UnitedHealth’s $112.7 billion of revenue was flat year on year but beat Wall Street’s estimates by 1.2%.
Looking ahead, sell-side analysts expect revenue to remain flat over the next 12 months, a deceleration versus the last two years. This projection is underwhelming and implies its products and services will face some demand challenges. At least the company is tracking well in other measures of financial health.
ONE MORE THING: 3 Hidden Platforms Growing 3X Faster than Amazon, Google, and PayPal. Amazon, Google, and Meta all followed the same playbook: Dominate an ignored market. Build an unbeatable moat. Scale until you’re unstoppable.
These three platforms are running that exact playbook right now. The early investors in Amazon made fortunes. The early investors in these could do the same. Get All 3 Stocks Here for FREE.
Adjusted Operating Margin
UnitedHealth was profitable over the last five years but held back by its large cost base. Its average adjusted operating margin of 7.5% was weak for a healthcare business.
Analyzing the trend in its profitability, UnitedHealth’s adjusted operating margin decreased by 2.7 percentage points over the last five years. The company’s two-year trajectory also shows it failed to get its profitability back to the peak as its margin fell by 2.7 percentage points. We still like UnitedHealth but would like to see some improvement in the future.
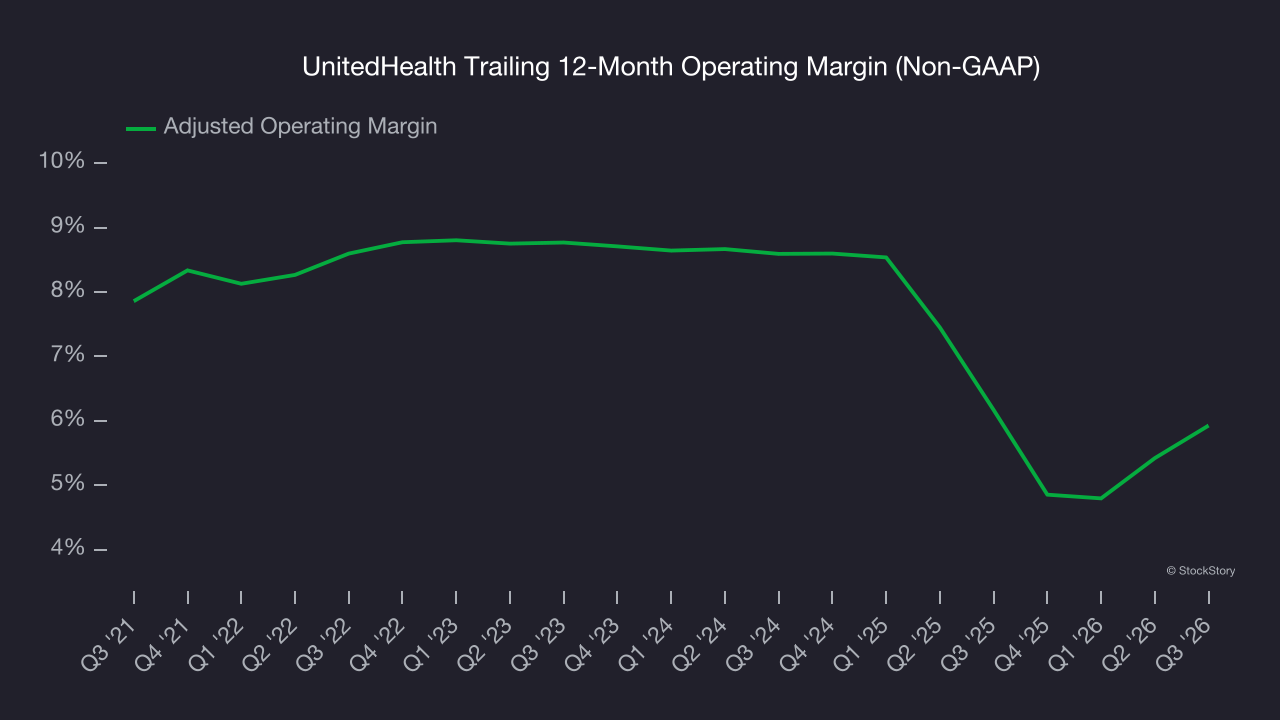
In Q3, UnitedHealth generated an adjusted operating margin profit margin of 5.8%, up 2 percentage points year on year. This increase was a welcome development and shows it was more efficient.
Earnings Per Share
Revenue trends explain a company’s historical growth, but the long-term change in earnings per share (EPS) points to the profitability of that growth — for example, a company could inflate its sales through excessive spending on advertising and promotions.
UnitedHealth’s EPS grew at an unimpressive 3.7% compounded annual growth rate over the last five years, lower than its 10% annualized revenue growth. This tells us the company became less profitable on a per-share basis as it expanded due to non-fundamental factors such as interest expenses and taxes.
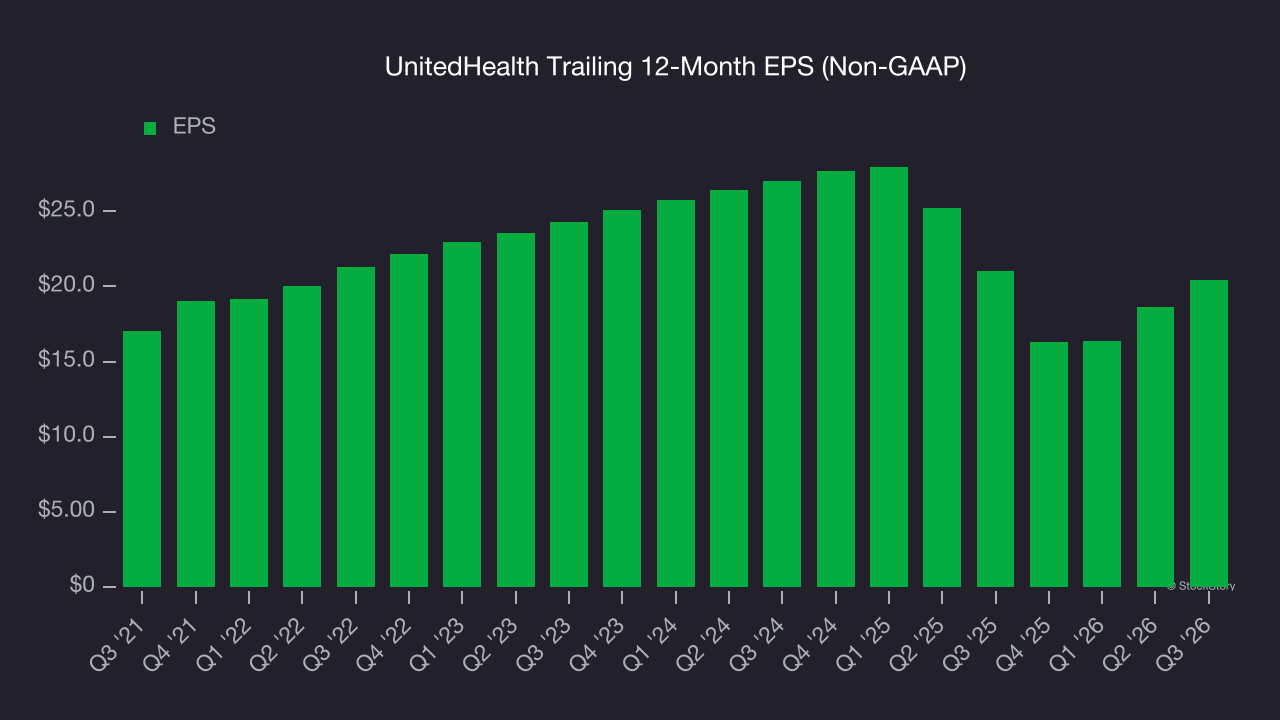
We can take a deeper look into UnitedHealth’s earnings to better understand the drivers of its performance. As we mentioned earlier, UnitedHealth’s adjusted operating margin expanded this quarter but declined by 2.7 percentage points over the last five years. This was the most relevant factor (aside from the revenue impact) behind its lower earnings; interest expenses and taxes can also affect EPS but don’t tell us as much about a company’s fundamentals.
In Q3, UnitedHealth reported adjusted EPS of $4.69, up from $2.92 in the same quarter last year. This print easily cleared analysts’ estimates, and shareholders should be content with the results. Over the next 12 months, Wall Street expects UnitedHealth’s full-year EPS to grow 7.6% from $20.41 to $21.95.
Key Takeaways from UnitedHealth’s Q3 Results
We enjoyed seeing UnitedHealth beat analysts’ full-year EPS guidance expectations this quarter. We were also glad its EPS outperformed Wall Street’s estimates. Overall, we think this was a decent quarter with some key metrics above expectations. The stock traded up 2.7% to $388.24 immediately following the results.
UnitedHealth put up rock-solid earnings, but one quarter doesn’t necessarily make the stock a buy. Let’s see if this is a good investment. When making that decision, it’s important to consider its valuation, business qualities, as well as what has happened in the latest quarter. We cover that in our actionable full research report which you can read here (it’s free).