Global investment bank Goldman Sachs (NYSE: GS) announced better-than-expected revenue in Q3 2026, with sales up 23% year on year to $18.68 billion. Its GAAP profit of $17.01 per share was 30% above analysts’ consensus estimates.
Is now the time to buy Goldman Sachs? Find out by accessing our full research report, it’s free.
Goldman Sachs (GS) Q3 2026 Highlights:
- Revenue: $18.68 billion vs analyst estimates of $16.75 billion (23% year-on-year growth, 11.5% beat)
- Pre-tax Profit: $7.00 billion (37.5% margin)
- EPS (GAAP): $17.01 vs analyst estimates of $13.09 (30% beat)
- Tangible Book Value per Share: $372.64 vs analyst estimates of $338.45 (14.2% year-on-year growth, 10.1% beat)
- Market Capitalization: $270.7 billion
Company Overview
Founded in 1869 as a small commercial paper business in New York City, Goldman Sachs (NYSE: GS) is a global financial institution that provides investment banking, securities, asset management, and consumer banking services to corporations, governments, and individuals.
Revenue Growth
Examining a company’s long-term performance can provide clues about its quality. Any business can have short-term success, but a top-tier one grows for years. Unfortunately, Goldman Sachs’s 3.6% annualized revenue growth over the last five years was sluggish. This fell short of our benchmark for the financials sector and is a tough starting point for our analysis.
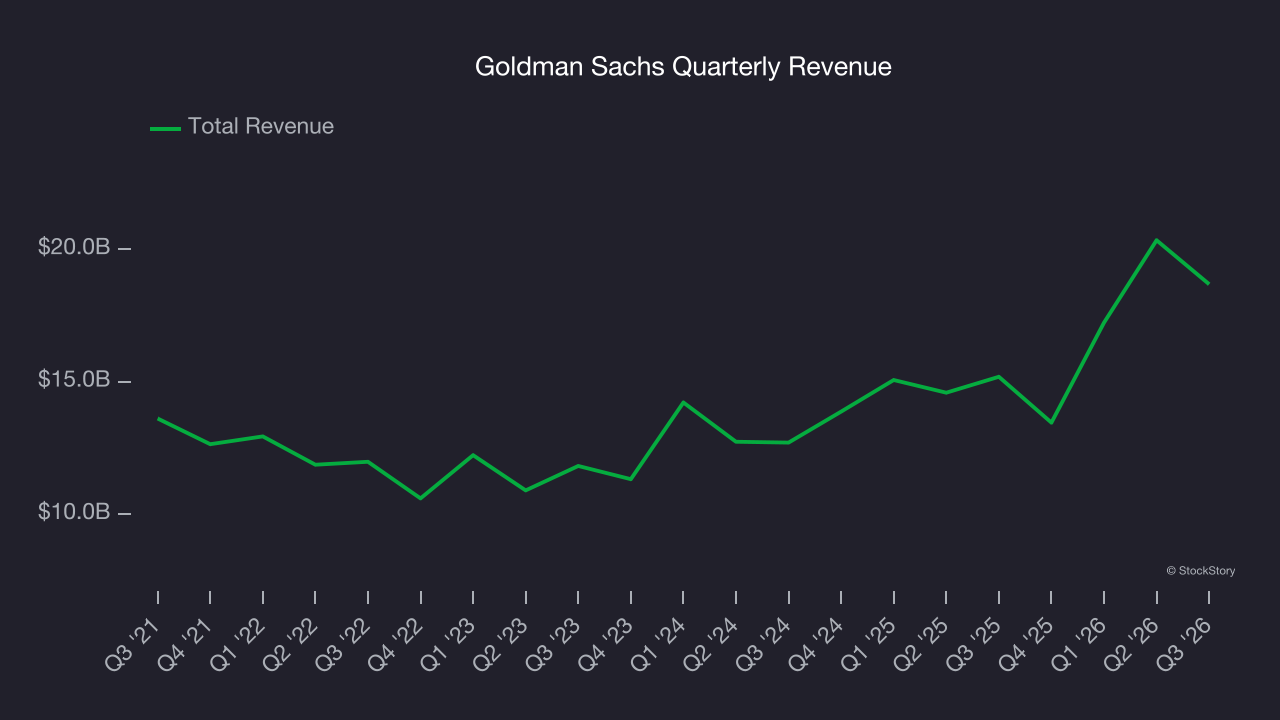
We at StockStory place the most emphasis on long-term growth, but within financials, a half-decade historical view may miss recent interest rate changes, market returns, and industry trends. Goldman Sachs’s annualized revenue growth of 16.9% over the last two years is above its five-year trend, suggesting its demand recently accelerated. 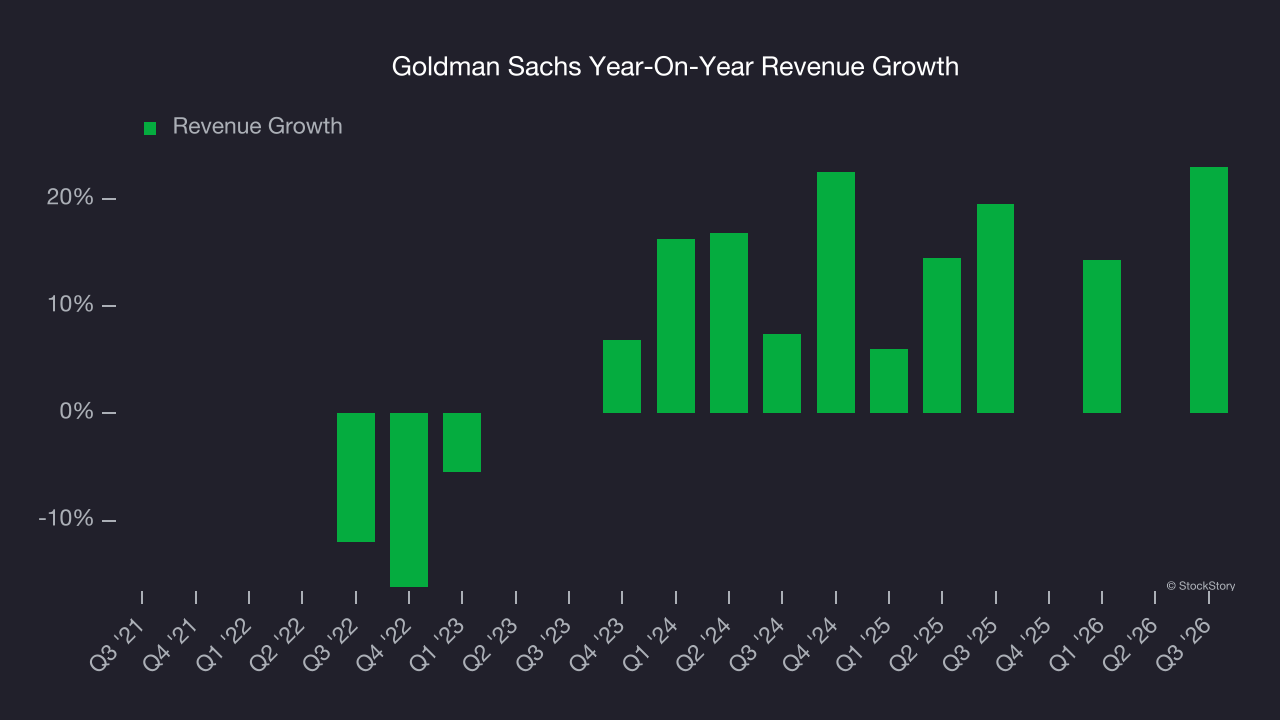 Note: Quarters not shown were determined to be outliers because they were impacted by outsized investment gains/losses that are not indicative of the recurring fundamentals of the business.
We can better understand the company’s revenue dynamics by analyzing its most important segments, Banking & Markets and Asset & Wealth Management, which are 72% and 27% of total revenue. Banking & Markets revenue grew by 7.7% and 25.8% annually over the past five and two years, respectively, both better than its total revenue. At the same time, Asset & Wealth Management revenue decreased by 3.3% per year over the past five years but reversed its trend by growing 7.4% annually on a two-year horizon. These results underperformed its total revenue. 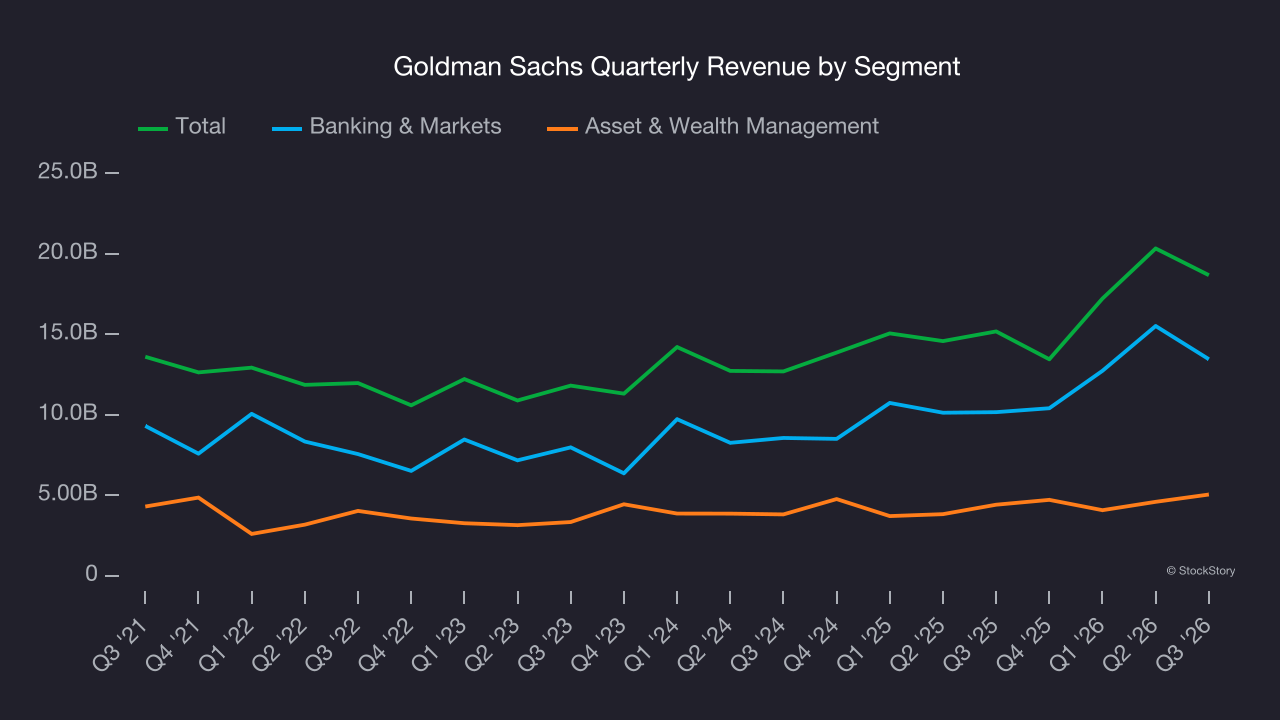
This quarter, Goldman Sachs reported robust year-on-year revenue growth of 23%, and its $18.68 billion of revenue topped Wall Street estimates by 11.5%.
ONE MORE THING: The $21 AI Application Stock Wall Street Forgot. While Wall Street obsesses over who’s building AI, one company is already using it to print money. And nobody’s paying attention.
AI chip stocks trade at ridiculous valuations. This company processes a trillion consumer signals monthly using AI and trades at a third of the price. The gap won’t last. The institutions will figure it out. You need to see this first. Read the FREE Report Before They Notice.
Tangible Book Value Per Share (TBVPS)
Financial firms are valued based on their balance sheet strength and ability to compound book value across diverse business lines.
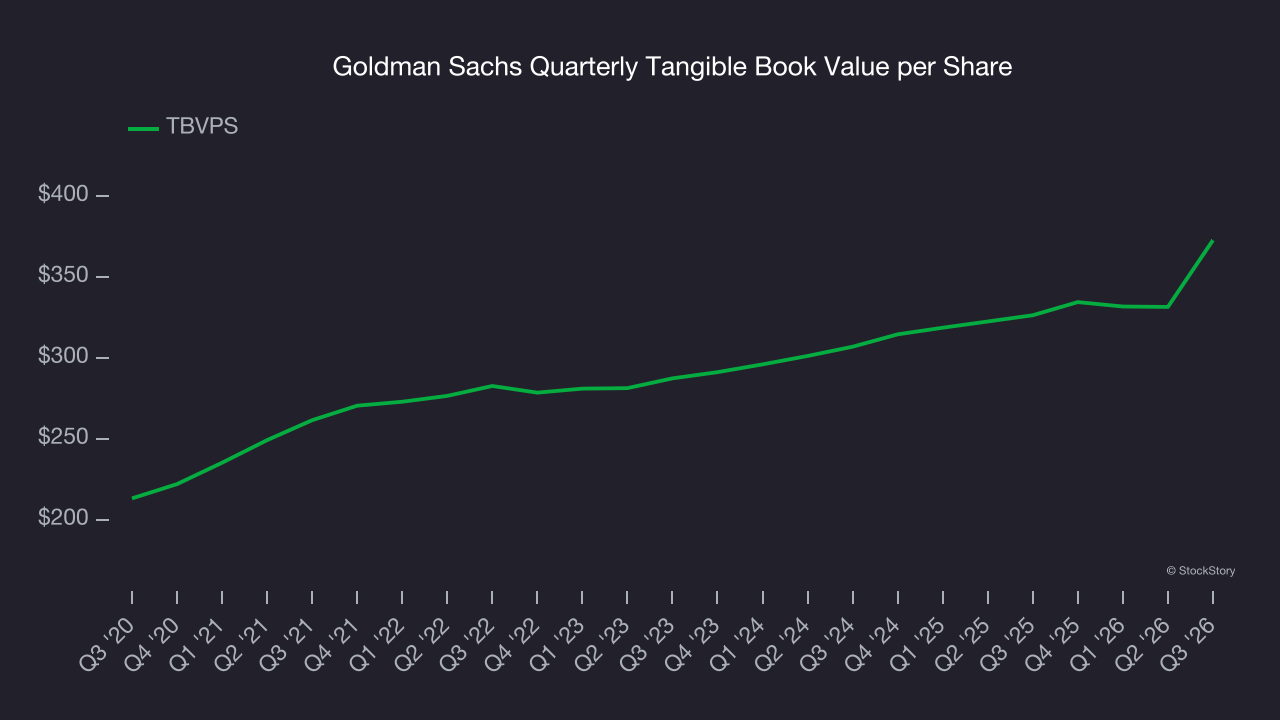
Because of this, tangible book value per share (TBVPS) emerges as the critical performance benchmark for the sector. This metric captures real, liquid net worth per share that reflects the institution’s overall financial health across all business lines. Traditional metrics like EPS are helpful but face distortion from the complexity of diversified operations, M&A activity, and various accounting rules that can obscure true performance across multiple business lines.
Goldman Sachs’s TBVPS grew at a mediocre 7.3% annual clip over the last five years. However, TBVPS growth has accelerated recently, growing by 10.2% annually over the last two years from $306.87 to $372.64 per share.
Tangible Book Value Per Share (TBVPS)
Financial institutions with multiple business lines manage complex balance sheets that span various financial activities. Market valuations reflect this operational complexity, prioritizing balance sheet strength and sustainable book value growth across all business segments.
This is why we consider tangible book value per share (TBVPS) an important metric for the sector. TBVPS represents the real net worth per share across all business segments, providing a clear measure of shareholder equity regardless of the complexity of operations. On the other hand, EPS is often distorted by the diverse nature of operations, mergers, and various accounting treatments across different business units. Book value provides clearer performance insights.
Goldman Sachs’s TBVPS grew at a mediocre 7.3% annual clip over the last five years. However, TBVPS growth has accelerated recently, growing by 10.2% annually over the last two years from $306.87 to $372.64 per share.
Key Takeaways from Goldman Sachs’s Q3 Results
It was good to see Goldman Sachs beat analysts’ EPS expectations this quarter. We were also excited its revenue outperformed Wall Street’s estimates by a wide margin. Zooming out, we think this was a solid print. The stock traded up 3.4% to $923.22 immediately after reporting.
Indeed, Goldman Sachs had a rock-solid quarterly earnings result, but is this stock a good investment here? If you’re making that decision, you should consider the bigger picture of valuation, business qualities, as well as the latest earnings. We cover that in our actionable full research report which you can read here (it’s free).