Over the past six months, Flagstar Financial’s stock price fell to $11.32. Shareholders have lost 19.6% of their capital, which is disappointing considering the S&P 500 has climbed by 13.5%. This was partly due to its softer quarterly results and may have investors wondering how to approach the situation.
Is now the time to buy Flagstar Financial, or should you be careful about including it in your portfolio? Check out our in-depth research report to see what our analysts have to say, it’s free.
Why Do We Think Flagstar Financial Will Underperform?
Even though the stock has become cheaper, we’re sitting this one out for now. Here are three reasons why FLG doesn’t excite us, plus one stock we’d rather own.
1. Net Interest Income Points to Soft Demand
Markets consistently prioritize net interest income over non-recurring fees, recognizing its superior quality compared to the more unpredictable revenue streams.
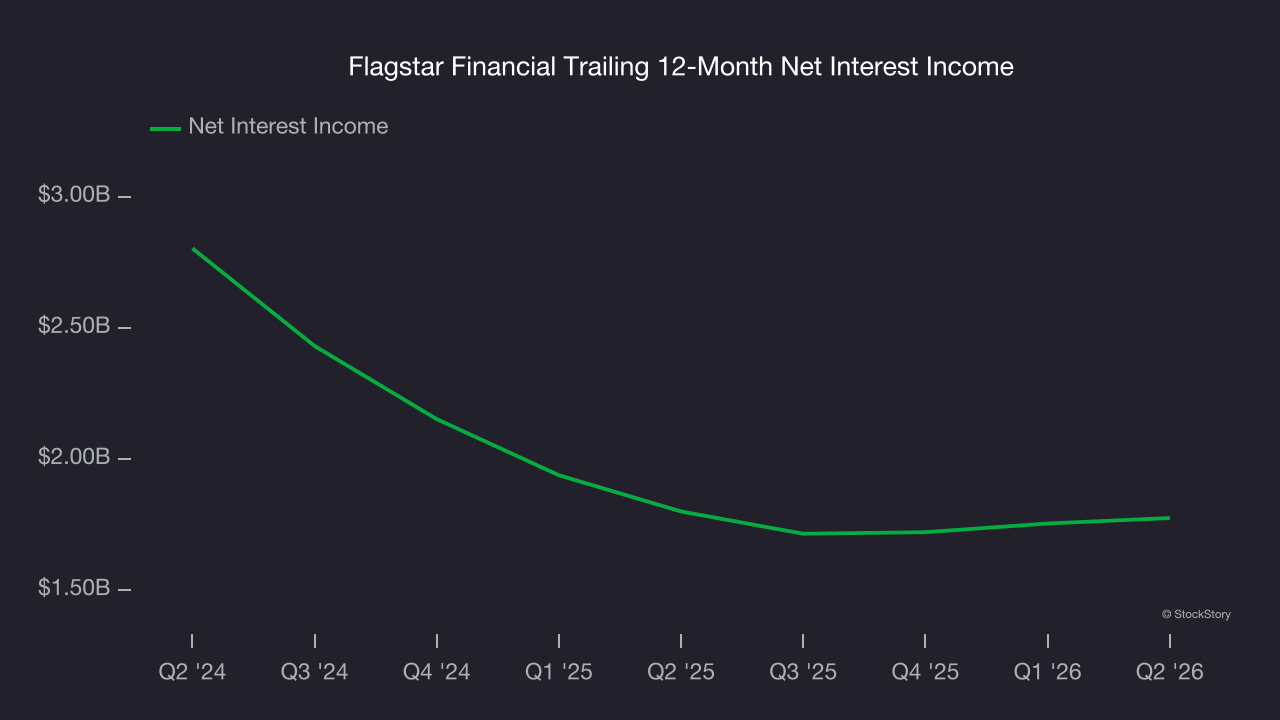
Flagstar Financial’s net interest income has grown at a 7.5% annualized rate over the last five years, worse than the broader banking industry and slower than its total revenue.
2. Low Net Interest Margin Reveals Weak Loan Book Profitability
Net interest margin (NIM) represents the unit economics of a bank by measuring the profitability of its interest-bearing assets relative to its interest-bearing liabilities. It’s a fundamental metric that investors use to assess lending premiums and returns.
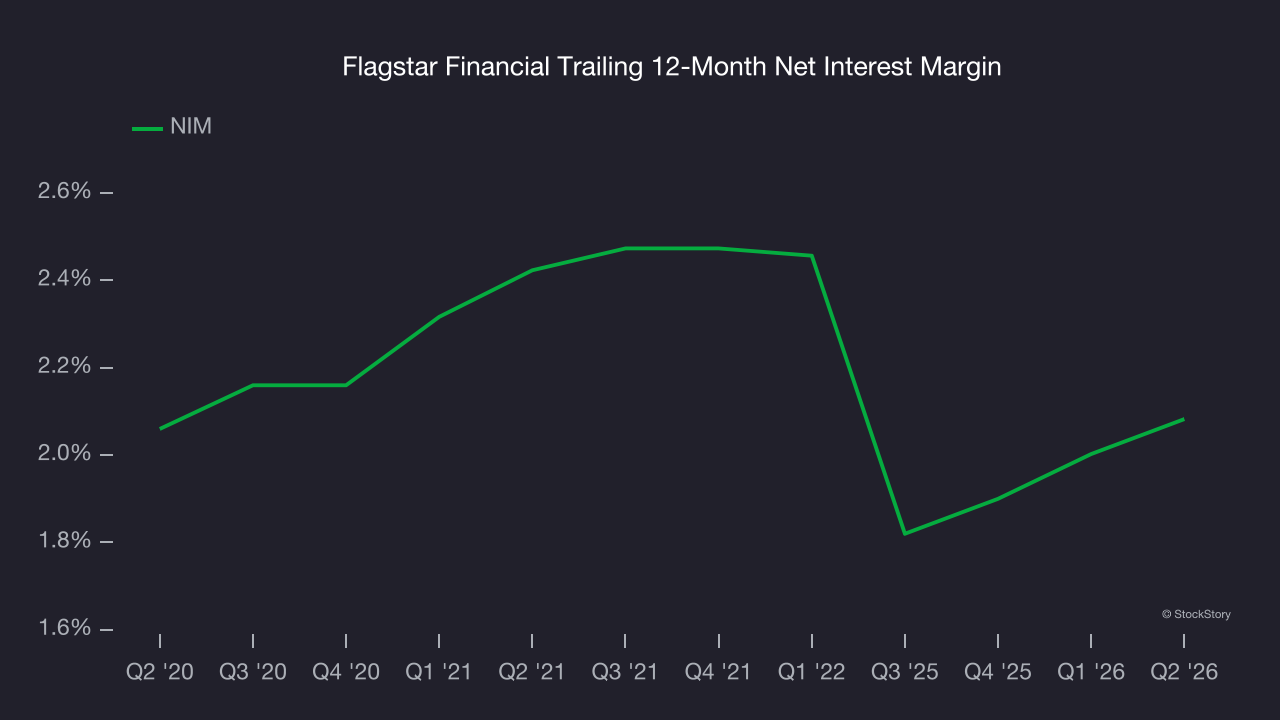
Over the past two years, we can see that Flagstar Financial’s net interest margin averaged a poor 2%. This metric is well below other banks, signaling its loans aren’t very profitable.
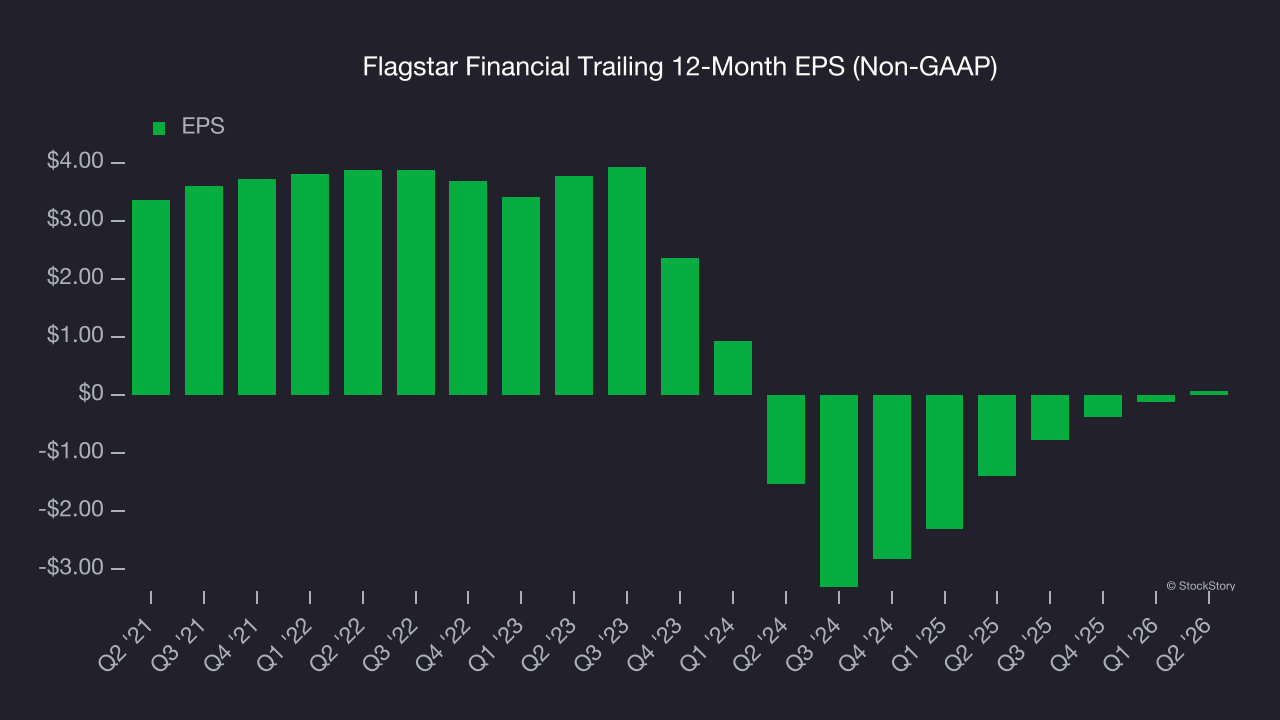
3. EPS Trending Down
Analyzing the long-term change in earnings per share (EPS) shows whether a company’s incremental sales were profitable — for example, revenue could be inflated through excessive spending on advertising and promotions.
Sadly for Flagstar Financial, its EPS declined by 52.6% annually over the last five years while its revenue grew by 9.8%. This tells us the company became less profitable on a per-share basis as it expanded.
Final Judgment
We cheer for all companies supporting the economy, but in the case of Flagstar Financial, we’ll be cheering from the sidelines. After the recent drawdown, the stock trades at 0.6× forward P/B (or $11.32 per share). While this valuation is optically cheap, the potential downside is huge given its shaky fundamentals. There are better stocks to buy right now. We’d recommend looking at an all-weather company that owns household favorite Taco Bell.
Stocks We Like More Than Flagstar Financial
ONE MORE THING: Top 6 Stocks for This Week. This market is separating quality stocks from expensive ones fast. AI is taking down whole sectors with no warning. In a rotation this fast, you need more than a list of good companies.
Our AI system flagged Palantir before it ran 1,662% between October 2022 and February 2026. AppLovin before it ran 753% between February 2024 and February 2026. Nvidia before it ran 1,178% between January 2023 and February 2026. Each week it produces 6 new names that pass the same tests. Get Our Top 6 Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Kadant (+214% between June 2020 and June 2025). Find your next big winner with StockStory today.