Jabil has been treading water for the past six months, recording a small return of 2.1% while holding steady at $299.23. The stock also fell short of the S&P 500’s 14.3% gain during that period.
Is now the time to buy JBL? Find out in our full research report, it’s free.
Why Are We Positive on JBL?
With manufacturing facilities spanning the globe from China to Mexico to the United States, Jabil (NYSE: JBL) provides electronics design, manufacturing, and supply chain solutions to companies across various industries, from healthcare to automotive to cloud computing.
1. Skyrocketing Revenue Shows Strong Momentum
We at StockStory place the most emphasis on long-term growth, but within business services, a stretched historical view may miss recent innovations or disruptive industry trends. Jabil’s annualized revenue growth of 11.6% over the last two years is above its five-year trend, suggesting its demand recently accelerated. 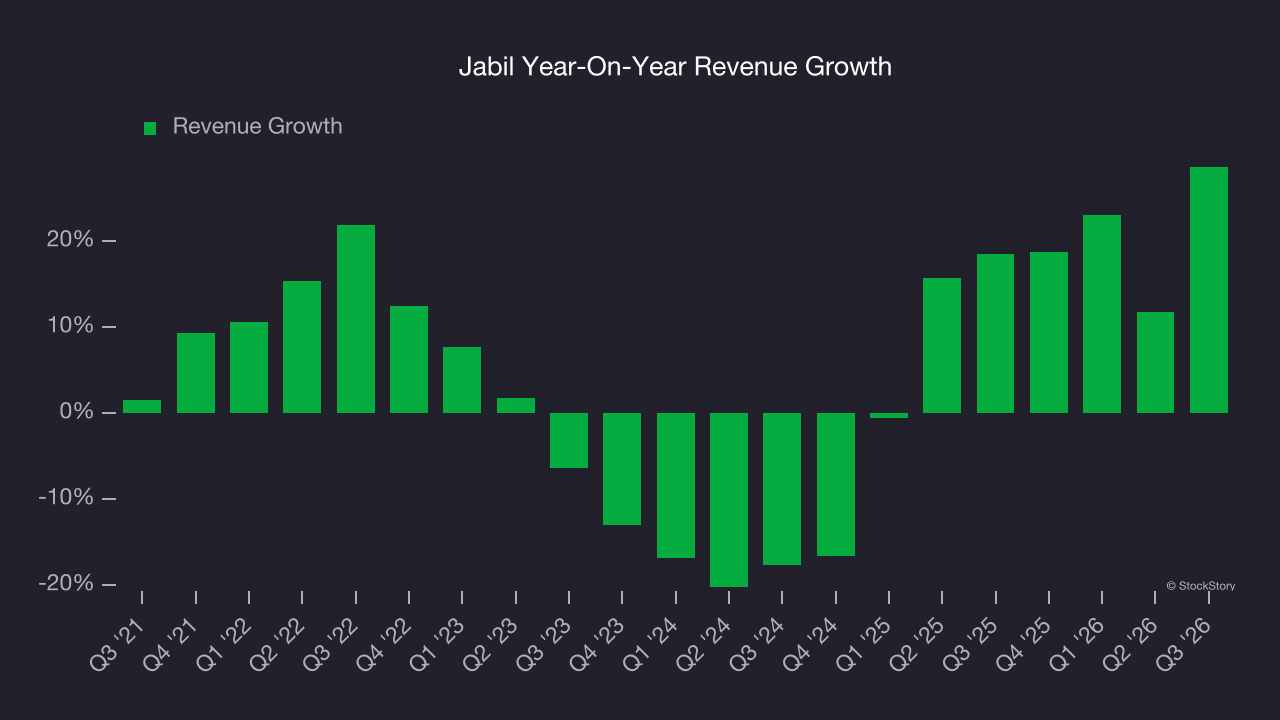
2. Economies of Scale Give It Negotiating Leverage with Suppliers
With $35.95 billion in revenue over the past 12 months, Jabil is a behemoth in the business services sector and benefits from economies of scale, giving it an edge in distribution. This also enables it to gain more leverage on its fixed costs than smaller competitors and the flexibility to offer lower prices. However, its scale is a double-edged sword because it’s challenging to maintain high growth rates when you’ve already captured a large portion of the addressable market. For Jabil to boost its sales, it likely needs to adjust its prices, launch new offerings, or lean into foreign markets.
3. Outstanding Long-Term EPS Growth
We track the long-term change in earnings per share (EPS) because it highlights whether a company’s growth is profitable.
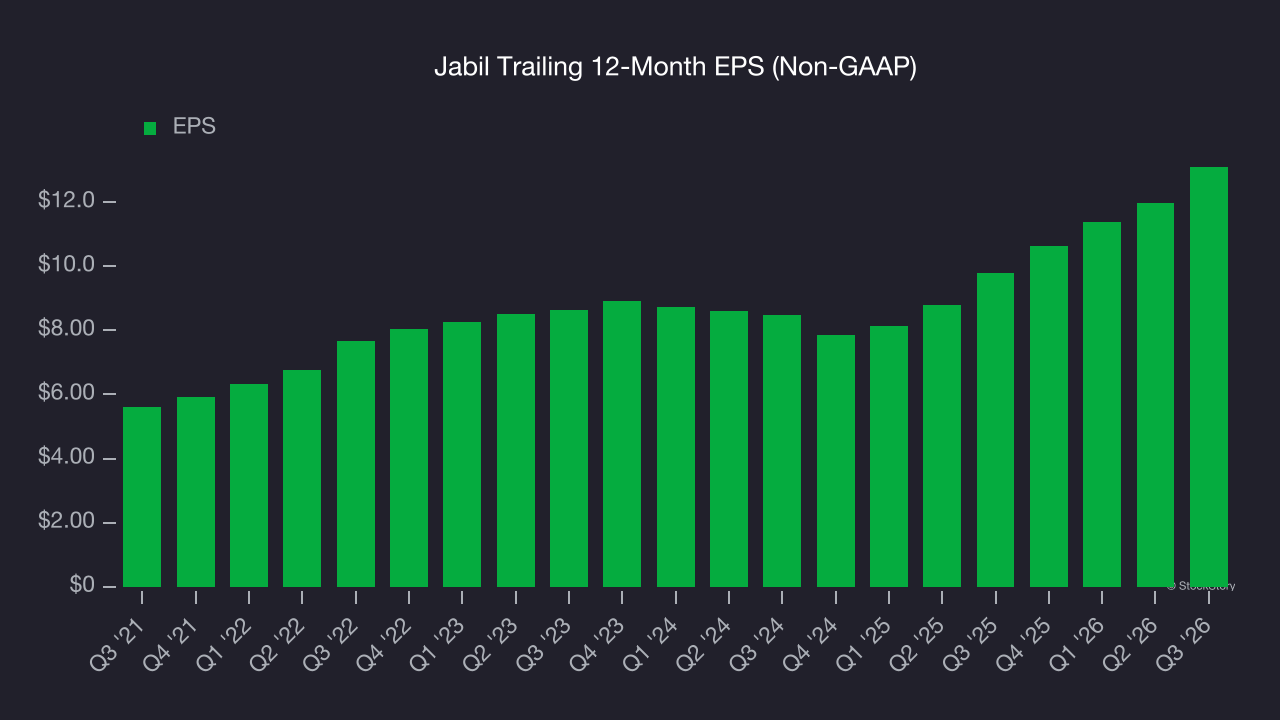
Jabil’s EPS grew at 18.5% compounded annual growth rate over the last five years, higher than its 4.2% annualized revenue growth. This tells us the company became more profitable on a per-share basis as it expanded.
Final Judgment
These are just a few reasons why Jabil ranks highly on our list. With its shares underperforming the market lately, the stock trades at 16.9× forward P/E (or $299.23 per share). Is now the right time to buy? See for yourself in our comprehensive research report, it’s free.
Stocks We Like Even More Than Jabil
WHILE YOU’RE HERE: Top 9 Market-Beating Stocks. The best stocks don’t just beat the market once. They do it again. And again. Robust revenue growth, rising free cash flow, returns on capital that leave their competition in the dust. The market has already rewarded these businesses.
But our AI platform says the party isn’t over. Find out which 9 stocks made the cut this week — FREE. Get Our Top 9 Market-Beating Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Kadant (+214% between June 2020 and June 2025). Find your next big winner with StockStory today.