Global airline Delta Air Lines (NYSE: DAL) beat Wall Street’s revenue expectations in Q3 2026, with sales up 21.1% year on year to $20.19 billion. Its GAAP profit of $1.15 per share was 35.4% below analysts’ consensus estimates.
Is now the time to buy Delta? Find out by accessing our full research report, it’s free.
Delta (DAL) Q3 2026 Highlights:
- Revenue: $20.19 billion vs analyst estimates of $19.37 billion (21.1% year-on-year growth, 4.2% beat)
- EPS (GAAP): $1.15 vs analyst expectations of $1.78 (35.4% miss)
- EPS (GAAP) guidance for the full year is $5.35 at the midpoint, missing analyst estimates by 4.5%
- Operating Margin: 7.2%, down from 10.1% in the same quarter last year
- Free Cash Flow Margin: 2.3%, down from 4.1% in the same quarter last year
- Revenue Passenger Miles: in line with the same quarter last year
- Market Capitalization: $53.73 billion
"Demand remains strong, supported by consumers' growing preference for experiences and travel, with air travel continuing to be one of the best values in the consumer economy. Against this backdrop, we delivered September quarter pre-tax profit of $1.5 billion, matching last year's performance, and generated $1.9 billion of free cash flow year-to-date. Our resilience reflects the structural durability we've built over many years, enabling us to effectively navigate one of the most elevated fuel environments in recent times. The foundation of that resilience is our people, whose commitment to delivering for our customers continues to set Delta apart," said Ed Bastian, Delta's chief executive officer.
Company Overview
One of the ‘Big Four’ airlines in the US, Delta Air Lines (NYSE: DAL) is a major global air carrier that serves both business and leisure travelers through its domestic and international flights.
Revenue Growth
Examining a company’s long-term performance can provide clues about its quality. Any business can have short-term success, but a top-tier one grows for years. Over the last five years, Delta grew its sales at a 24.1% compounded annual growth rate. Though this growth is acceptable on an absolute basis, we need to see more than just topline growth for the consumer discretionary sector, which can display significant earnings volatility. This means our bar for the sector is particularly high, reflecting the non-essential and hit-driven nature of the products and services offered. Additionally, five-year CAGR starts around Covid, when revenue was depressed then rebounded.
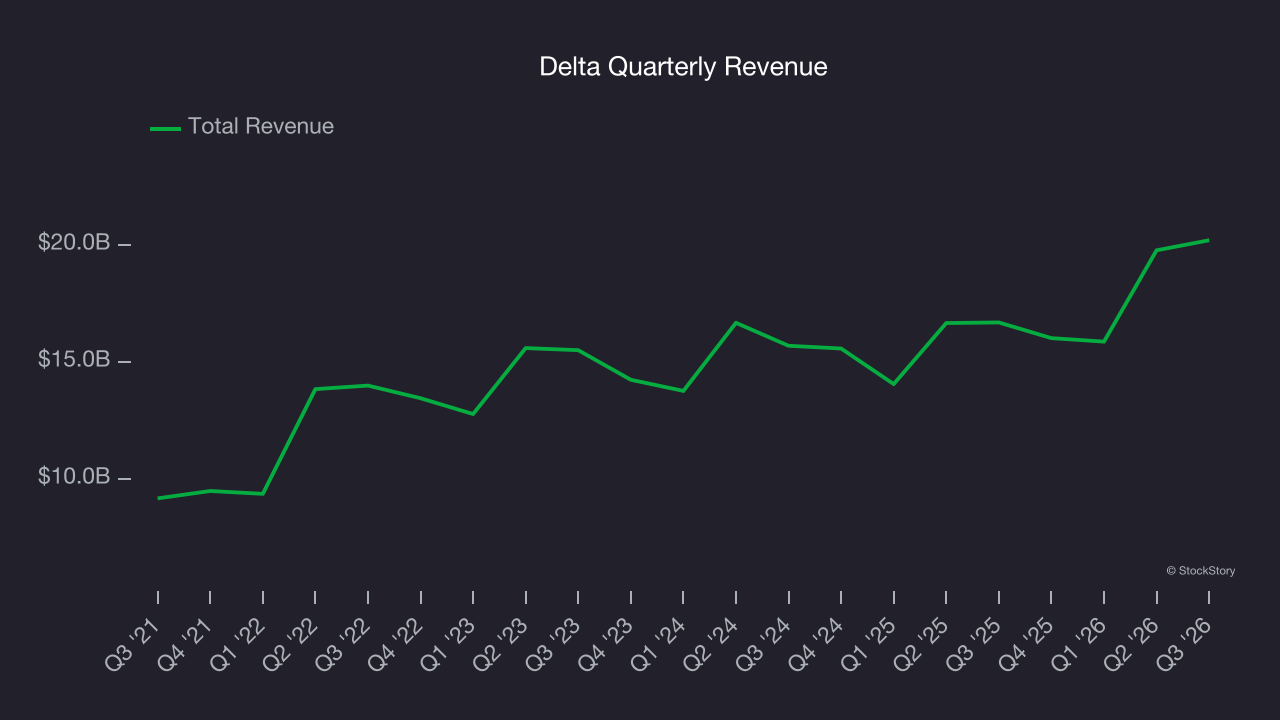
We at StockStory place the most emphasis on long-term growth, but within consumer discretionary, a stretched historical view may miss a company riding a successful new property or trend. Delta’s recent performance shows its demand has slowed as its annualized revenue growth of 9.1% over the last two years was below its five-year trend. We’re wary when companies in the sector see decelerations in revenue growth, as it could signal changing consumer tastes aided by low switching costs. 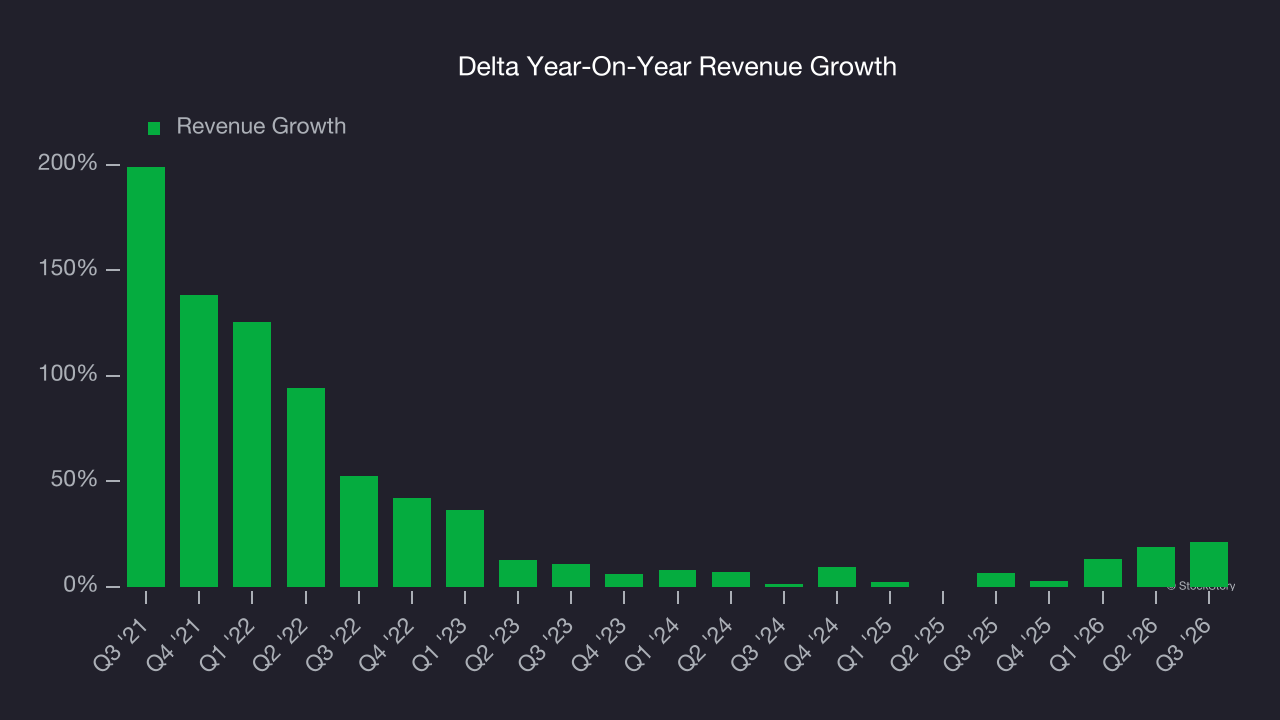
Delta also discloses its number of revenue passenger miles, which reached 68.13 billion in the latest quarter. Over the last two years, Delta’s revenue passenger miles averaged 1.2% year-on-year growth. Because this number is lower than its revenue growth during the same period, we can see the company’s monetization has risen. 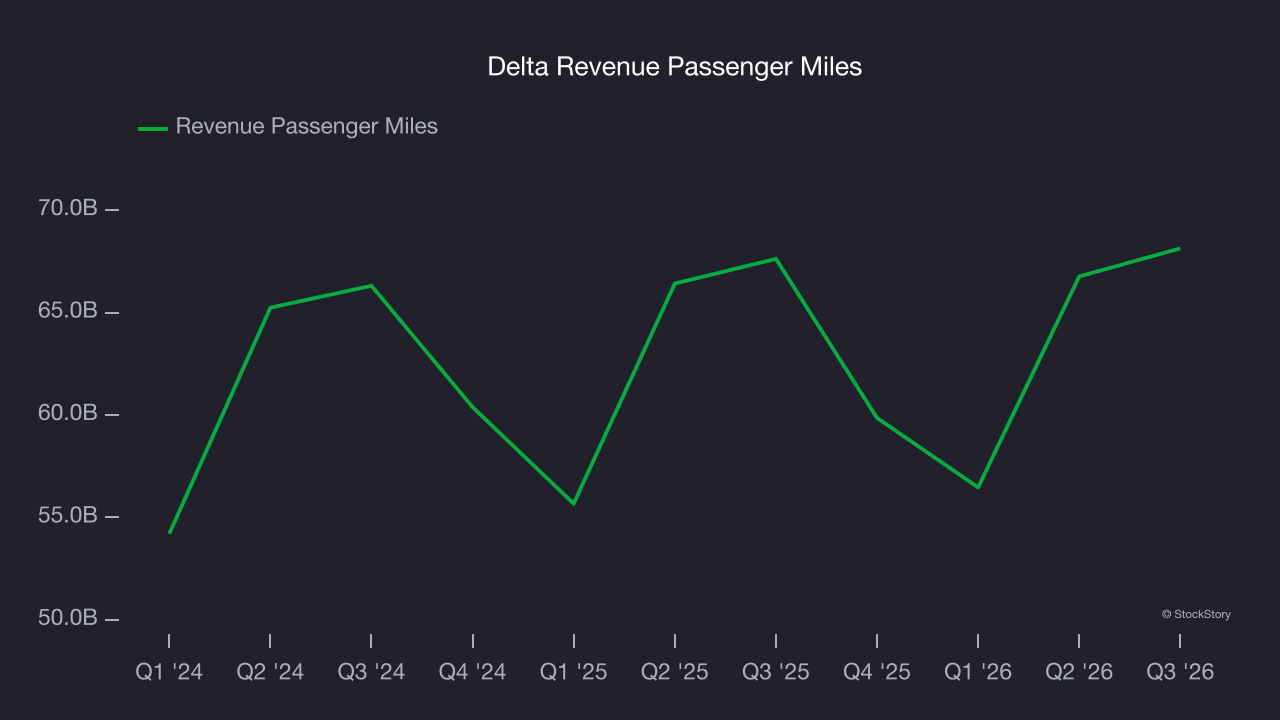
This quarter, Delta reported robust year-on-year revenue growth of 21.1%, and its $20.19 billion of revenue topped Wall Street estimates by 4.2%.
Looking ahead, sell-side analysts expect revenue to grow 6.2% over the next 12 months, a slight deceleration versus the last two years. This projection doesn’t excite us and indicates its products and services will face some demand challenges.
ONE MORE THING: 3 Hidden Platforms Growing 3X Faster than Amazon, Google, and PayPal. Amazon, Google, and Meta all followed the same playbook: Dominate an ignored market. Build an unbeatable moat. Scale until you’re unstoppable.
These three platforms are running that exact playbook right now. The early investors in Amazon made fortunes. The early investors in these could do the same. Get All 3 Stocks Here for FREE.
Operating Margin
Operating margin is an important measure of profitability as it shows the portion of revenue left after accounting for all core expenses — everything from the cost of goods sold to advertising and wages. It’s also useful for comparing profitability across companies with different levels of debt and tax rates because it excludes interest and taxes.
Delta’s operating margin has been trending down over the last 12 months and averaged 8.4% over the last two years. The company’s profitability was mediocre for a consumer discretionary business and shows it couldn’t pass its higher operating expenses onto its customers.
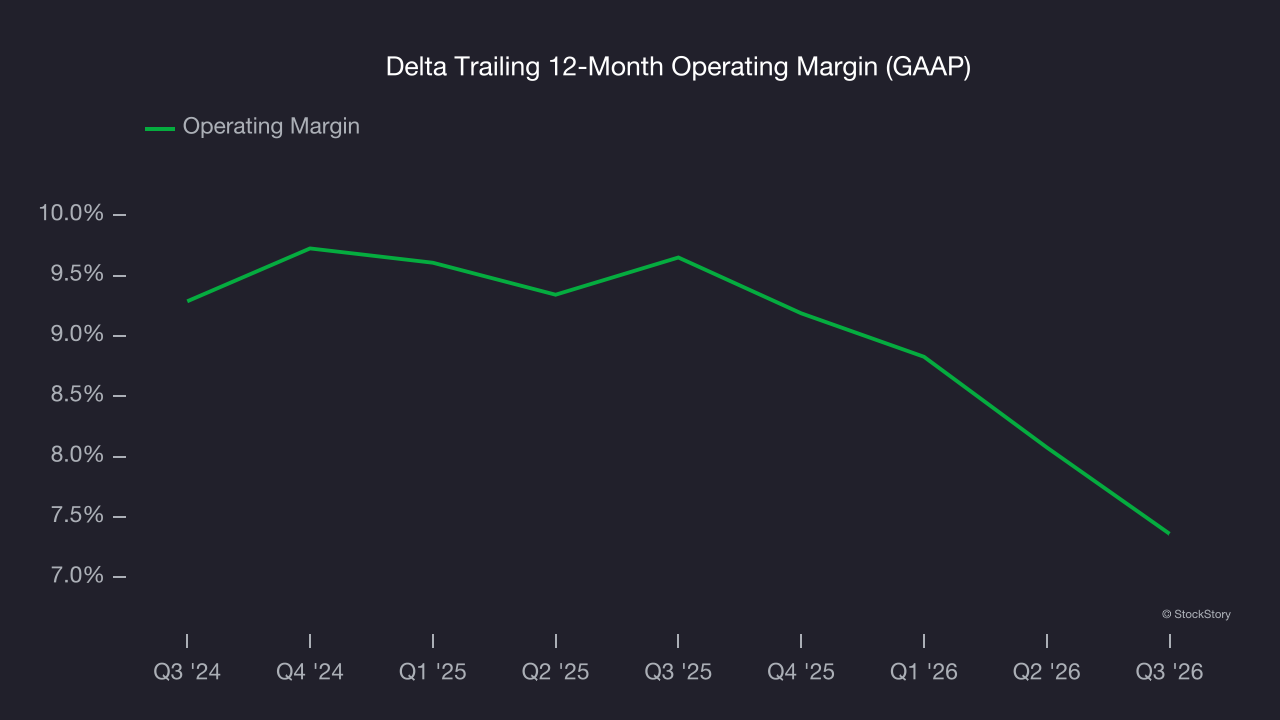
This quarter, Delta generated an operating margin profit margin of 7.2%, down 2.9 percentage points year on year. This contraction shows it was less efficient because its expenses grew faster than its revenue.
Earnings Per Share
Revenue trends explain a company’s historical growth, but the long-term change in earnings per share (EPS) points to the profitability of that growth — for example, a company could inflate its sales through excessive spending on advertising and promotions.
Delta’s full-year EPS flipped from negative to positive over the last five years. This is encouraging and shows it’s at a critical moment in its life.
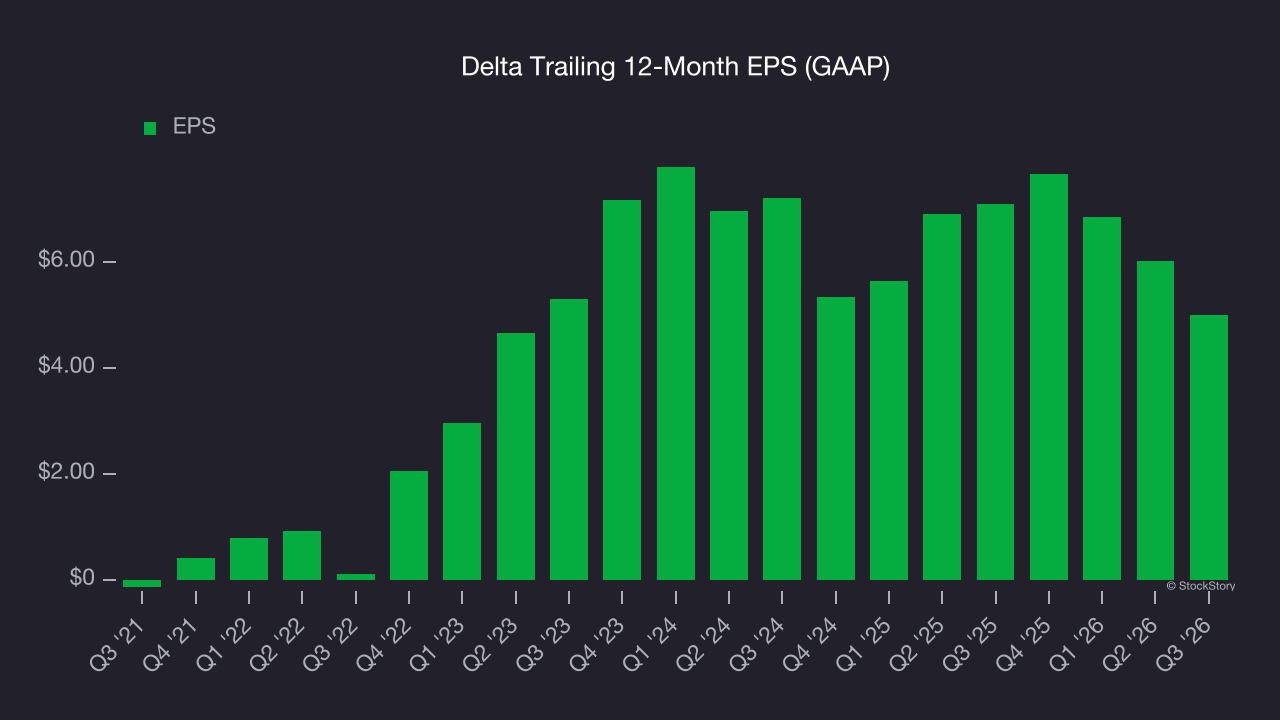
In Q3, Delta reported EPS of $1.15, down from $2.17 in the same quarter last year. This print missed analysts’ estimates, but we care more about long-term EPS growth than short-term movements. Over the next 12 months, Wall Street expects Delta’s full-year EPS to grow 38.9% from $5.00 to $6.95.
Key Takeaways from Delta’s Q3 Results
We enjoyed seeing Delta beat analysts’ revenue expectations this quarter. On the other hand, its EPS missed and its full-year EPS guidance fell short of Wall Street’s estimates. Overall, this was a softer quarter. The stock traded down 3.8% to $79.05 immediately following the results.
Delta didn’t show its best hand this quarter, but does that create an opportunity to buy the stock right now? When making that decision, it’s important to consider its valuation, business qualities, as well as what has happened in the latest quarter. We cover that in our actionable full research report which you can read here (it’s free).