The end of the earnings season is always a good time to take a step back and see who shined (and who didn’t). Let’s take a look at how data & business process services stocks fared in Q2, starting with SS&C (NASDAQ: SSNC).
A combination of increasing reliance on data and analytics across various industries and the desire for cost efficiency through outsourcing could mean that companies in this space gain. As functions such as payroll, HR, and credit risk assessment rely on more digitization, key players in the data & business process services industry could see increased demand. On the other hand, the sector faces headwinds from growing regulatory scrutiny on data privacy and security, with laws like GDPR and evolving U.S. regulations potentially limiting data collection and monetization strategies. Additionally, rising cyber threats pose risks to firms handling sensitive personal and financial information, creating outsized headline risk when things go wrong in this area.
The 10 data & business process services stocks we track reported a mixed Q2. As a group, revenues beat analysts’ consensus estimates by 1.9% while next quarter’s revenue guidance was 3.1% below.
Amidst this news, share prices of the companies have had a rough stretch. On average, they are down 6.2% since the latest earnings results.
SS&C (NASDAQ: SSNC)
Founded in 1986 as a bridge between technology and financial services, SS&C Technologies (NASDAQ: SSNC) provides software and software-enabled services that help financial firms and healthcare organizations automate complex business processes.
SS&C reported revenues of $1.70 billion, up 10.3% year on year. This print exceeded analysts’ expectations by 2.1%. Overall, it was a strong quarter for the company with a solid beat of analysts’ billings estimates and an impressive beat of analysts’ full-year EPS guidance estimates.
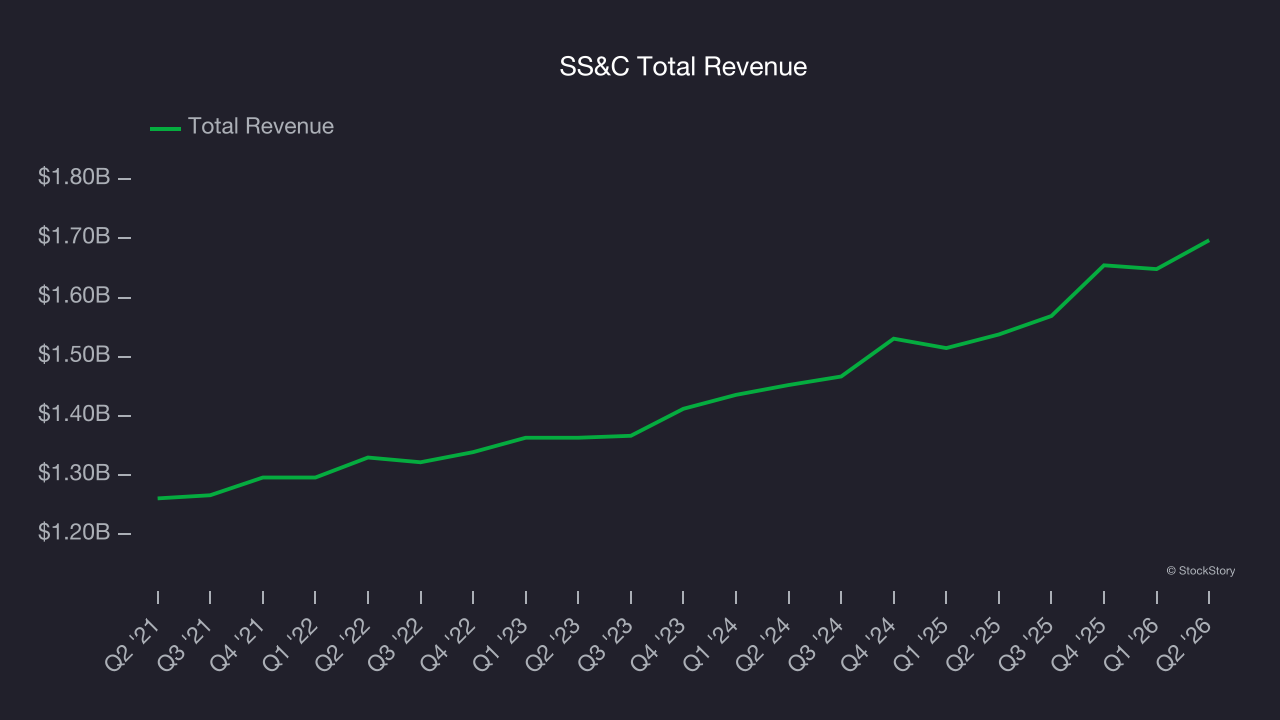
Interestingly, the stock is up 20% since reporting and currently trades at $80.33.
Is now the time to buy SS&C? Access our full analysis of the earnings results here, it’s free.
Best Q2: EXL (NASDAQ: EXLS)
Originally founded as an outsourcing company in 1999 before evolving into a technology-focused enterprise, EXL (NASDAQ: EXLS) provides data analytics and AI-powered digital operations solutions that help businesses transform their operations and make better decisions.
EXL reported revenues of $594.8 million, up 15.6% year on year, outperforming analysts’ expectations by 3.5%. The business had a very strong quarter with full-year revenue guidance beating analysts’ expectations and a beat of analysts’ EPS estimates.
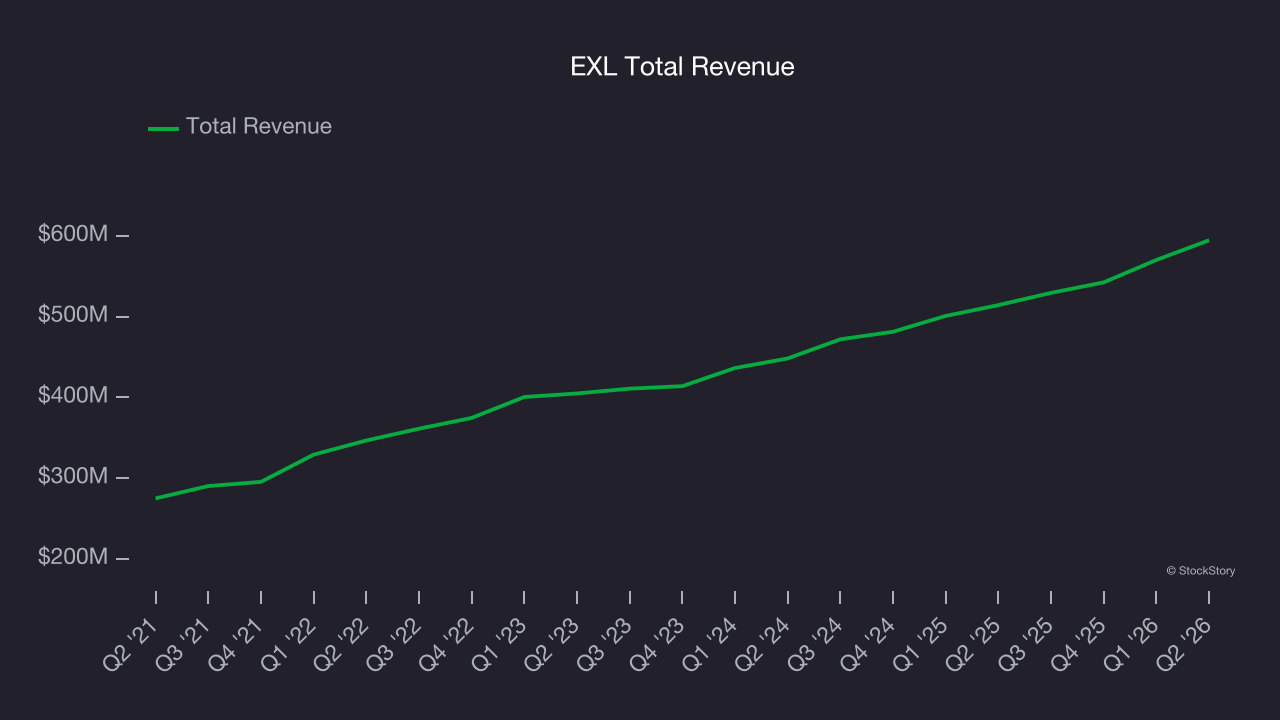
EXL scored the highest full-year guidance raise in the group. The market seems happy with the results as the stock is up 20.8% since reporting. It currently trades at $36.89.
Is now the time to buy EXL? Access our full analysis of the earnings results here, it’s free.
Weakest Q2: CoStar (NASDAQ: CSGP)
With a research department that makes over 10,000 property updates daily to its 35-year-old database, CoStar Group (NASDAQ: CSGP) provides comprehensive real estate data, analytics, and online marketplaces for commercial and residential properties in the U.S. and U.K.
CoStar reported revenues of $925 million, up 18.4% year on year, in line with analysts’ expectations. It was a slower quarter as it posted full-year revenue guidance missing analysts’ expectations and full-year EPS guidance in line with analysts’ estimates.
CoStar delivered the weakest full-year guidance update among its peers. As expected, the stock is down 1.9% since the results and currently trades at $29.76.
Read our full analysis of CoStar’s results here.
Verisk (NASDAQ: VRSK)
Processing over 2.8 billion insurance transaction records annually through one of the world's largest private databases, Verisk Analytics (NASDAQ: VRSK) provides data, analytics, and technology solutions that help insurance companies assess risk, detect fraud, and make better business decisions.
Verisk reported revenues of $806.3 million, up 4.4% year on year. This result was in line with analysts’ expectations. Aside from that, it was a mixed quarter as it also produced a beat of analysts’ EPS estimates but a slight miss of analysts’ full-year EPS guidance estimates.
Verisk had the slowest revenue growth of the whole group. The stock is down 18.4% since reporting and currently trades at $173.20.
Read our full, actionable report on Verisk here, it’s free.
Fair Isaac Corporation (NYSE: FICO)
Creator of the three-digit number that can determine whether you get a mortgage or credit card, Fair Isaac Corporation (NYSE: FICO) develops analytics software and the widely used FICO Score, which is the standard measure of consumer credit risk in the United States.
Fair Isaac Corporation reported revenues of $674.2 million, up 25.7% year on year. This print missed analysts’ expectations by 1.5%. It was a slower quarter as it also logged full-year revenue guidance slightly missing analysts’ expectations.
Fair Isaac Corporation had the weakest performance against analyst estimates in the group. The stock is down 48.5% since reporting and currently trades at $707.01.
Read our full, actionable report on Fair Isaac Corporation here, it’s free.
Market Update
Over the past year, investors have been forced to repeatedly answer the same question: what is the market’s biggest risk? The answer has changed several times, and each shift has reshaped market leadership.
Late in 2025 and early 2026, artificial intelligence became the market’s primary uncertainty. Investors questioned whether AI would erode software pricing power and weaken competitive moats as AI made it easier to replicate once-differentiated products.
By the spring, technology took a back seat to geopolitics. The U.S. conflict with Iran briefly became the market’s dominant narrative, raising concerns about oil prices, inflation, and global growth. But as energy markets remained orderly and fears of a prolonged supply disruption faded, investors quickly turned their focus back to fundamentals.
Want to invest in winners with rock-solid fundamentals? Check out our 9 Best Market-Beating Stocks and add them to your watchlist. These companies are poised for growth regardless of the political or macroeconomic climate.