What a brutal six months it’s been for Piper Sandler. The stock has dropped 22.7% and now trades at $64.38, rattling many shareholders. This might have investors contemplating their next move.
Is now the time to buy Piper Sandler, or should you be careful about including it in your portfolio? Dive into our full research report to see our analyst team’s opinion, it’s free.
Why Is Piper Sandler Not Exciting?
Even with the cheaper entry price, we don’t have much confidence in Piper Sandler. Here are three reasons you should be careful with PIPR, plus one stock we’d rather own.
1. Long-Term Revenue Growth Disappoints
Examining a company’s long-term performance can provide clues about its quality. Any business can put up a good quarter or two, but the best consistently grow over the long haul.
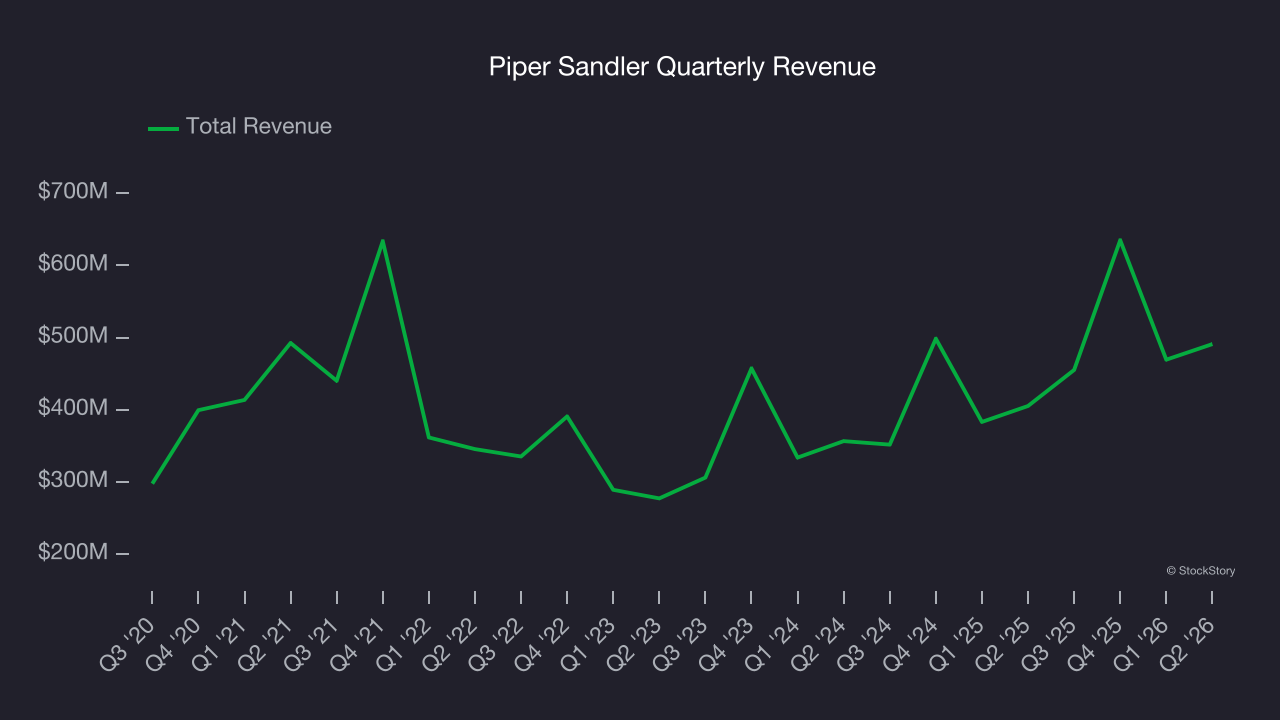
Over the last five years, Piper Sandler grew its revenue at a tepid 5% compounded annual growth rate. This was below our standard for the financials sector.
2. EPS Barely Growing
Analyzing the long-term change in earnings per share (EPS) shows whether a company’s incremental sales were profitable — for example, revenue could be inflated through excessive spending on advertising and promotions.
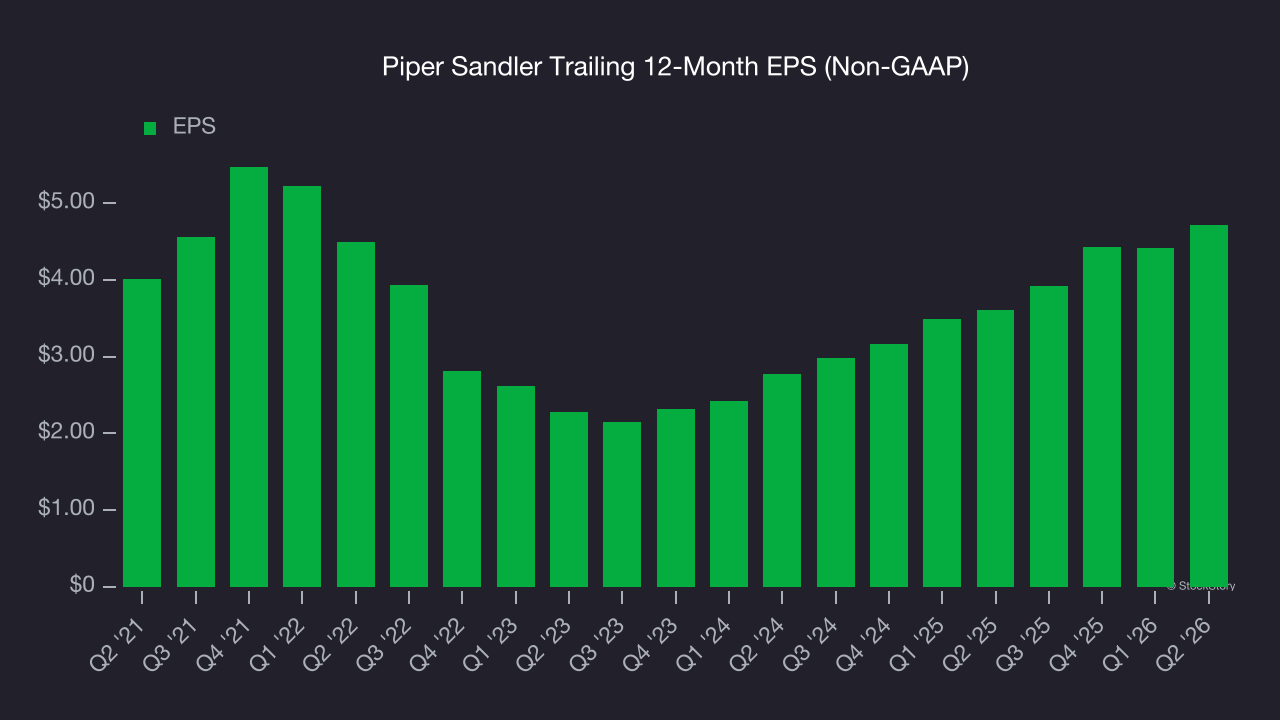
Piper Sandler’s weak 3.3% annual EPS growth over the last five years aligns with its revenue performance. On the bright side, this tells us its incremental sales were profitable.
3. Steady Increase in TBVPS Highlights Solid Asset Growth
Tangible book value per share (TBVPS) is a crucial metric that measures the actual value of shareholders’ equity, stripping out goodwill and other intangible assets that may not be recoverable in a worst-case scenario.
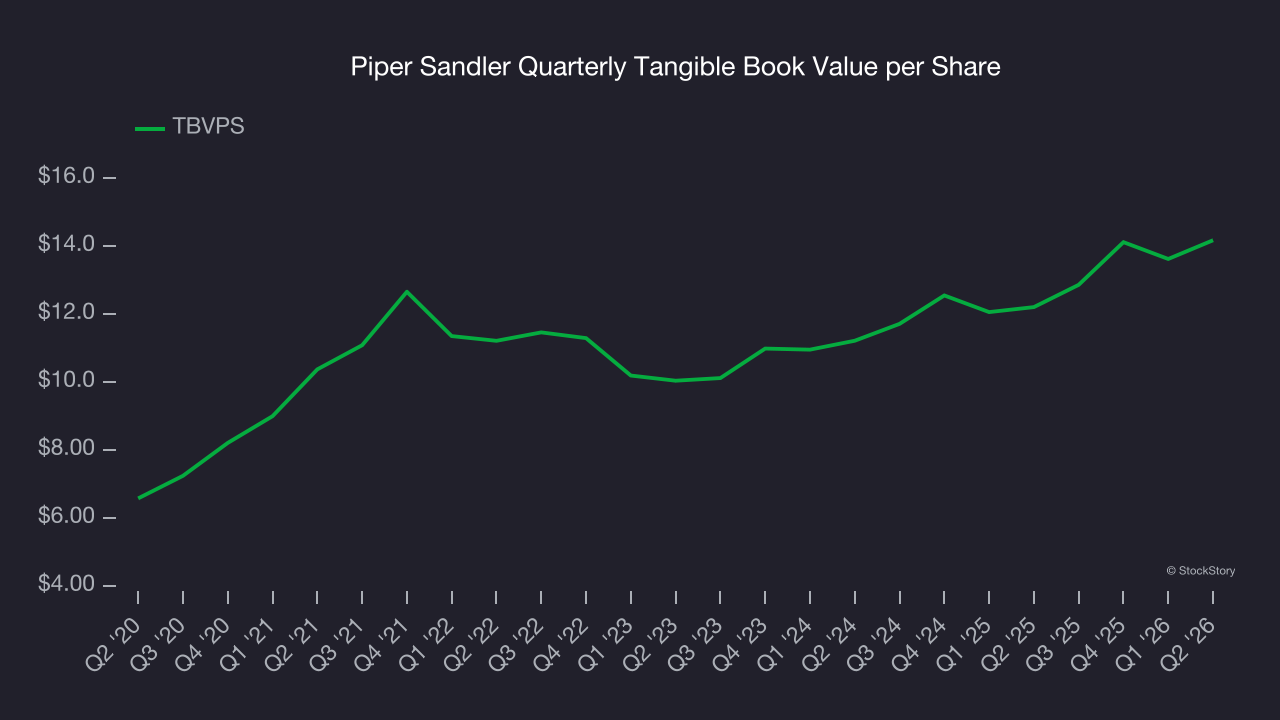
Although Piper Sandler’s TBVPS increased by a meager 6.4% annually over the last five years, the good news is that its growth has recently accelerated as TBVPS grew at a solid 12.4% annual clip over the past two years (from $11.21 to $14.17 per share).
Final Judgment
Piper Sandler isn’t a terrible business, but it isn’t one of our picks. Following the recent decline, the stock trades at 12.8× forward P/E (or $64.38 per share). While this valuation is fair, the upside isn’t great compared to the potential downside. We’re fairly confident there are better stocks to buy right now. We’d suggest looking at a top digital advertising platform riding the creator economy.
Stocks We Would Buy Instead of Piper Sandler
ONE MORE THING: Top 5 Growth Stocks. The biggest stock winners almost always had one thing in common before they ran. Revenue growing like crazy. Meta. CrowdStrike. Broadcom. Our AI flagged all three. They returned 315%, 314%, and 455%, respectively.
Find out which 5 stocks it’s flagging this month — FREE. Get Our Top 5 Growth Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Tecnoglass (+1,552% between June 2020 and June 2025). Find your next big winner with StockStory today.