Over the past six months, Ameresco’s stock price fell to $21.01. Shareholders have lost 19.2% of their capital, which is disappointing considering the S&P 500 has climbed by 14.3%. This might have investors contemplating their next move.
Is there a buying opportunity in Ameresco, or does it present a risk to your portfolio? See what our analysts have to say in our full research report, it’s free.
Why Is Ameresco Not Exciting?
Despite the more favorable entry price, we’re cautious about Ameresco. Here are three reasons we avoid AMRC, plus one stock we’d rather own.
1. EPS Trending Down
Analyzing the long-term change in earnings per share (EPS) shows whether a company’s incremental sales were profitable — for example, revenue could be inflated through excessive spending on advertising and promotions.
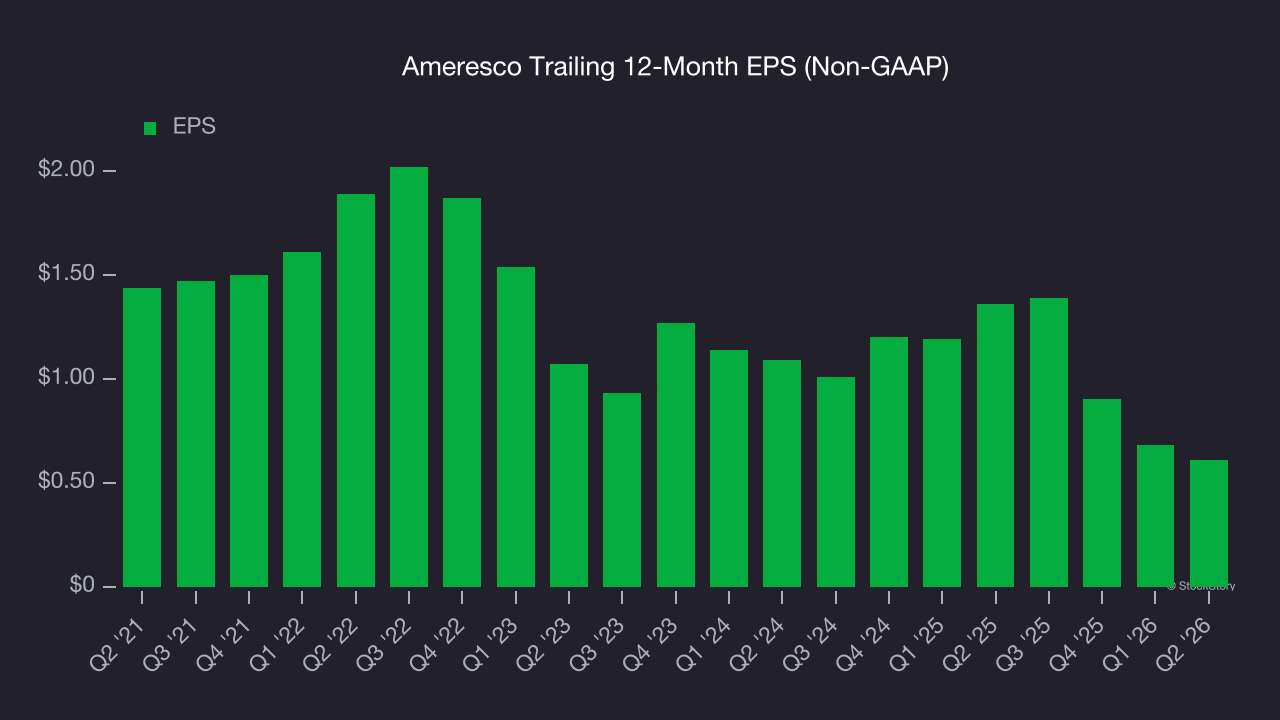
Sadly for Ameresco, its EPS declined by 15.7% annually over the last five years while its revenue grew by 12.5%. This tells us the company became less profitable on a per-share basis as it expanded.
2. Cash Burn Ignites Concerns
Free cash flow isn’t a prominently featured metric in company financials and earnings releases, but we think it’s telling because it accounts for all operating and capital expenses, making it tough to manipulate. Cash is king.
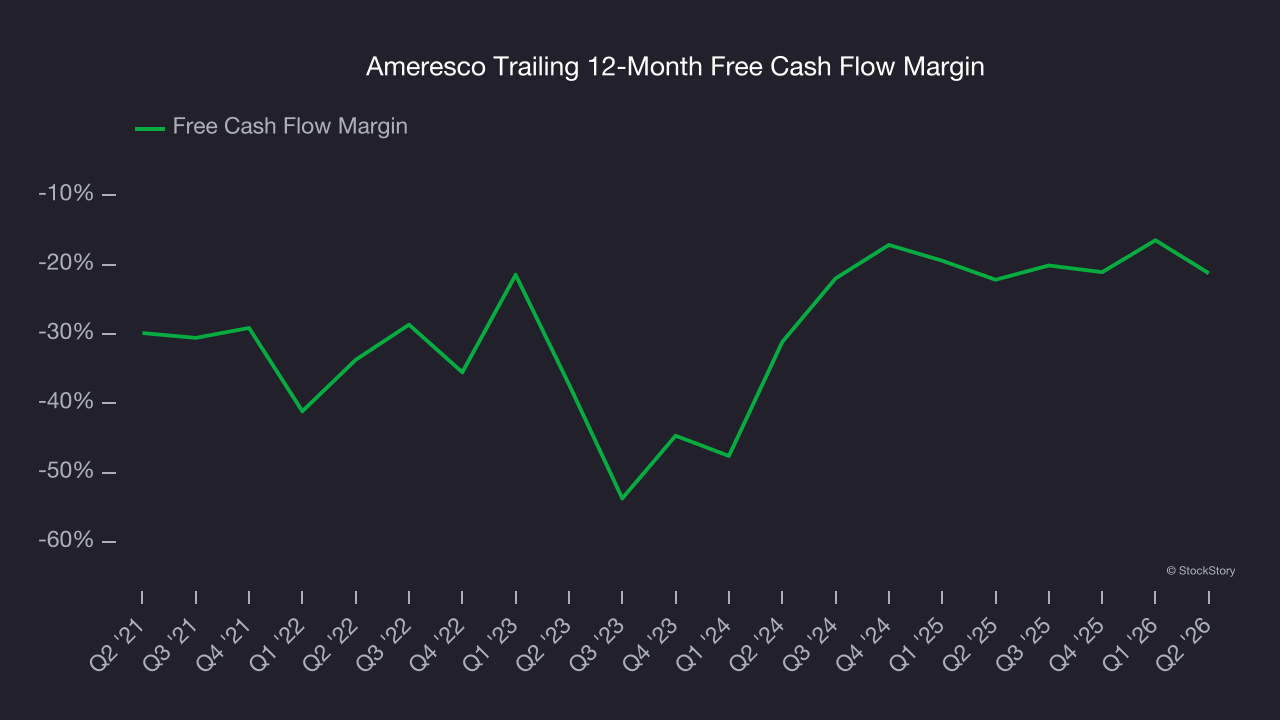
Ameresco’s demanding reinvestments have drained its resources over the last five years, putting it in a pinch and limiting its ability to return capital to investors. Its free cash flow margin averaged negative 28.3%, meaning it lit $28.35 of cash on fire for every $100 in revenue.
3. Short Cash Runway Exposes Shareholders to Potential Dilution
As long-term investors, the risk we care about most is the permanent loss of capital, which can happen when a company goes bankrupt or raises money from a disadvantaged position. This is separate from short-term stock price volatility, something we are much less bothered by.
Ameresco burned through $429.9 million of cash over the last year, and its $2.02 billion of debt exceeds the $138.3 million of cash on its balance sheet. This is a deal breaker for us because indebted loss-making companies spell trouble.
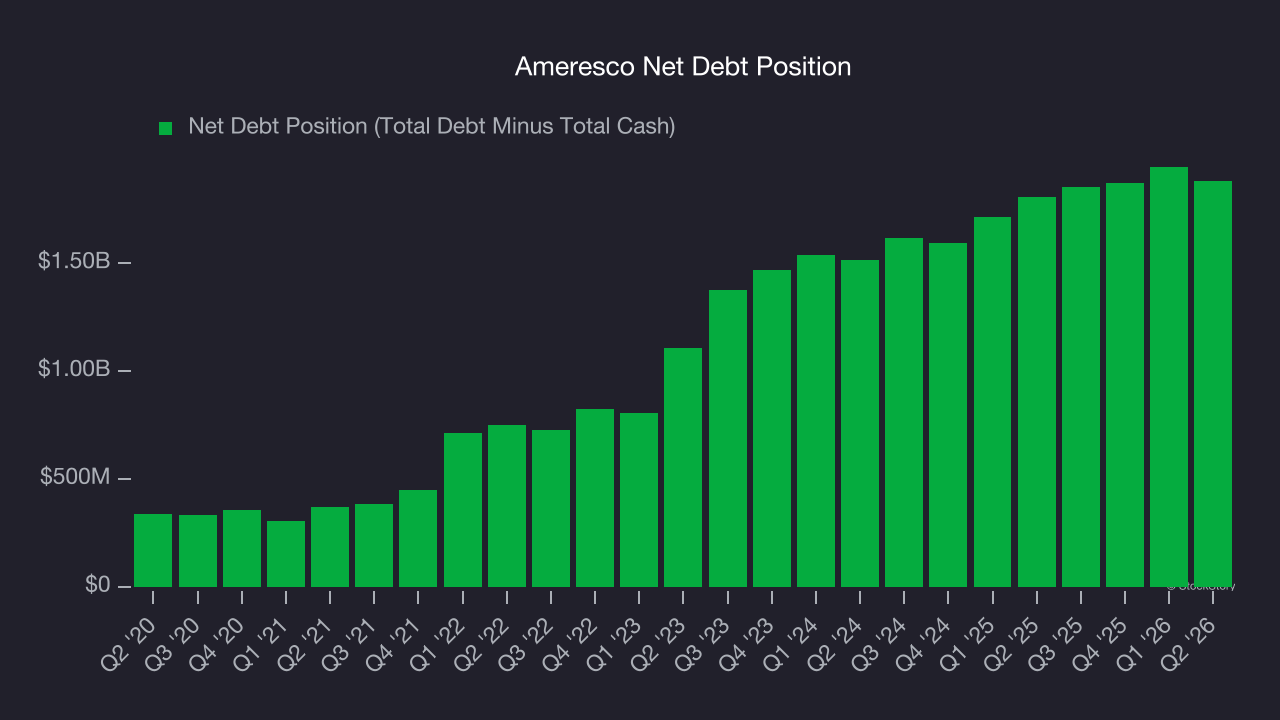
Unless the Ameresco’s fundamentals change quickly, it might find itself in a position where it must raise capital from investors to continue operating. Whether that would be favorable is unclear because dilution is a headwind for shareholder returns.
We remain cautious of Ameresco until it generates consistent free cash flow or any of its announced financing plans materialize on its balance sheet.
Final Judgment
Ameresco isn’t a terrible business, but it isn’t one of our picks. After the recent drawdown, the stock trades at 15.9× forward P/E (or $21.01 per share). While this valuation is reasonable, we don’t really see a big opportunity at the moment. We’re pretty confident there are more exciting stocks to buy at the moment. We’d suggest looking at our favorite semiconductor picks and shovels play.
Stocks We Like More Than Ameresco
ONE MORE THING: Top 5 Growth Stocks. The biggest stock winners almost always had one thing in common before they ran. Revenue growing like crazy. Meta. CrowdStrike. Broadcom. Our AI flagged all three. They returned 315%, 314%, and 455%, respectively.
Find out which 5 stocks it’s flagging this month — FREE. Get Our Top 5 Growth Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-small-cap company Exlservice (+271% between June 2020 and June 2025). Find your next big winner with StockStory today.