Let’s dig into the relative performance of Callaway Golf Company (NYSE: CALY) and its peers as we unravel the now-completed Q2 consumer discretionary - leisure facilities earnings season.
The Consumer Discretionary sector, by definition, is made up of companies selling non-essential goods and services. When economic conditions deteriorate or tastes shift, consumers can easily cut back or eliminate these purchases. For long-term investors with five-year holding periods, this creates a structural challenge: the sector is inherently hit-driven, with low switching costs and fickle customers. As a result, only a handful of companies can reliably grow demand and compound earnings over long periods, which is why our bar is high and High Quality ratings are rare. Leisure facilities companies own and operate theme parks, fitness centers, bowling alleys, and other venue-based entertainment destinations, generating revenue from admissions, memberships, and on-site spending. Tailwinds include consumer preference for experiential spending, tourism recovery, and technology-enhanced guest experiences that support premium pricing. Headwinds are notable: high fixed costs, such as real estate, labor, and maintenance, make profitability highly sensitive to attendance fluctuations during economic slowdowns. Weather, pandemics, and safety incidents can disrupt operations unpredictably. Rising construction and labor costs inflate expansion budgets, while competition from at-home entertainment alternatives and other experiential options limits pricing power in many markets.
The 10 consumer discretionary - leisure facilities stocks we track reported a mixed Q2. As a group, revenues beat analysts’ consensus estimates by 1.4% while next quarter’s revenue guidance was 0.8% below.
Amidst this news, share prices of the companies have had a rough stretch. On average, they are down 11.5% since the latest earnings results.
Callaway Golf Company (NYSE: CALY)
Formed between the merger of Callaway and Topgolf, Callaway Golf Company (NYSE: CALY) sells golf equipment and operates technology-driven golf entertainment venues.
Callaway Golf Company reported revenues of $612.2 million, up 2% year on year. This print exceeded analysts’ expectations by 1.3%. Overall, it was a strong quarter for the company with EBITDA guidance for next quarter exceeding analysts’ expectations and full-year EBITDA guidance exceeding analysts’ expectations.
"We are very pleased with our second quarter results with our revenue growth, gross margin improvement and Adjusted EBITDA all exceeding expectations," commented Chip Brewer, President and Chief Executive Officer of Callaway Golf Company.
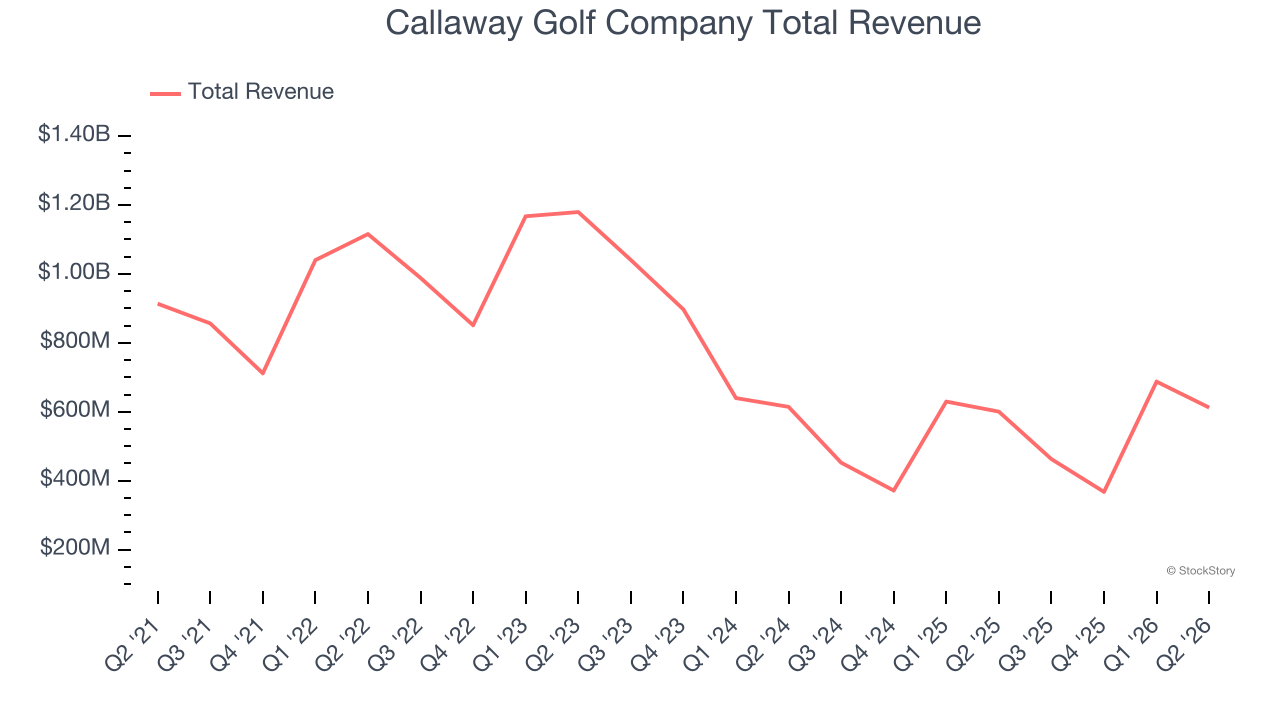
Investor expectations, however, were likely higher than Wall Street’s published projections, leaving some wishing for even better results (analysts’ consensus estimates are those published by big banks and advisory firms, not the investors who make buy and sell decisions). The stock is down 26.7% since reporting and currently trades at $14.35.
Is now the time to buy Callaway Golf Company? Access our full analysis of the earnings results here, it’s free.
Best Q2: Sphere Entertainment (NYSE: SPHR)
Famous for its viral Las Vegas Sphere venue, Sphere Entertainment (NYSE: SPHR) hosts live entertainment events and distributes content across various media platforms.
Sphere Entertainment reported revenues of $313.6 million, up 11% year on year, outperforming analysts’ expectations by 1.8%. The business had an exceptional quarter with a beat of analysts’ EPS estimates and an impressive beat of analysts’ adjusted operating income estimates.
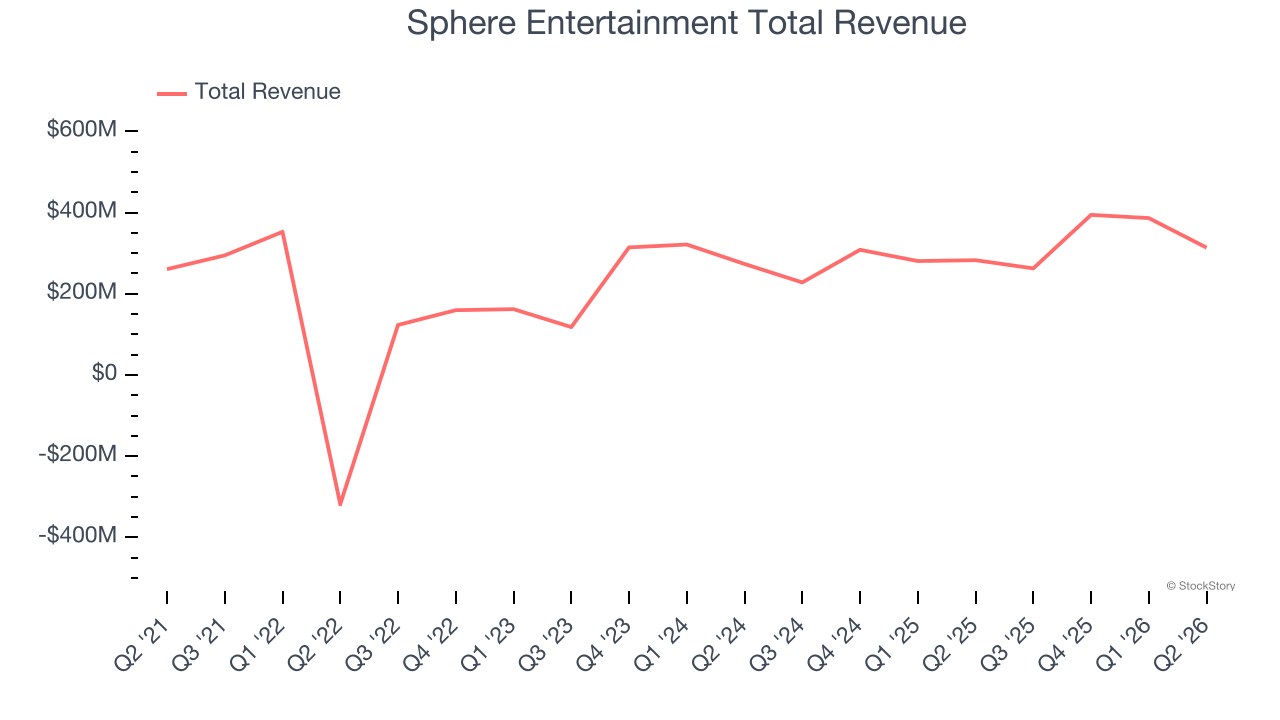
Although it had a fine quarter compared to its peers, the market seems unhappy with the results as the stock is down 24.6% since reporting. It currently trades at $105.65.
Is now the time to buy Sphere Entertainment? Access our full analysis of the earnings results here, it’s free.
Weakest Q2: Xponential Fitness (NYSE: XPOF)
Owner of Club Pilates, Stretch Lab, BFT and Pure Barre, Xponential Fitness (NYSE: XPOF) is a boutique fitness brand offering diverse and specialized exercise experiences.
Xponential Fitness reported revenues of $65.97 million, down 13.4% year on year, exceeding analysts’ expectations by 2.5%. Still, it was a disappointing quarter as it posted full-year revenue guidance missing analysts’ expectations significantly and a significant miss of analysts’ EPS estimates.
Xponential Fitness delivered the slowest revenue growth and weakest full-year guidance update of the whole group. As expected, the stock is down 24.4% since the results and currently trades at $4.81.
Read our full analysis of Xponential Fitness’s results here.
Live Nation (NYSE: LYV)
Owner of Ticketmaster and operator of music festival EDC, Live Nation (NYSE: LYV) is a company specializing in live event promotion, venue management, and ticketing services for concerts and shows.
Live Nation reported revenues of $7.67 billion, up 9.4% year on year. This print beat analysts’ expectations by 1.4%. It was an exceptional quarter as it also logged a beat of analysts’ EPS estimates and a solid beat of analysts’ adjusted operating income estimates.
The stock is down 6.4% since reporting and currently trades at $171.80.
Read our full, actionable report on Live Nation here, it’s free.
Vail Resorts (NYSE: MTN)
Founded by two Aspen, Colorado ski patrol guides, Vail Resorts (NYSE: MTN) is a mountain resort company offering luxury experiences in over 30 locations across the globe.
Vail Resorts reported revenues of $278.1 million, up 2.5% year on year. This result surpassed analysts’ expectations by 1.6%. Aside from that, it was a mixed quarter as it also produced a decent beat of analysts’ EBITDA estimates but full-year EBITDA guidance slightly missing analysts’ expectations.
The stock is up 5.4% since reporting and currently trades at $145.50.
Read our full, actionable report on Vail Resorts here, it’s free.
Market Update
Over the past year, investors have been forced to repeatedly answer the same question: what is the market’s biggest risk? The answer has changed several times, and each shift has reshaped market leadership.
Late in 2025 and early 2026, artificial intelligence became the market’s primary uncertainty. Investors questioned whether AI would erode software pricing power and weaken competitive moats as AI made it easier to replicate once-differentiated products.
By the spring, technology took a back seat to geopolitics. The U.S. conflict with Iran briefly became the market’s dominant narrative, raising concerns about oil prices, inflation, and global growth. But as energy markets remained orderly and fears of a prolonged supply disruption faded, investors quickly turned their focus back to fundamentals.
Want to invest in winners with rock-solid fundamentals? Check out our Top 5 Quality Compounder Stocks and add them to your watchlist. These companies are poised for growth regardless of the political or macroeconomic climate.