Over the past six months, Align Technology’s shares (currently trading at $144.11) have posted a disappointing 13.6% loss, well below the S&P 500’s 17.5% gain. This may have investors wondering how to approach the situation.
Is now the time to buy Align Technology, or should you be careful about including it in your portfolio? Get the full breakdown from our expert analysts, it’s free.
Why Is Align Technology Not Exciting?
Even though the stock has become cheaper, we’re cautious about Align Technology. Here are three reasons you should be careful with ALGN, plus one stock we’d rather own.
1. Long-Term Revenue Growth Disappoints
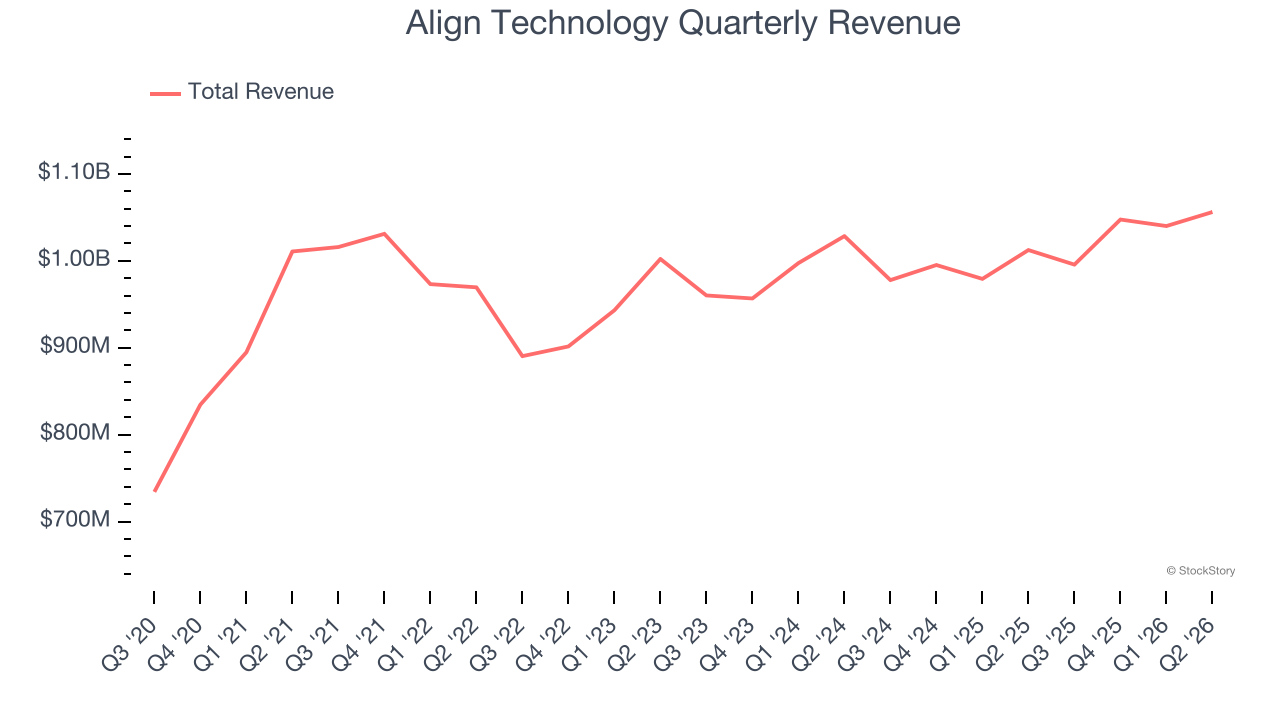
A company’s long-term performance is an indicator of its overall quality. Any business can put up a good quarter or two, but the best consistently grow over the long haul. Regrettably, Align Technology’s sales grew at a tepid 3.6% compounded annual growth rate over the last five years. This fell short of our benchmark for the healthcare sector.
2. EPS Barely Growing
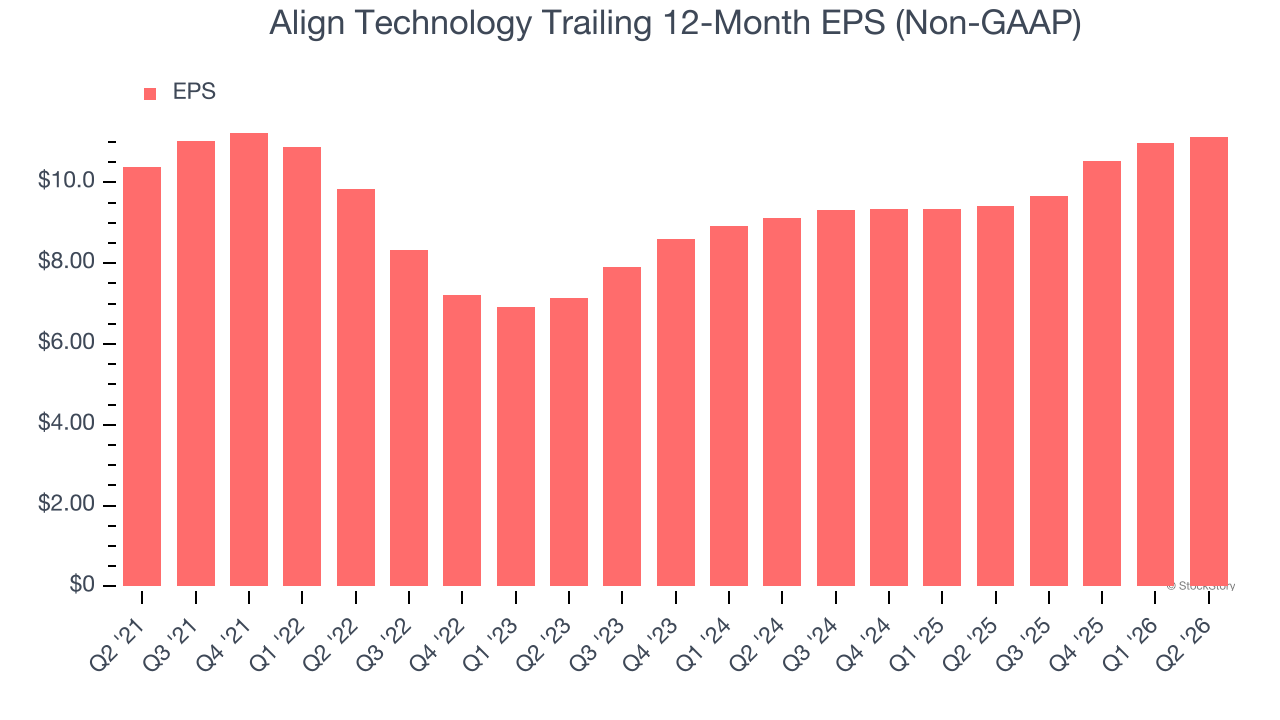
We track the long-term change in earnings per share (EPS) because it highlights whether a company’s growth is profitable.
Align Technology’s EPS grew at an unimpressive 1.4% compounded annual growth rate over the last five years, lower than its 3.6% annualized revenue growth. This tells us the company became less profitable on a per-share basis as it expanded.
3. New Investments Fail to Bear Fruit as ROIC Declines
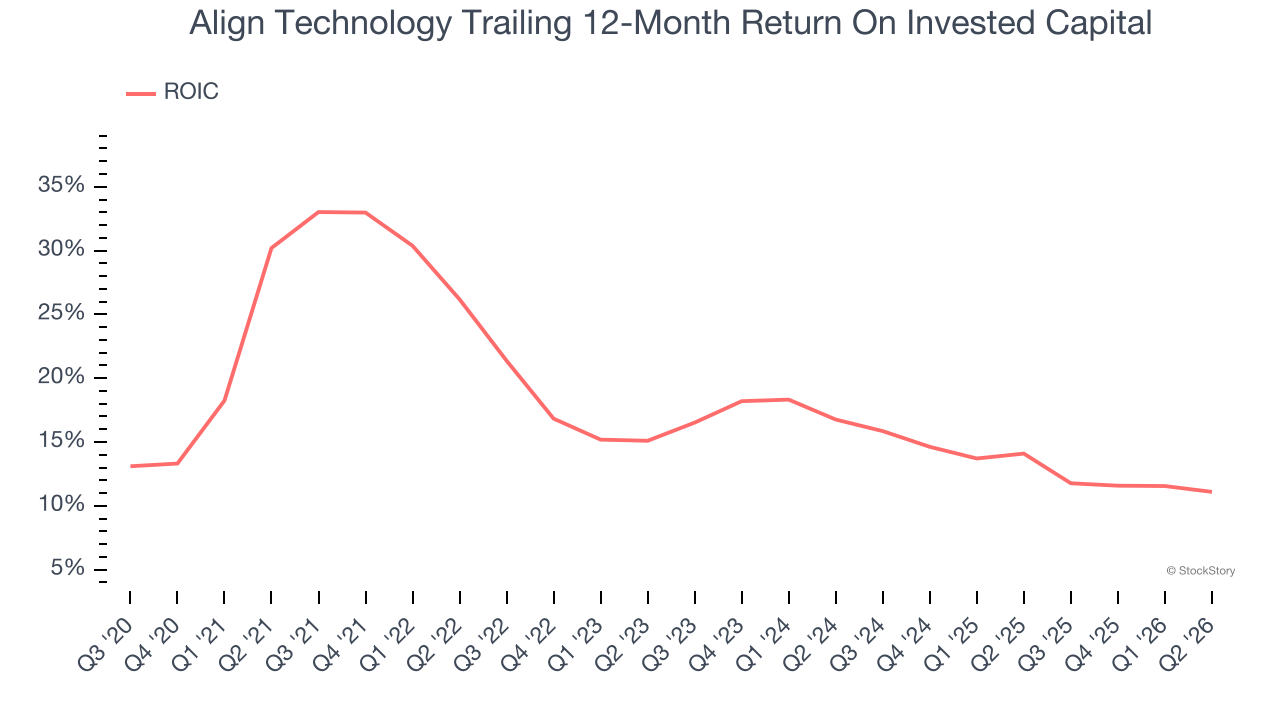
ROIC, or return on invested capital, is a metric showing how much operating profit a company generates relative to the money it has raised (debt and equity).
Unfortunately, Align Technology’s ROIC has decreased over the last few years. We like what management has done in the past, but its declining returns are perhaps a symptom of fewer profitable growth opportunities.
Final Judgment
Align Technology isn’t a terrible business, but it isn’t one of our picks. After the recent drawdown, the stock trades at 11.9× forward P/E (or $144.11 per share). While this valuation is reasonable, we don’t really see a big opportunity at the moment. We’re fairly confident there are better stocks to buy right now. We’d recommend looking at a fast-growing restaurant franchise with an A+ ranch dressing sauce.
Stocks We Would Buy Instead of Align Technology
WHILE YOU’RE HERE: Top 9 Market-Beating Stocks. The best stocks don’t just beat the market once. They do it again. And again. Robust revenue growth, rising free cash flow, returns on capital that leave their competition in the dust. The market has already rewarded these businesses.
But our AI platform says the party isn’t over. Find out which 9 stocks made the cut this week — FREE. Get Our Top 9 Market-Beating Stocks for Free HERE.
Stocks that have made our list include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Kadant (+214% between June 2020 and June 2025). Find your next big winner with StockStory today.