Looking back on household products stocks’ Q2 earnings, we examine this quarter’s best and worst performers, including Procter & Gamble (NYSE: PG) and its peers.
Household products stocks are generally stable investments, as many of the industry's products are essential for a comfortable and functional living space. Recently, there's been a growing emphasis on eco-friendly and sustainable offerings, reflecting the evolving consumer preferences for environmentally conscious options. These trends can be double-edged swords that benefit companies who innovate quickly to take advantage of them and hurt companies that don't invest enough to meet consumers where they want to be with regards to trends.
The 10 household products stocks we track reported a satisfactory Q2. As a group, revenues beat analysts’ consensus estimates by 2.1% while next quarter’s revenue guidance was 1.6% above.
Amidst this news, share prices of the companies have had a rough stretch. On average, they are down 9.1% since the latest earnings results.
Procter & Gamble (NYSE: PG)
Founded by candle maker William Procter and soap maker James Gamble, Procter & Gamble (NYSE: PG) is a consumer products behemoth whose product portfolio spans everything from facial tissues to laundry detergent to feminine care to men’s grooming.
Procter & Gamble reported revenues of $21.2 billion, up 1.5% year on year. This print fell short of analysts’ expectations by 0.8%. Overall, it was a mixed quarter for the company with a decent beat of analysts’ gross margin estimates but full-year EPS guidance meeting analysts’ expectations.
“Fiscal 2026 was a year of foundation building while continuing to grow sales and profit and return high levels of cash to shareowners despite a very challenging geopolitical and economic environment,” said Shailesh Jejurikar, President and Chief Executive Officer.
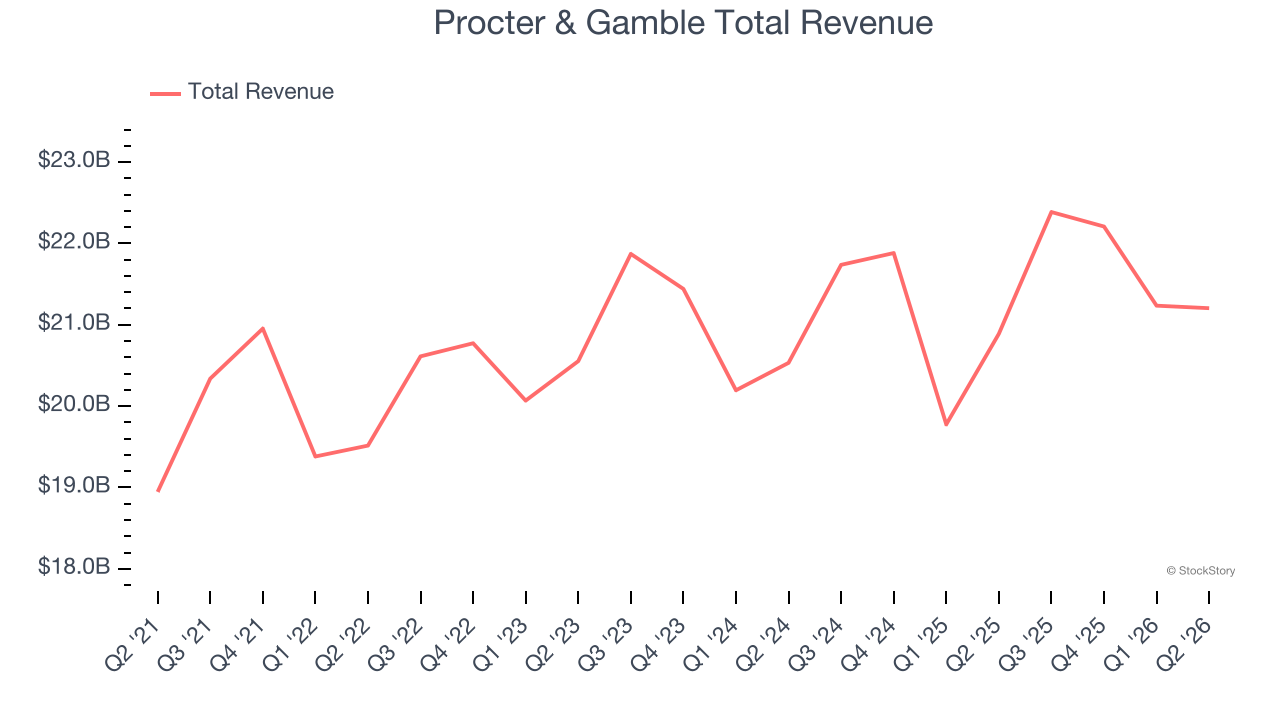
The market seems disappointed with the results as the stock is down 2.9% since reporting and currently trades at $144.60.
Read our full report on Procter & Gamble here, it’s free.
Best Q2: Spectrum Brands (NYSE: SPB)
A leader in multiple consumer product categories, Spectrum Brands (NYSE: SPB) is a diversified company with a portfolio of trusted brands spanning home appliances, garden care, personal care, and pet care.
Spectrum Brands reported revenues of $753.3 million, up 7.7% year on year, outperforming analysts’ expectations by 2.4%. The business had a stunning quarter with a beat of analysts’ EPS estimates and a solid beat of analysts’ EBITDA estimates.
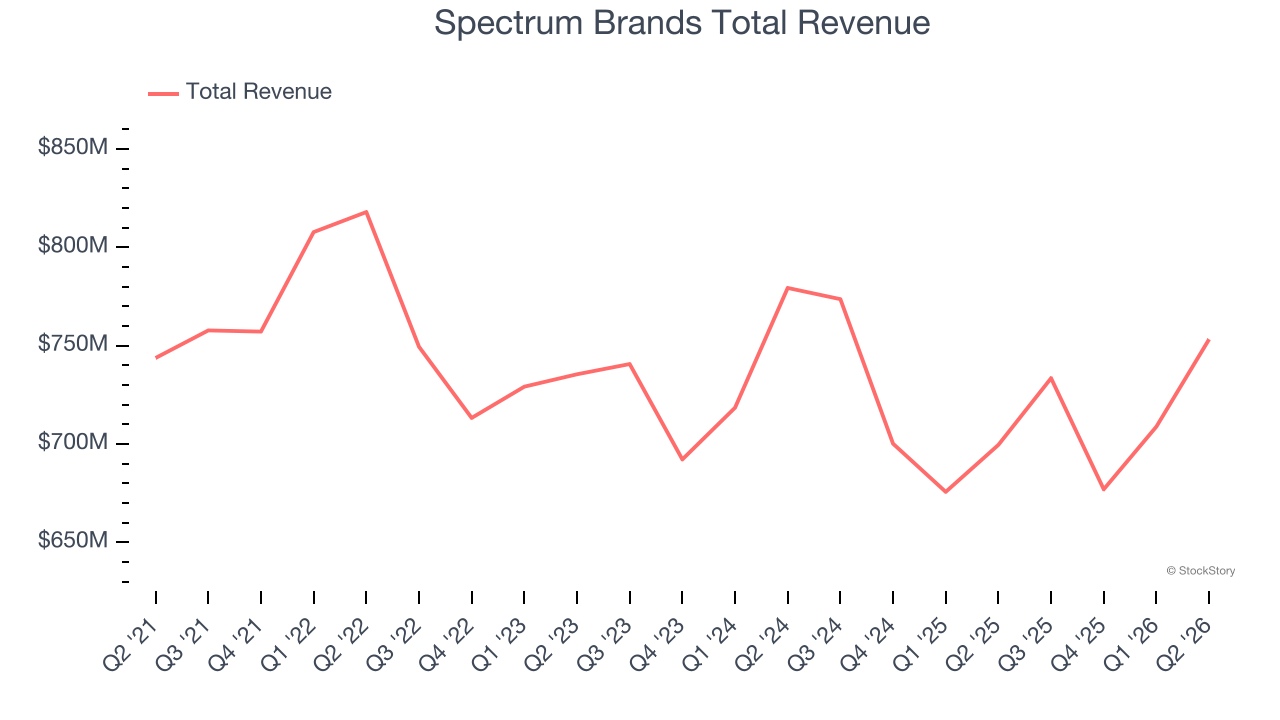
Although it had a fine quarter compared to its peers, the market seems unhappy with the results as the stock is down 11.3% since reporting. It currently trades at $78.29.
Is now the time to buy Spectrum Brands? Access our full analysis of the earnings results here, it’s free.
Slowest Q2: Energizer (NYSE: ENR)
Masterminds behind the viral Energizer Bunny mascot, Energizer (NYSE: ENR) is one of the world's largest manufacturers of batteries.
Energizer reported revenues of $734.1 million, up 1.2% year on year, exceeding analysts’ expectations by 1.2%. Still, it was a slower quarter as it posted a significant miss of analysts’ gross margin estimates and a significant miss of analysts’ EPS estimates.
Interestingly, the stock is up 5.4% since the results and currently trades at $22.26.
Read our full analysis of Energizer’s results here.
WD-40 (NASDAQ: WDFC)
Short for “Water Displacement perfected on the 40th try”, WD-40 (NASDAQ: WDFC) is a renowned American consumer goods company known for its iconic and versatile spray, WD-40 Multi-Use Product.
WD-40 reported revenues of $195.1 million, up 24.3% year on year. This print topped analysts’ expectations by 12.9%. It was an exceptional quarter as it also produced a beat of analysts’ EPS estimates and full-year revenue guidance exceeding analysts’ expectations.
WD-40 pulled off the biggest analyst estimate beat and fastest revenue growth in the group. The stock is down 15.2% since reporting and currently trades at $203.04.
Read our full, actionable report on WD-40 here, it’s free.
Reynolds (NASDAQ: REYN)
Best known for its aluminum foil, Reynolds (NASDAQ: REYN) is a household products company whose products focus on food storage, cooking, and waste.
Reynolds reported revenues of $944 million, flat year on year. This result surpassed analysts’ expectations by 1.1%. Zooming out, it was a satisfactory quarter as it also logged an impressive beat of analysts’ gross margin estimates but full-year EBITDA guidance meeting analysts’ expectations.
The stock is down 15.4% since reporting and currently trades at $21.84.
Read our full, actionable report on Reynolds here, it’s free.
Market Update
Over the past year, investors have been forced to repeatedly answer the same question: what is the market’s biggest risk? The answer has changed several times, and each shift has reshaped market leadership.
Late in 2025 and early 2026, artificial intelligence became the market’s primary uncertainty. Investors questioned whether AI would erode software pricing power and weaken competitive moats as AI made it easier to replicate once-differentiated products.
By the spring, technology took a back seat to geopolitics. The U.S. conflict with Iran briefly became the market’s dominant narrative, raising concerns about oil prices, inflation, and global growth. But as energy markets remained orderly and fears of a prolonged supply disruption faded, investors quickly turned their focus back to fundamentals.
Want to invest in winners with rock-solid fundamentals? Check out our Hidden Gem Stocks and add them to your watchlist. These companies are poised for growth regardless of the political or macroeconomic climate.