Freight delivery company RXO (NYSE: RXO) reported Q3 2026 results beating Wall Street’s revenue expectations, with revenue up 31.7% year on year to $1.87 billion. Its non-GAAP profit of $0.09 per share was 20% above analysts’ consensus estimates.
For more on RXO, read the full research report for free.
RXO (RXO) Q3 2026 highlights:
- Revenue $1.87 billion vs S&P analysts’ consensus estimates of $1.82 billion (31.7% year-on-year growth, 2.6% beat)
- Adjusted EPS $0.09 vs S&P analysts’ consensus estimates of $0.08 (20% beat)
- Adjusted EBITDA $51 million vs analysts’ consensus estimates of $44.32 million (2.7% margin, 15.1% beat)
- Operating margin 0.9%, up from -0.5% in the same quarter last year
- Free cash flow margin 0.6%, similar to the same quarter last year
- Sales volumes rose 2% year on year (1% in the same quarter last year)
- Market capitalization $4.55 billion
Revenue growth
A company’s long-term revenue performance can indicate its overall quality. Any business can report a good quarter or two, but the best consistently grow over the long term. RXO’s revenue grew at a decent 8% compounded annual growth rate over the last five years. Its growth was slightly above the average industrials company and shows its offerings resonate with customers.
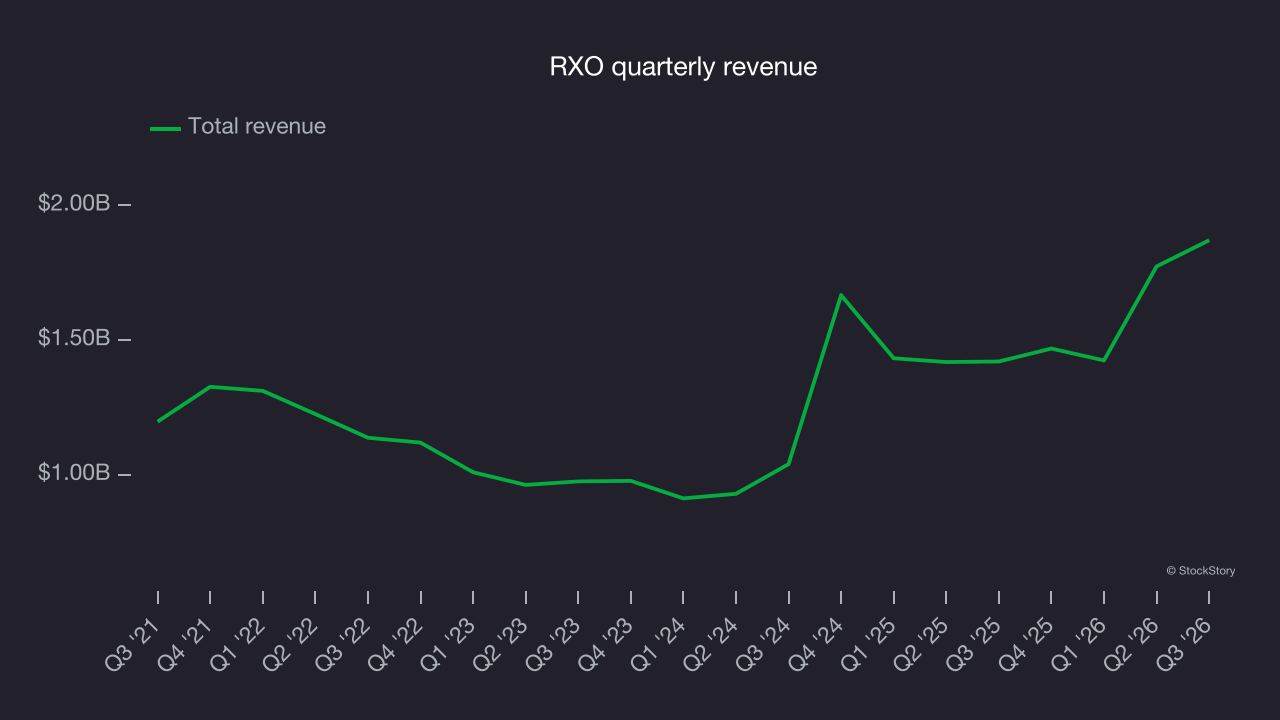
Long-term growth is the most important, but within industrials, a half-decade historical view may miss new industry trends or demand cycles. RXO’s annualized revenue growth of 30.1% over the last two years is above its five-year trend, suggesting its demand recently accelerated. 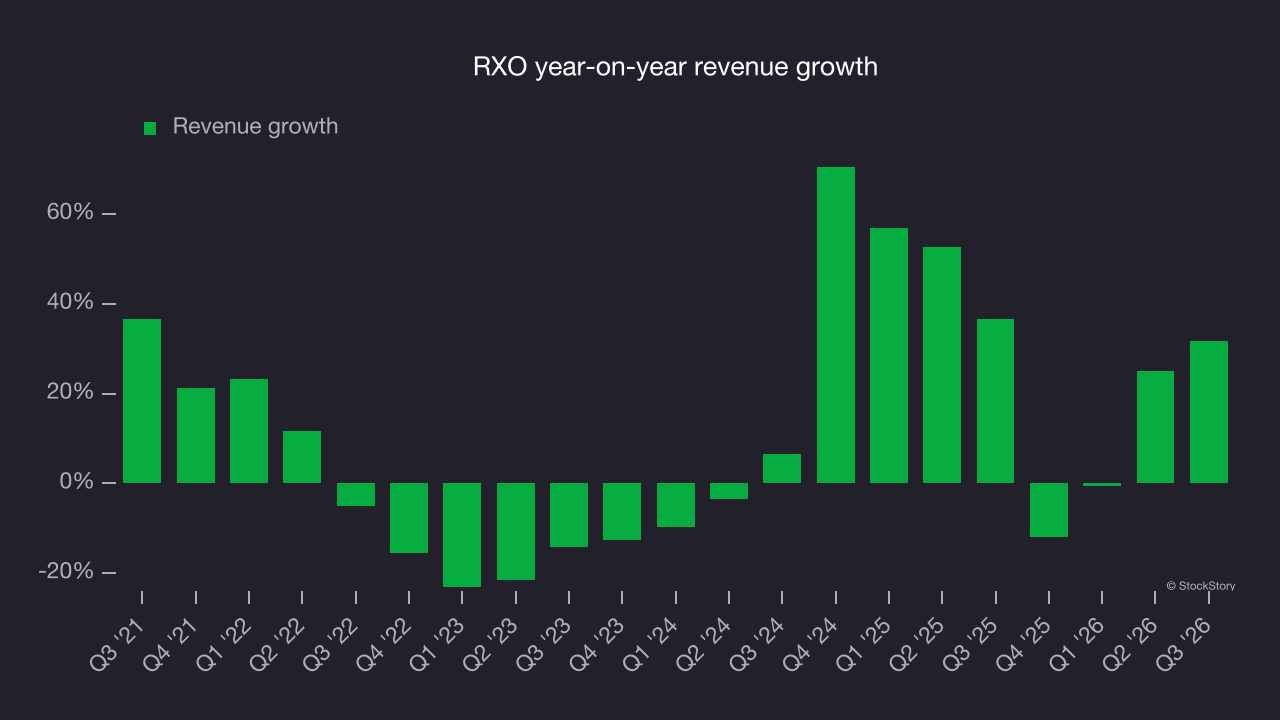
The number of units sold helps explain the company’s revenue dynamics. Over the last two years, RXO’s units sold averaged 1.6% year-on-year declines. Revenue growth outpaced this metric, indicating that price increases contributed to growth. 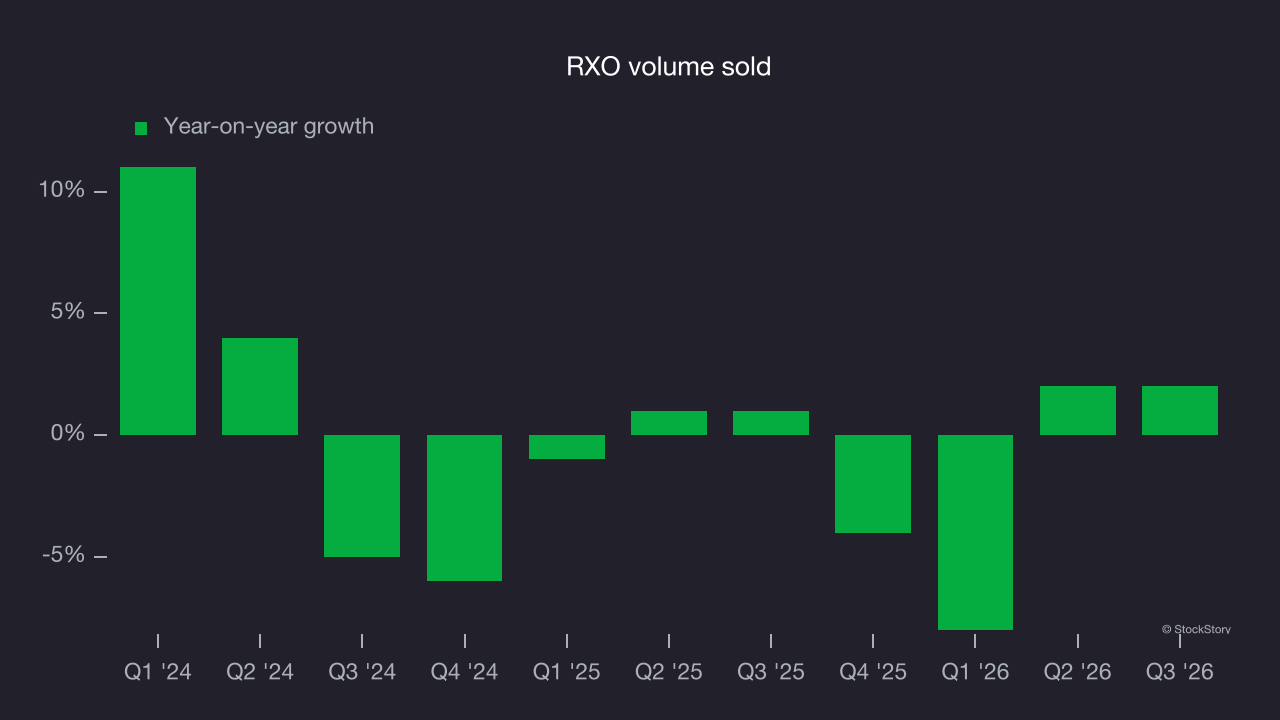
This quarter, RXO reported year-on-year revenue growth of 31.7%, and its $1.87 billion of revenue exceeded Wall Street’s consensus estimates by 2.6%.
Looking ahead, sell-side analysts expect revenue to grow 14.4% over the next 12 months, according to S&P, a deceleration versus the last two years. Despite the slowdown, this projection is strong and indicates the market expects its products and services to perform well.
Operating margin
RXO was roughly breakeven when averaging the last five years of quarterly operating profits, inadequate for an industrials business. That outcome is unsurprising given its low gross margin baseline.
Looking at the trend in its profitability, RXO’s operating margin decreased by 4.4 percentage points over the last five years. This raises questions about the company’s expense base because its revenue growth should have given it leverage on its fixed costs, resulting in better economies of scale and profitability. RXO’s performance was poor, showing that costs were rising and it couldn’t pass them on to its customers.
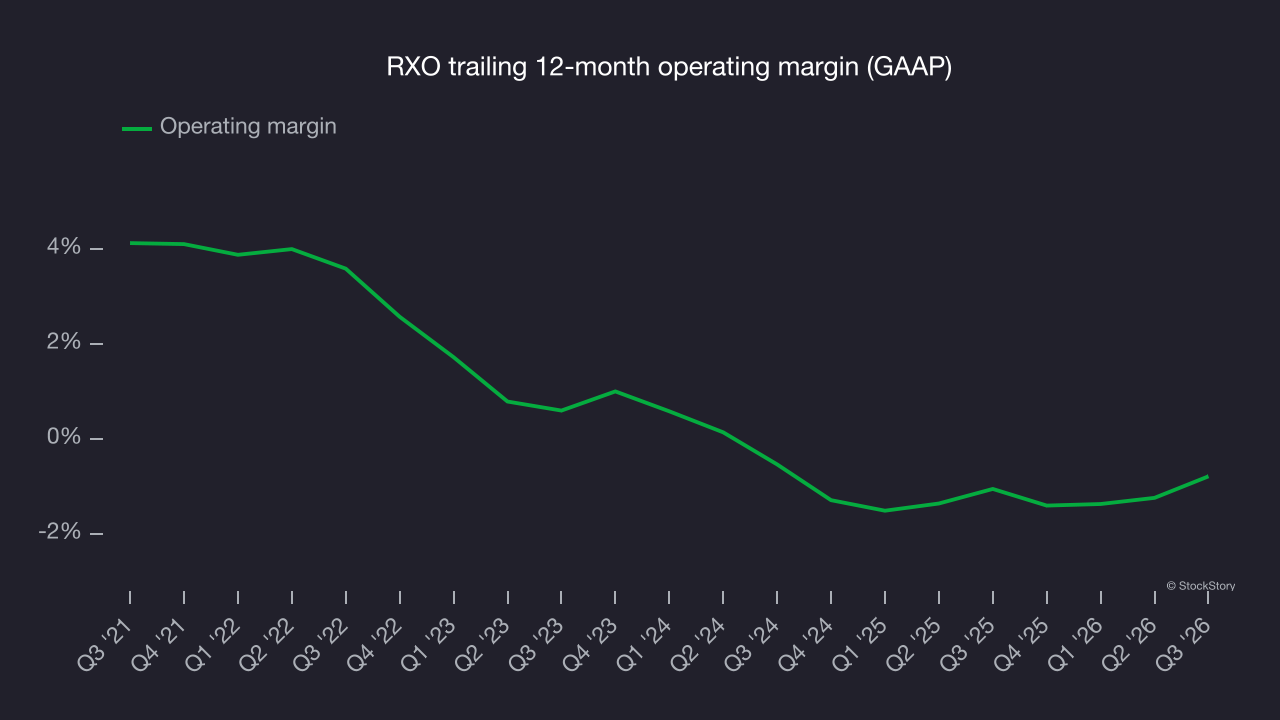
This quarter, RXO’s breakeven margin was 0.9%, up 1.4 percentage points year on year. The increase was a positive sign, and with gross margin declining, it suggests greater efficiency as operating expenses such as marketing, R&D and administrative overhead grew more slowly than revenue.
Earnings per share
Revenue trends explain a company’s historical growth, but the long-term change in earnings per share (EPS) points to the profitability of that growth. For example, a company could inflate its revenue through excessive spending on advertising and promotions.
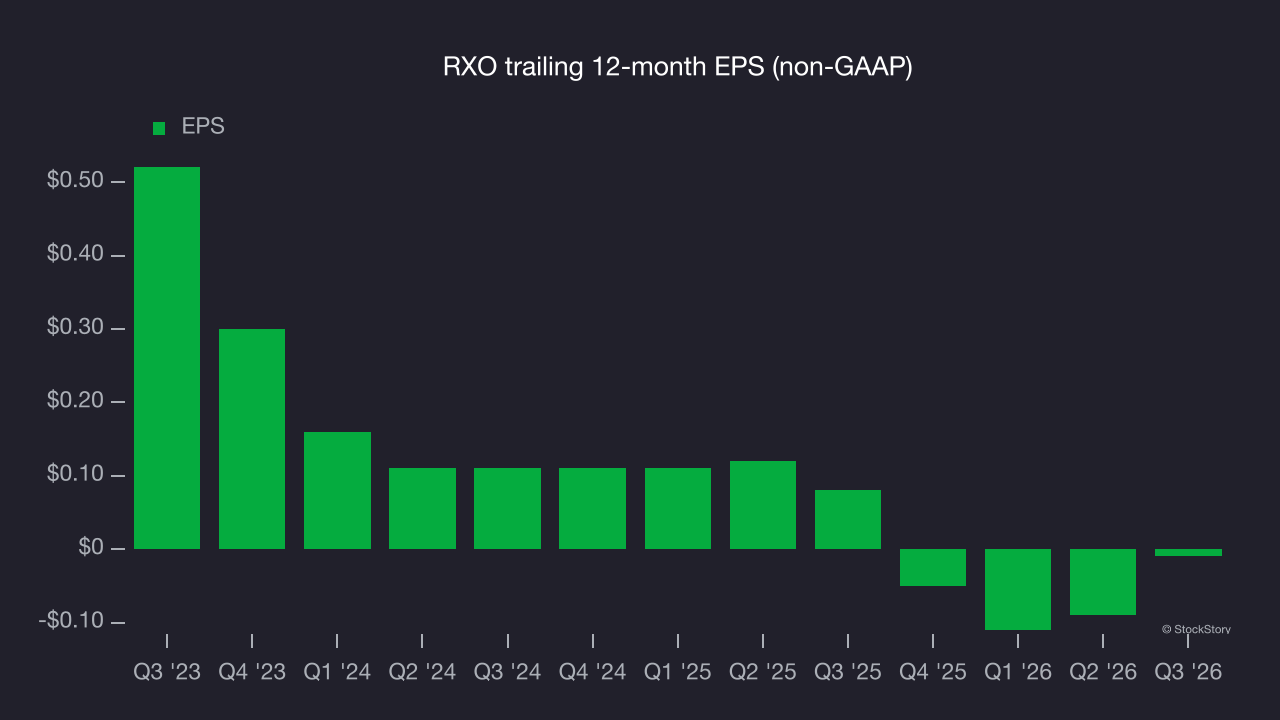
RXO’s full-year EPS turned negative over the last three years. Companies with falling revenue and EPS warrant caution, as diminishing earnings could imply changing secular trends and preferences. If the tide turns unexpectedly, RXO’s low margin of safety could leave its stock price susceptible to large downswings.
As with revenue, examining EPS over a more recent period can provide insight into an emerging theme or development for the business.
RXO’s two-year annual EPS declines of 44.6% show it has continued to underperform. These results were poor regardless of how the data is viewed.
In Q3, RXO reported adjusted EPS of $0.09, up from $0.01 in the same quarter last year. EPS easily cleared analysts’ consensus estimates, a positive result for shareholders. Wall Street expects improvement over the next 12 months. Analysts forecast RXO’s full-year EPS will turn positive, rising from negative $0.01 to positive $0.49, according to S&P.
Key takeaways from RXO’s Q3 results
RXO’s sizable EBITDA beat and EPS above Wall Street’s consensus estimates were key positives this quarter. Shares edged higher 1.3% to $27.95 immediately after the report.
RXO reported solid earnings, but one quarter doesn’t necessarily make the stock a buy. That decision requires considering its valuation, business quality and latest quarterly results. For more on RXO, read our full research report here (it’s free).