Texas-based financial institution Cullen/Frost Bankers (NYSE: CFR) reported Q3 2026 results topping the market’s revenue expectations, with revenue up 10.5% year on year to $626.7 million. Its GAAP profit of $2.84 per share was 1.7% above analysts’ consensus estimates.
For more on Cullen/Frost Bankers, read the full research report, available free.
Cullen/Frost Bankers (CFR) Q3 2026 highlights:
- Net interest income $490.8 million vs analysts’ consensus estimates of $480.6 million (5.8% year-on-year growth, 2.1% beat)
- Net interest margin 3.8% vs analysts’ consensus estimates of 3.8% (in line)
- Revenue $626.7 million vs analysts’ consensus estimates of $608.7 million, according to S&P (10.5% year-on-year growth, 3% beat)
- Efficiency ratio 60.2% vs analysts’ consensus estimates of 60.7% (54.4 basis point beat)
- EPS (GAAP) $2.84 vs analysts’ consensus estimates of $2.79 (1.7% beat)
- Market capitalization $9.76 billion
"During the third quarter, Frost Bankers continued their outstanding execution of our organic growth strategy, and as a result, we saw another quarter of accelerating growth in average loan and deposit volumes," said Cullen/Frost Chairman and CEO Phil Green.
Revenue growth
From lending activities to service fees, most banks build their revenue model around two income sources. Interest rate spreads between loans and deposits create the first stream, with the second coming from charges on everything from basic bank accounts to complex investment banking transactions. Over the last five years, Cullen/Frost Bankers grew its revenue at a decent 11.7% compounded annual growth rate. Its growth was slightly above the average banking company and shows its offerings resonate with customers.
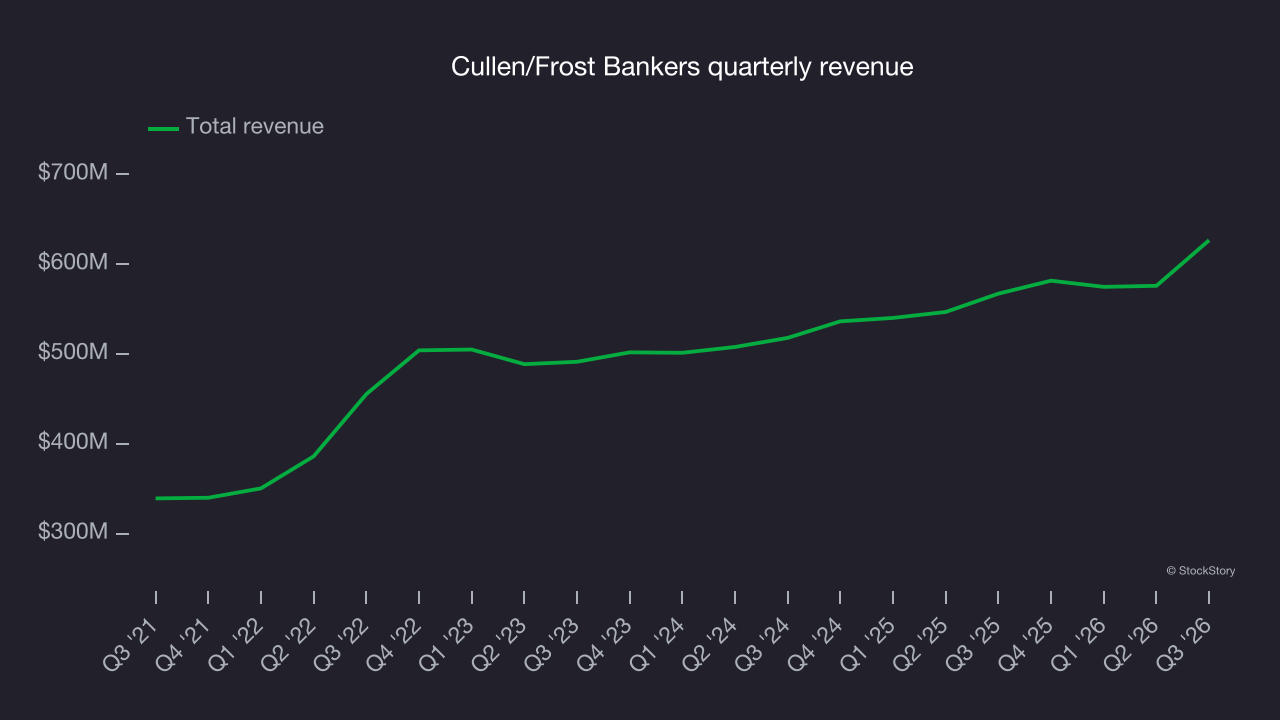
Long-term growth matters the most, but within financials, a half-decade historical view may miss recent interest rate changes, market returns and industry trends. Cullen/Frost Bankers’s recent performance shows its demand has slowed as its annualized revenue growth of 7.8% over the last two years was below its five-year trend. Such slowdowns warrant caution, as they could signal changing consumer preferences in a sector with low switching costs. 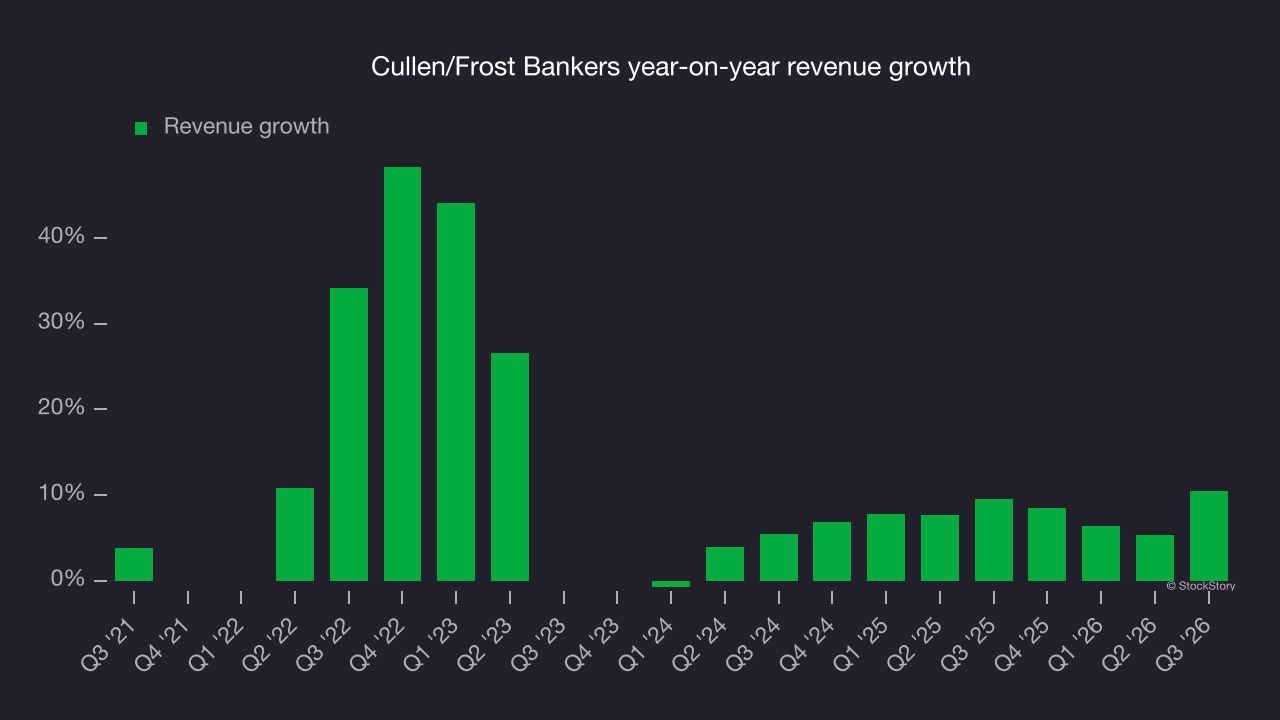 Note: Quarters not shown were determined to be outliers because they were impacted by outsized investment gains/losses that are not indicative of the recurring fundamentals of the business.
This quarter, Cullen/Frost Bankers reported year-on-year revenue growth of 10.5%, and its $626.7 million of revenue exceeded Wall Street’s consensus estimates by 3%.
Net interest income made up 77.6% of the company’s total revenue during the last five years, meaning lending operations are Cullen/Frost Bankers’s largest source of revenue.
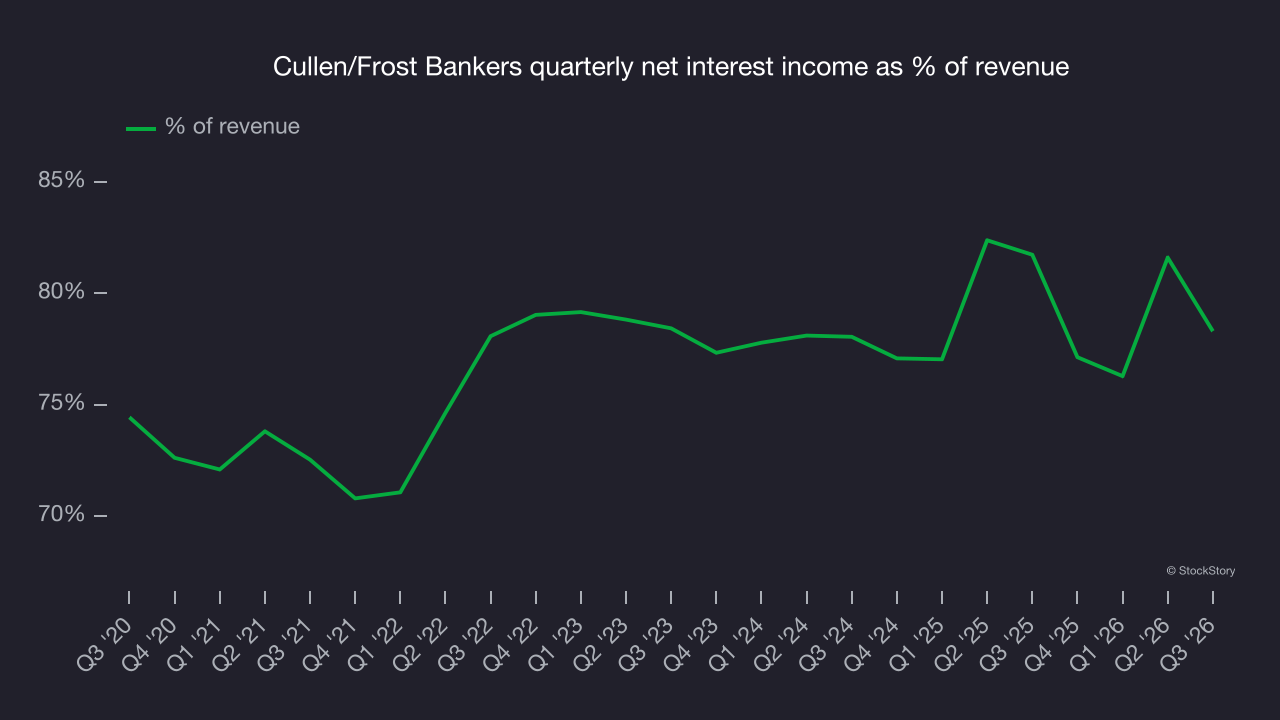
While banks generate revenue from multiple sources, investors view net interest income as the cornerstone – its predictable, recurring characteristics stand in sharp contrast to the volatility of non-interest income.
Key takeaways from Cullen/Frost Bankers’s Q3 results
Revenue and net interest income both topped Wall Street’s consensus estimates, giving Cullen/Frost Bankers’ quarter some key positives. EPS also came in slightly ahead of estimates. Shares remained flat at $157.36 immediately after the results.
Is Cullen/Frost Bankers a buy at its current price? When making that decision, consider its valuation, business quality and the latest quarter. For more on these factors, read our full research report here (it’s free).