Food and beverage supplier MGP Ingredients (NASDAQ: MGPI) missed Wall Street’s revenue expectations in Q3 2026, with revenue falling 9.9% year on year to $117.9 million. On the other hand, the company’s full-year revenue guidance of $490 million at the midpoint came in 1.2% above analysts’ consensus estimates. Its non-GAAP profit of $0.39 per share was 21.1% above analysts’ consensus estimates.
For more on MGP Ingredients, read our free full research report.
MGP Ingredients (MGPI) Q3 2026 highlights:
- Revenue $117.9 million vs S&P analysts’ consensus estimates of $120.6 million (9.9% year-on-year decline, 2.2% miss)
- Adjusted EPS $0.39 vs S&P analysts’ consensus estimates of $0.32 (21.1% beat)
- Adjusted EBITDA $21.49 million vs analysts’ consensus estimates of $21.89 million (18.2% margin, 1.8% miss)
- Revenue guidance The company reconfirmed its revenue guidance for the full year of $490 million at the midpoint
- Adjusted EPS guidance Management reiterated its full-year adjusted EPS guidance of $1.65 at the midpoint
- EBITDA guidance $94 million at the midpoint for the full year, above analysts’ consensus estimates of $91.88 million
- Operating margin 10.2%, down from 16.1% in the same quarter last year
- Free cash flow margin 23.1%, up from 21.1% in the same quarter last year
- Market capitalization $328.1 million
“Our third quarter results show that we are doing what we said we would do. Our cash flow from operations was $32 million during the quarter, and adjusted EBITDA, adjusted basic EPS and ending net leverage each came in better than our expectations. As a result, we are reaffirming guidance,” said Julie Francis, president and CEO. “In Branded Spirits, Penelope Bourbon sales grew 12% and our mid-priced brands grew 6%. Distilling Solutions continued to navigate an oversupplied market and Ingredient Solutions grew sales by 5%. As we become Sempreon on November 2, our focus remains on executing our strategic roadmap in each of our three businesses, supported by our financial discipline and our strong right to win.”
Revenue growth
A company’s long-term revenue performance is one signal of its overall quality. Even a poor business can perform well for one or two quarters, but a top-tier one grows for years.
With $487 million in revenue over the past 12 months, MGP Ingredients is a small consumer staples company, which sometimes brings disadvantages compared to larger competitors benefiting from economies of scale and negotiating leverage with retailers.
MGP Ingredients struggled to generate demand over the last three years. Its revenue dropped by 15.7% annually.
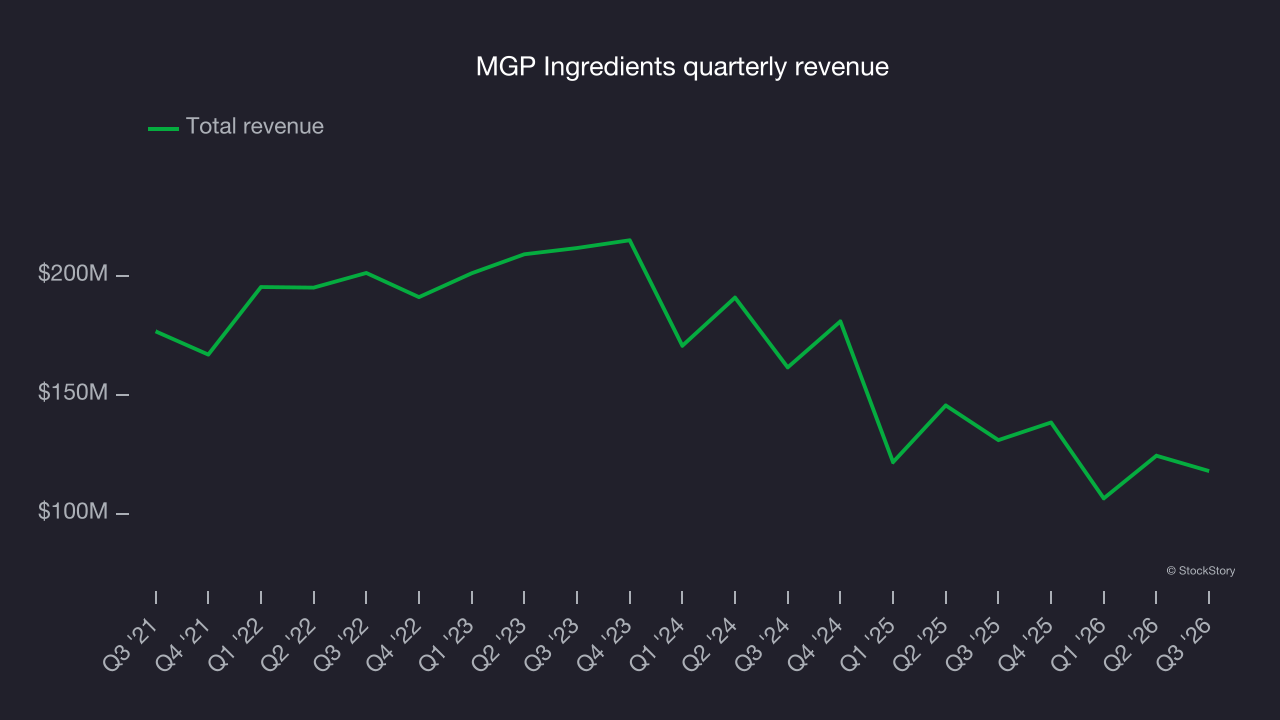
This quarter, MGP Ingredients missed Wall Street’s consensus estimates and reported an uninspiring 9.9% year-on-year revenue decline, generating $117.9 million in revenue.
Looking ahead, sell-side analysts expect revenue to grow 2.5% over the next 12 months, according to S&P. Although this projection implies its newer products will fuel better top-line performance, it is still below average for the sector.
Cash flow
Earnings are valuable for assessing company performance, but cash matters because accounting profits alone can’t pay the bills.
MGP Ingredients has shown decent cash profitability, giving it some flexibility to reinvest or return capital to investors. The company’s free cash flow margin averaged 5.9% over the last two years, slightly better than the broader consumer staples sector.
MGP Ingredients’s margin dropped by 10.6 percentage points over the last year. Continued declines could signal it is in the middle of an investment cycle.
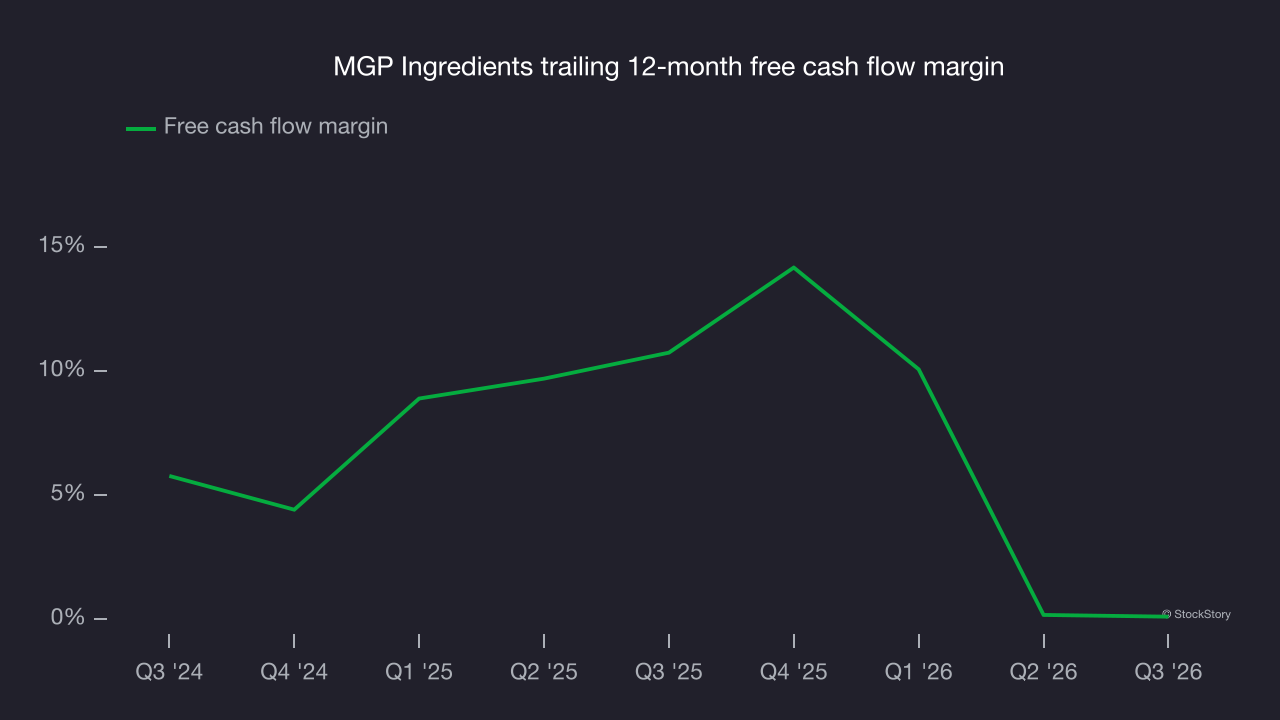
MGP Ingredients’s free cash flow totaled $27.21 million in Q3, equivalent to a 23.1% margin. This was a good result, with its margin 2 percentage points higher than in the same quarter last year, but short-term results warrant caution because investment needs can be seasonal, leading to temporary swings. Long-term trends carry greater meaning.
Key takeaways from MGP Ingredients’s Q3 results
MGP Ingredients delivered a mixed quarter, with an EPS beat and slightly above-consensus full-year revenue guidance offset by shortfalls in revenue and EBITDA versus Wall Street’s consensus estimates. Shares remained flat at $15.33 immediately after the results.
When deciding whether to invest in MGP Ingredients, the latest quarter matters, but longer-term business quality and valuation matter more. For more on these factors, read the full research report here (it’s free).