Sustainable ingredients producer Darling Ingredients (NYSE: DAR) fell short of the market’s revenue expectations in Q3 2026, but revenue rose 14.5% year on year to $1.79 billion. Its GAAP profit of $1.67 per share was 3.3% below analysts’ consensus estimates.
For more on Darling Ingredients, read our free full research report.
Darling Ingredients (DAR) Q3 2026 highlights:
- Revenue $1.79 billion vs S&P analysts’ consensus estimates of $1.80 billion (14.5% year-on-year growth, 0.8% miss)
- EPS (GAAP) $1.67 vs analysts’ consensus estimates of $1.73 (3.3% miss)
- Operating margin 18.6%, up from 4.6% in the same quarter last year
- Market capitalization $8.78 billion
“Our core business delivered another quarter of exceptional performance, demonstrating its resilience and strong cash flow generation,” said Randall C. Stuewe, Chairman and Chief Executive Officer. “This financial strength, bolstered by substantial cash from Diamond Green Diesel, enabled us to realize a $420 million reduction in net debt and return capital to our shareholders. With a strong balance sheet and a great outlook, the momentum is undeniable as we position the company for a successful 2027.”
Revenue growth
Examining a company’s long-term performance can provide clues about its quality. Any business can have short-term success, but a top-tier one grows for years.
With $6.78 billion in revenue over the past 12 months, Darling Ingredients is one of the larger consumer staples companies and benefits from a well-known brand that influences purchasing decisions. However, its scale is a double-edged sword because there are only a finite number of major retail partners, placing a ceiling on its growth. For Darling Ingredients to boost its revenue, it likely needs to adjust its prices, launch new offerings or expand in foreign markets.
Darling Ingredients struggled to increase demand as its $6.78 billion in revenue for the trailing 12 months was close to its revenue three years ago. This shows demand was soft.
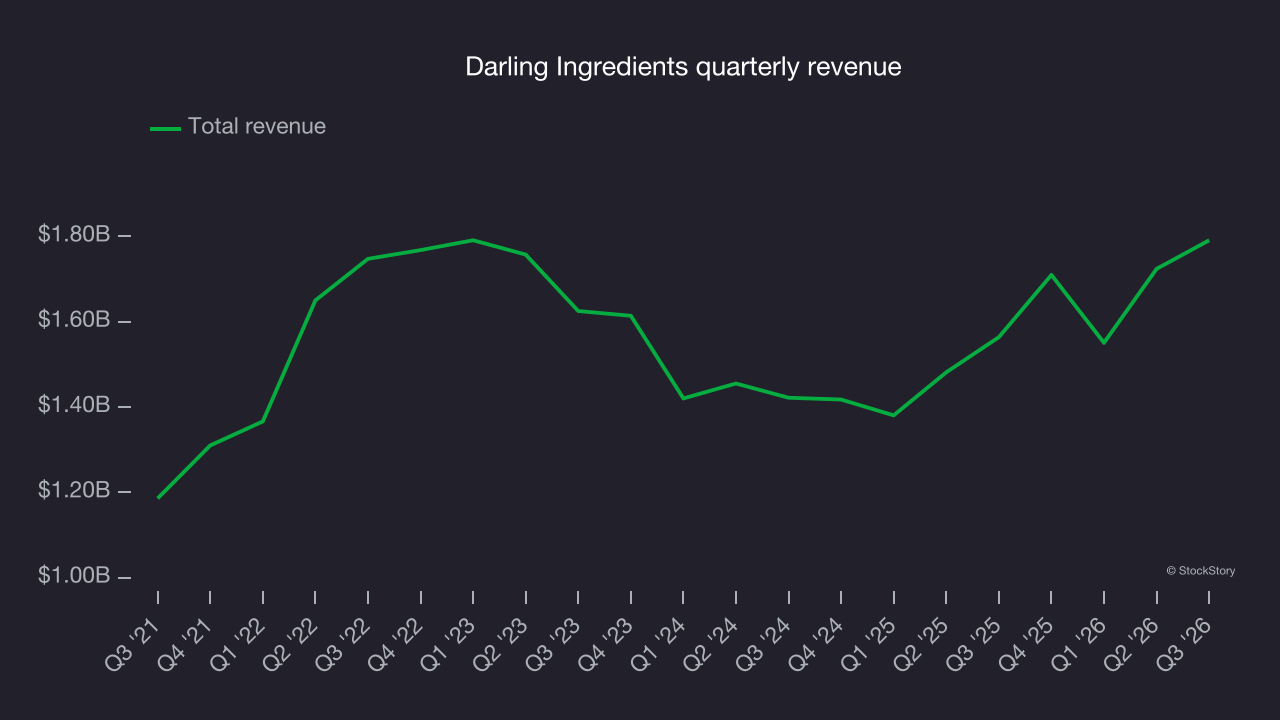
This quarter, Darling Ingredients’s revenue grew by 14.5% year on year to $1.79 billion but fell short of Wall Street’s consensus estimates.
Looking ahead, sell-side analysts expect revenue to grow 6.4% over the next 12 months, according to S&P, an acceleration versus the last three years. This projection is above the sector average and implies its newer products will spur better top-line performance.
Cash flow
Earnings are valuable for assessing company performance, but cash matters more because accounting profits can’t pay the bills.
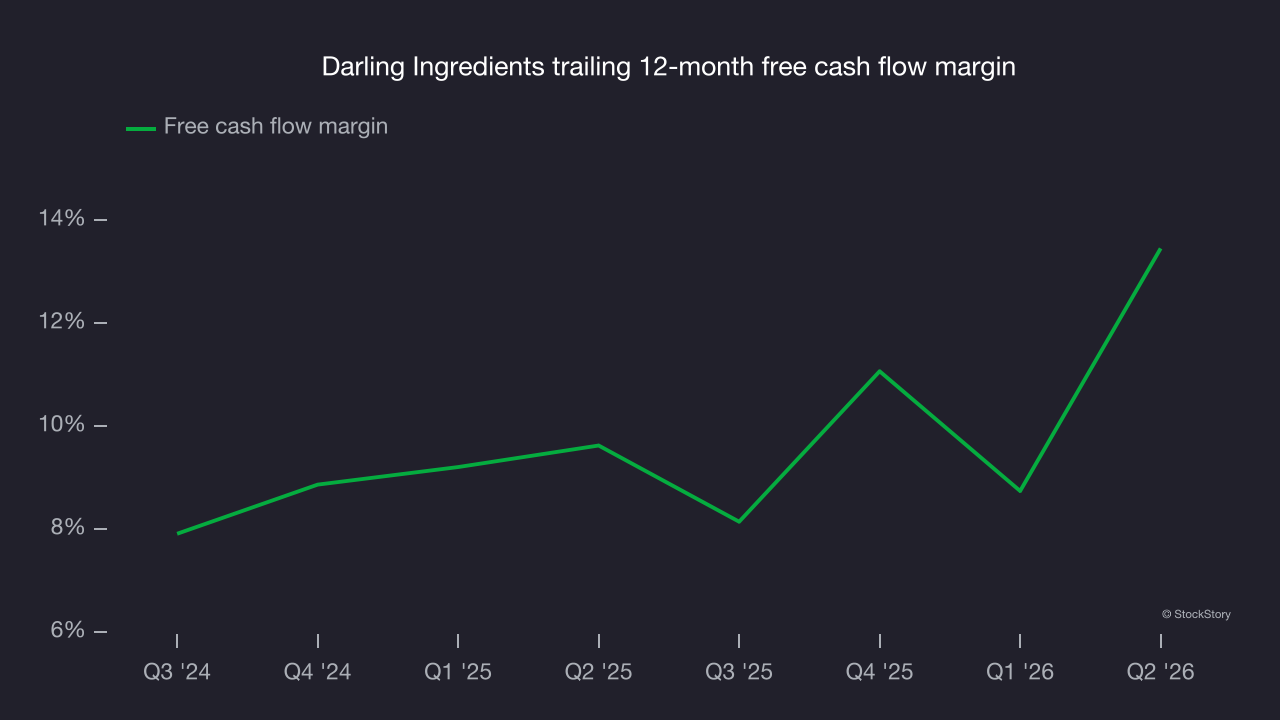
Darling Ingredients has shown strong cash profitability, giving it an edge over its competitors and the ability to reinvest or return capital to investors. The company’s free cash flow margin averaged 11.3% over the last two years, impressive for a consumer staples business.
Key takeaways from Darling Ingredients’s Q3 results
Revenue and gross margin both fell short of Wall Street’s consensus estimates, leaving few positives in Darling Ingredients’s Q3 results. The quarter could have been better. Shares edged lower 1.6% to $54.56 immediately after the release.
Darling Ingredients underperformed this quarter. Assessing whether that creates an investment opportunity requires a longer-term view. The latest quarter matters, but not as much as longer-term business quality and valuation, when deciding whether to invest in this stock. For more on Darling Ingredients, read the full research report here (it’s free).