Homebuilding company PulteGroup (NYSE: PHM) fell short of the market’s revenue expectations in Q3 2026, with sales falling 9.8% year on year to $3.97 billion. Its GAAP profit of $2.53 per share was 3.4% below analysts’ consensus estimates.
Is now the time to buy PulteGroup? Find out by accessing our full research report, it’s free.
PulteGroup (PHM) Q3 2026 highlights:
- Revenue: $3.97 billion vs analyst estimates of $4.15 billion (9.8% year-on-year decline, 4.2% miss)
- EPS (GAAP): $2.53 vs analyst expectations of $2.62 (3.4% miss)
- Operating Margin: 15.7%, down from 17.3% in the same quarter last year
- Free Cash Flow Margin: 9.8%, down from 14.8% in the same quarter last year
- Backlog: $6.44 billion at quarter end, up 3.4% year on year
- Market Capitalization: $21.16 billion
“With homebuying demand increasingly pressured by rising mortgage rates, widespread inflation, and global unrest, we continue to benefit from our diversified operating platform and consistent strategies for delivering superior returns over the housing cycle,” said PulteGroup President and CEO, Ryan Marshall. “With more than 60% of our business now comprised of more profitable move-up and active-adult homebuyers, our strong gross margins were instrumental to driving third quarter earnings of $2.53 per share."
Company overview
Having delivered over 850,000 homes since its founding in 1950, PulteGroup (NYSE: PHM) is one of America's largest homebuilders, constructing single-family homes, townhouses, and condominiums for first-time, move-up, and active adult buyers across 46 markets in 25 states.
Revenue growth
A company’s long-term sales performance can indicate its overall quality. Even a bad business can shine for one or two quarters, but a top-tier one grows for years. Regrettably, PulteGroup’s sales grew at a tepid 4.9% compounded annual growth rate over the last five years. This was below our standard for the industrials sector and is a poor baseline for our analysis.
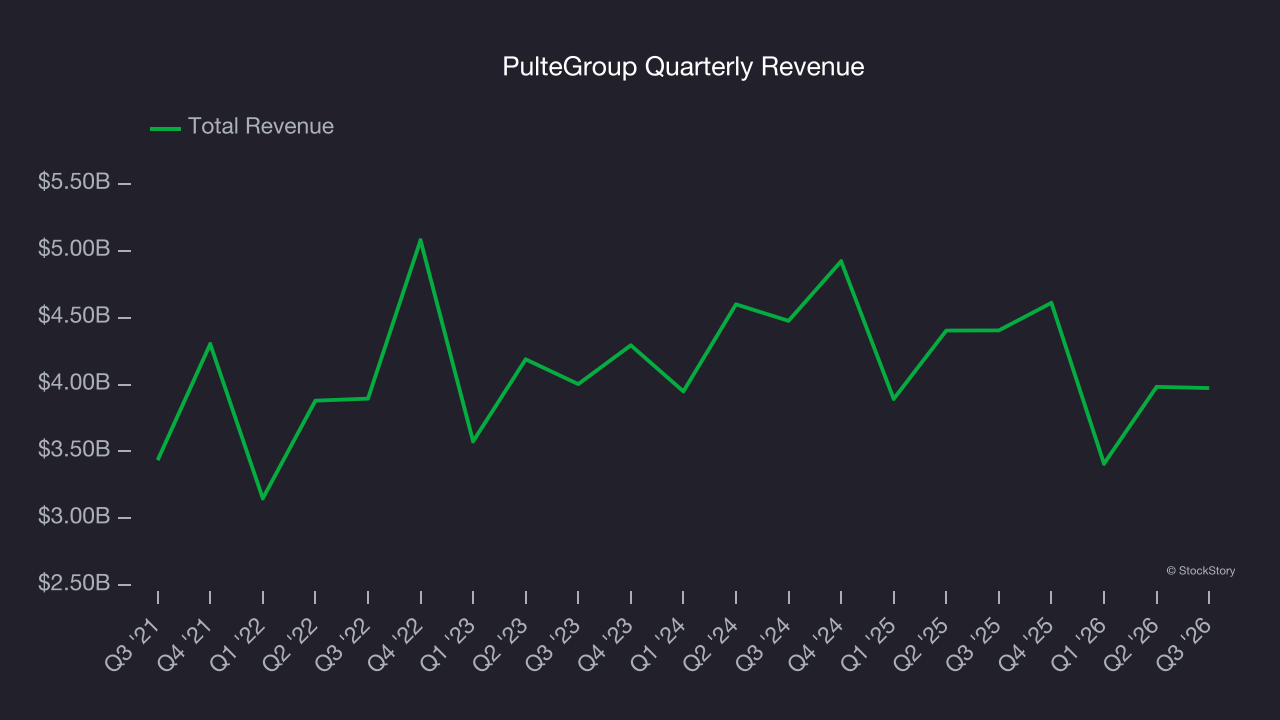
We at StockStory place the most emphasis on long-term growth, but within industrials, a half-decade historical view may miss cycles, industry trends, or a company capitalizing on catalysts such as a new contract win or a successful product line. PulteGroup’s performance shows it grew in the past but relinquished its gains over the last two years, as its revenue fell by 4% annually. PulteGroup isn’t alone in its struggles as the home builders industry experienced a cyclical downturn, with many similar businesses observing lower sales at this time. 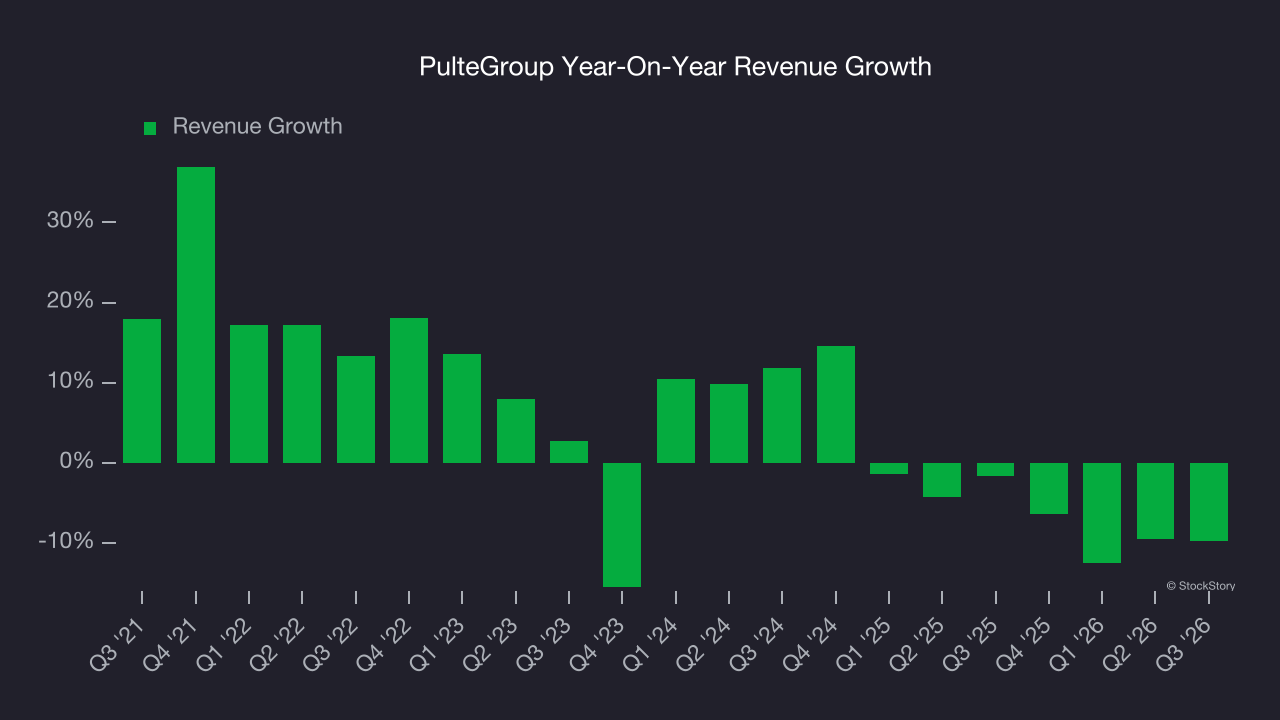
This quarter, PulteGroup missed Wall Street’s estimates and reported a rather uninspiring 9.8% year-on-year revenue decline, generating $3.97 billion of revenue.
Looking ahead, sell-side analysts expect revenue to grow 3.5% over the next 12 months. While this projection implies its newer products and services will catalyze better top-line performance, it is still below average for the sector.
ONE MORE THING: 3 Hidden Platforms Growing 3X Faster than Amazon, Google, and PayPal. Amazon, Google, and Meta all followed the same playbook: Dominate an ignored market. Build an unbeatable moat. Scale until you’re unstoppable.
These three platforms are running that exact playbook right now. The early investors in Amazon made fortunes. The early investors in these could do the same. Get All 3 Stocks Here for FREE.
Operating margin
Operating margin is one of the best measures of profitability because it tells us how much money a company takes home after procuring and manufacturing its products, marketing and selling those products, and most importantly, keeping them relevant through research and development.
PulteGroup has been a well-oiled machine over the last five years. It demonstrated elite profitability for an industrials business, boasting an average operating margin of 19.6%. This result was particularly impressive because of its low gross margin, which is mostly a factor of what it sells and takes huge shifts to move meaningfully. Companies have more control over their operating margins, and it’s a show of well-managed operations if they’re high when gross margins are low.
Analyzing the trend in its profitability, PulteGroup’s operating margin decreased by 5.5 percentage points over the last five years. Many home builders companies also saw their margins fall (along with revenue, as mentioned above) because the cycle turned in the wrong direction. We hope PulteGroup can emerge from this a stronger company, as the silver lining of a downturn is that market share can be won and efficiencies found.
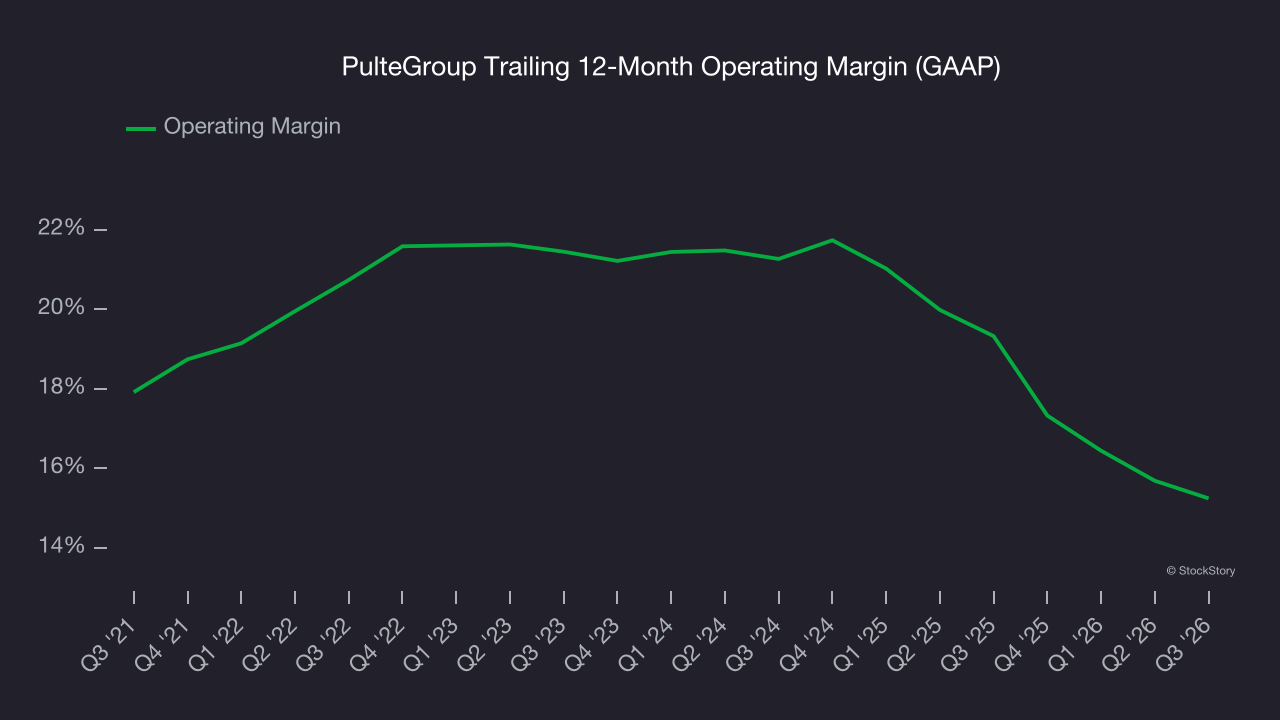
This quarter, PulteGroup generated an operating margin profit margin of 15.7%, down 1.6 percentage points year on year. Since PulteGroup’s operating margin decreased more than its gross margin, we can assume it was less efficient because expenses such as marketing, R&D, and administrative overhead increased.
Earnings per share
Revenue trends explain a company’s historical growth, but the long-term change in earnings per share (EPS) points to the profitability of that growth — for example, a company could inflate its sales through excessive spending on advertising and promotions.
PulteGroup’s EPS grew at 7.5% compounded annual growth rate over the last five years. This performance was better than its revenue growth but doesn’t tell us much about its business quality because its operating margin improvement was less than peers.
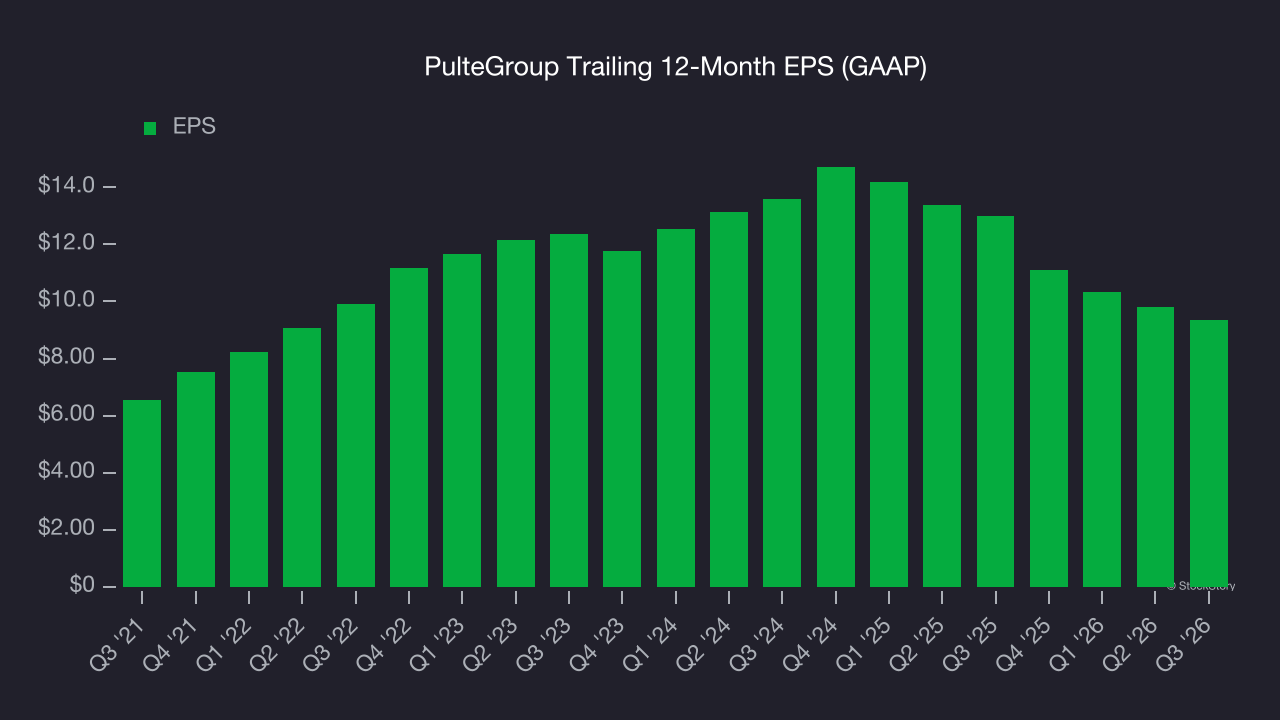
We can take a deeper look into PulteGroup’s earnings to better understand the drivers of its performance. A five-year view shows that PulteGroup has repurchased its stock, shrinking its share count by 27.4%. This tells us its EPS outperformed its revenue not because of increased operational efficiency but financial engineering, as buybacks boost per share earnings. 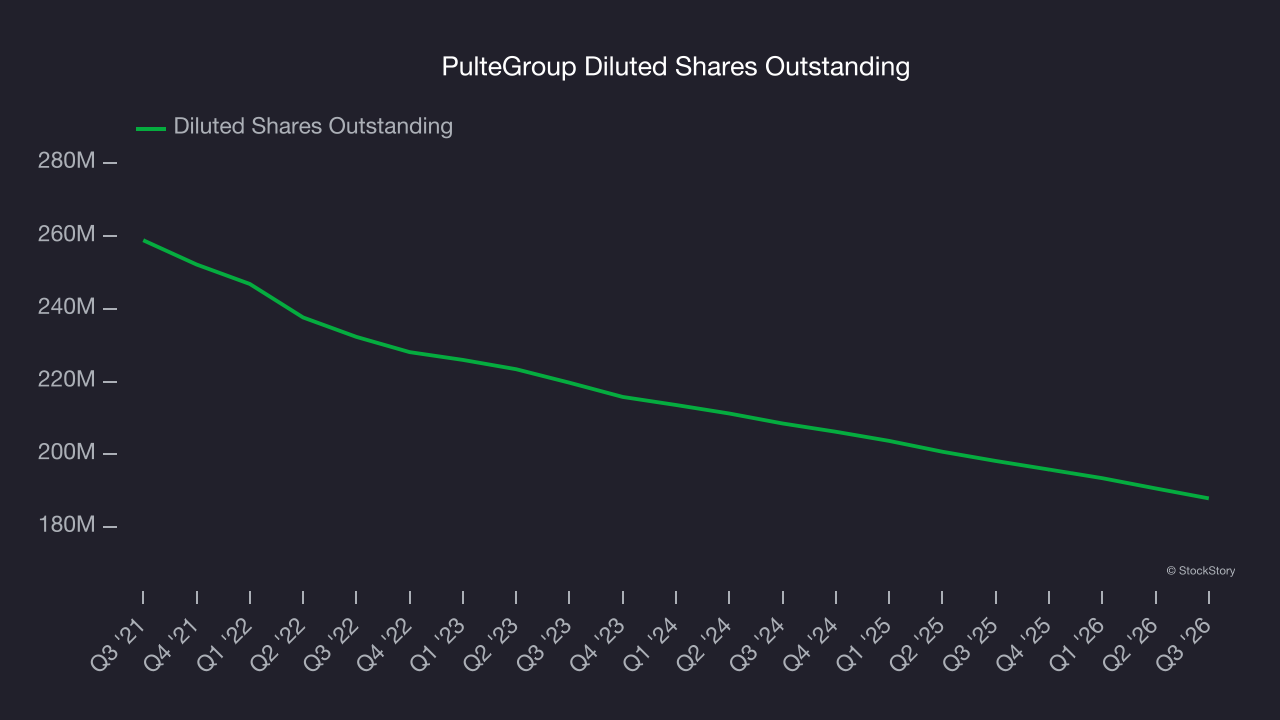
Like with revenue, we analyze EPS over a shorter period to see if we are missing a change in the business.
For PulteGroup, its two-year annual EPS declines of 17% show it’s continued to underperform. These results were bad no matter how you slice the data.
In Q3, PulteGroup reported EPS of $2.53, down from $2.96 in the same quarter last year. This print missed analysts’ estimates. Over the next 12 months, Wall Street expects PulteGroup’s full-year EPS to grow 13.4% from $9.36 to $10.61.
Key takeaways from PulteGroup’s Q3 results
We struggled to find many positives in these results. Its revenue missed and its EPS fell short of Wall Street’s estimates. Overall, this quarter could have been better. The stock traded down 7.1% to $104.89 immediately after reporting.
PulteGroup underperformed this quarter, but does that create an opportunity to invest right now? The latest quarter does matter, but not nearly as much as longer-term fundamentals and valuation, when deciding if the stock is a buy. We cover that in our actionable full research report which you can read here (it’s free).