Freight transportation company Norfolk Southern (NYSE: NSC) beat Wall Street’s revenue expectations in Q3 2026, with sales up 13.6% year on year to $3.53 billion. Its GAAP profit of $3.37 per share was 1.1% below analysts’ consensus estimates.
Is now the time to buy Norfolk Southern? Find out by accessing our full research report, it’s free.
Norfolk Southern (NSC) Q3 2026 highlights:
- Revenue: $3.53 billion vs analyst estimates of $3.47 billion (13.6% year-on-year growth, 1.7% beat)
- EPS (GAAP): $3.37 vs analyst expectations of $3.41 (1.1% miss)
- Operating Margin: 32.6%, down from 35.4% in the same quarter last year
- Free Cash Flow Margin: 20.9%, down from 23.2% in the same quarter last year
- Market Capitalization: $73.69 billion
Company overview
Starting with a single route from Virginia to North Carolina, Norfolk Southern (NYSE: NSC) is a freight transportation company operating a major railroad network across the eastern United States.
Revenue growth
Examining a company’s long-term performance can provide clues about its quality. Any business can put up a good quarter or two, but many enduring ones grow for years. Regrettably, Norfolk Southern’s sales grew at a sluggish 3.6% compounded annual growth rate over the last five years. This fell short of our benchmark for the industrials sector and is a poor baseline for our analysis.
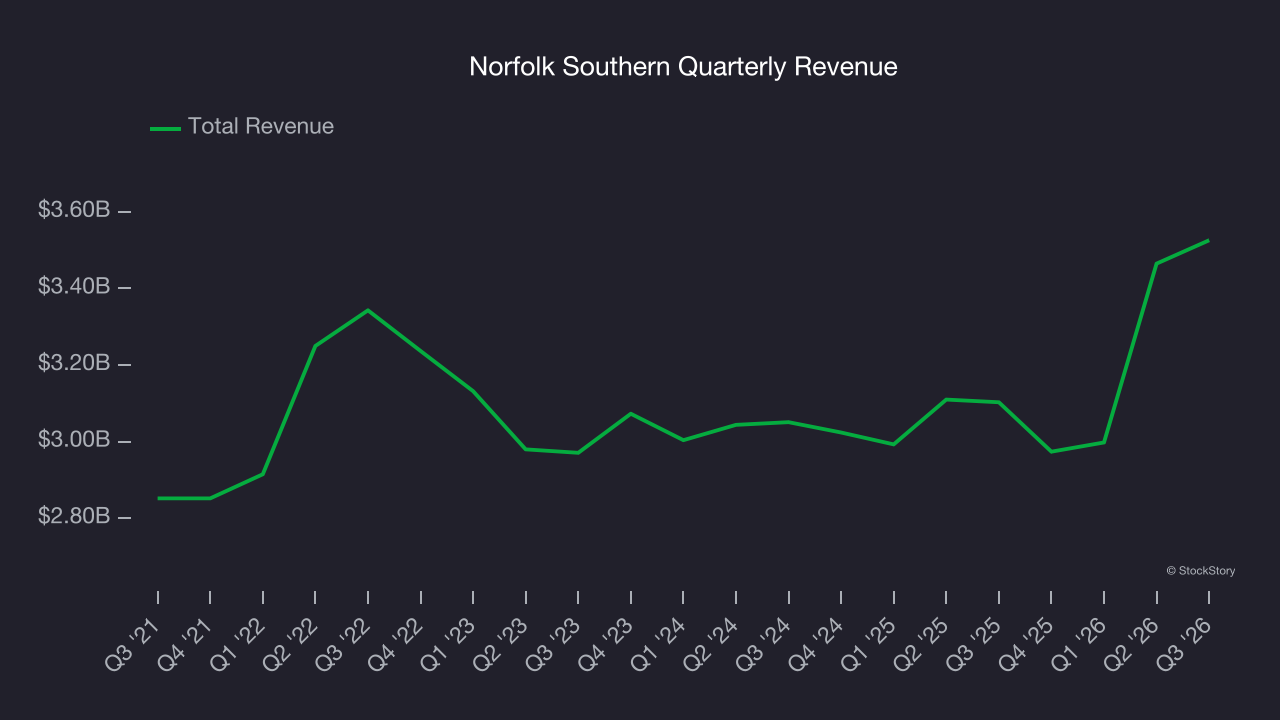
We at StockStory place the most emphasis on long-term growth, but within industrials, a half-decade historical view may miss cycles, industry trends, or a company capitalizing on catalysts such as a new contract win or a successful product line. Norfolk Southern’s annualized revenue growth of 3.2% over the last two years aligns with its five-year trend, suggesting its demand was consistently weak. 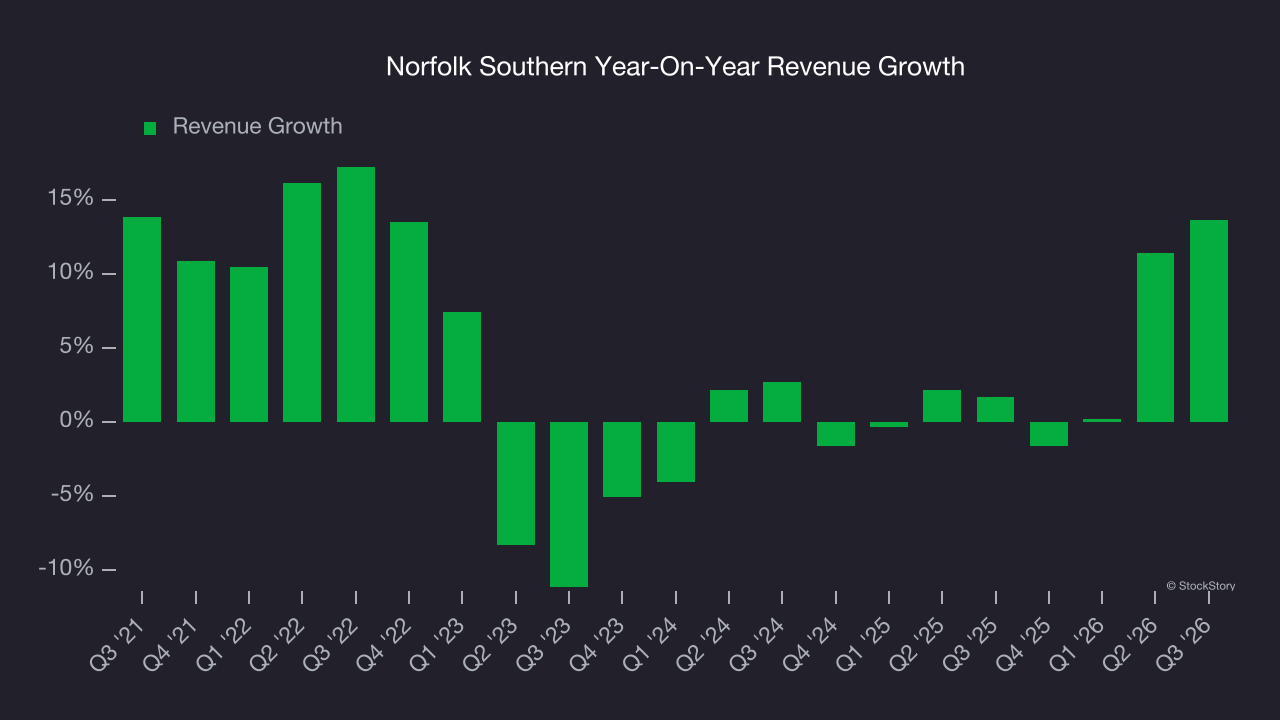
This quarter, Norfolk Southern reported year-on-year revenue growth of 13.6%, and its $3.53 billion of revenue exceeded Wall Street’s estimates by 1.7%.
Looking ahead, sell-side analysts expect revenue to grow 7.6% over the next 12 months, an improvement versus the last two years. This projection is above average for the sector and implies its newer products and services will catalyze better top-line performance.
WHILE YOU’RE HERE: The Next Palantir? One satellite company captures images of every point on Earth. Every single day. The Pentagon wants it. Hedge funds are using it to beat earnings. You’ve probably never heard of it.
This is what the early days of Palantir looked like before it became a giant. Same playbook. Different technology. If you missed Palantir, you need to see this. Claim The Stock Ticker for Free HERE.
Operating margin
Operating margin is an important measure of profitability as it shows the portion of revenue left after accounting for all core expenses — everything from the cost of goods sold to advertising and wages. It’s also useful for comparing profitability across companies with different levels of debt and tax rates because it excludes interest and taxes.
Norfolk Southern has been a well-oiled machine over the last five years. It demonstrated elite profitability for an industrials business, boasting an average operating margin of 32.8%. This result isn’t surprising as its high gross margin gives it a favorable starting point.
Analyzing the trend in its profitability, Norfolk Southern’s operating margin decreased by 7 percentage points over the last five years. This raises questions about the company’s expense base because its revenue growth should have given it leverage on its fixed costs, resulting in better economies of scale and profitability.
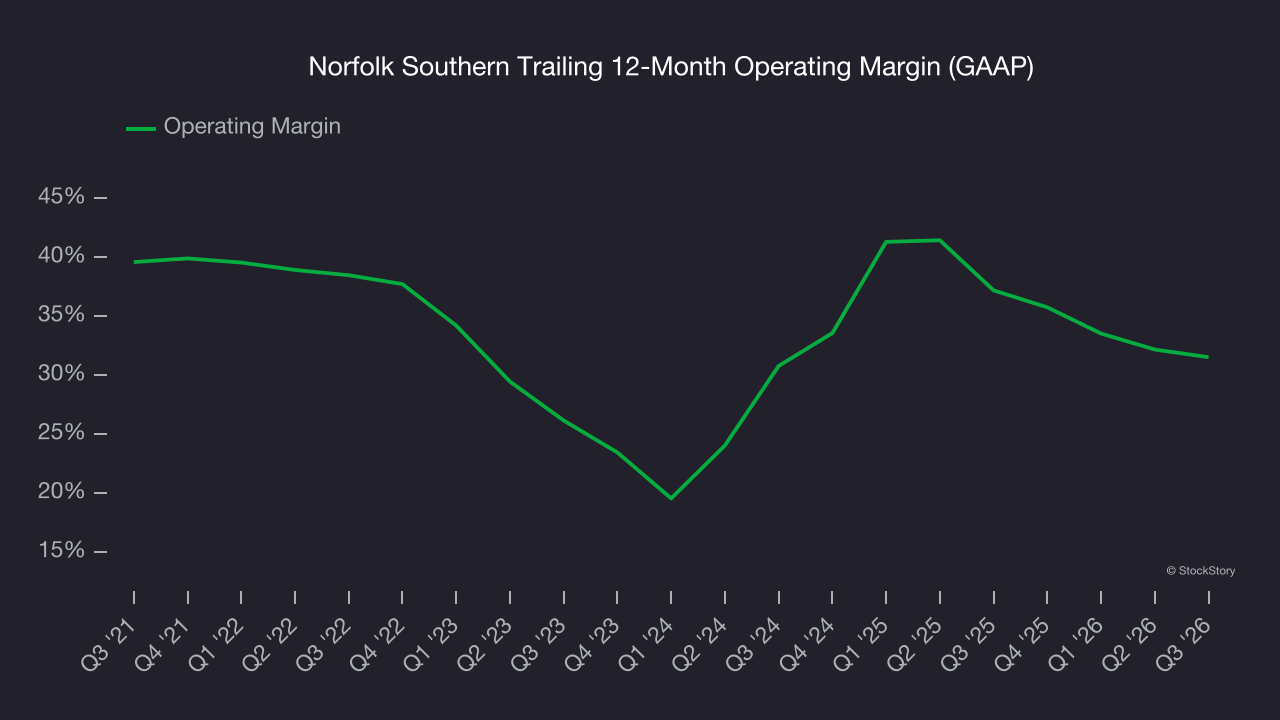
This quarter, Norfolk Southern generated an operating margin profit margin of 32.6%, down 2.8 percentage points year on year. Since Norfolk Southern’s gross margin decreased more than its operating margin, we can assume its recent inefficiencies were driven more by weaker leverage on its cost of sales rather than increased marketing, R&D, and administrative overhead expenses.
Earnings per share
We track the long-term change in earnings per share (EPS) for the same reason as long-term revenue growth. Compared to revenue, however, EPS highlights whether a company’s growth is profitable.
Norfolk Southern’s flat EPS over the last five years was below its 3.6% annualized revenue growth. This tells us the company became less profitable on a per-share basis as it expanded due to non-fundamental factors such as interest expenses and taxes.
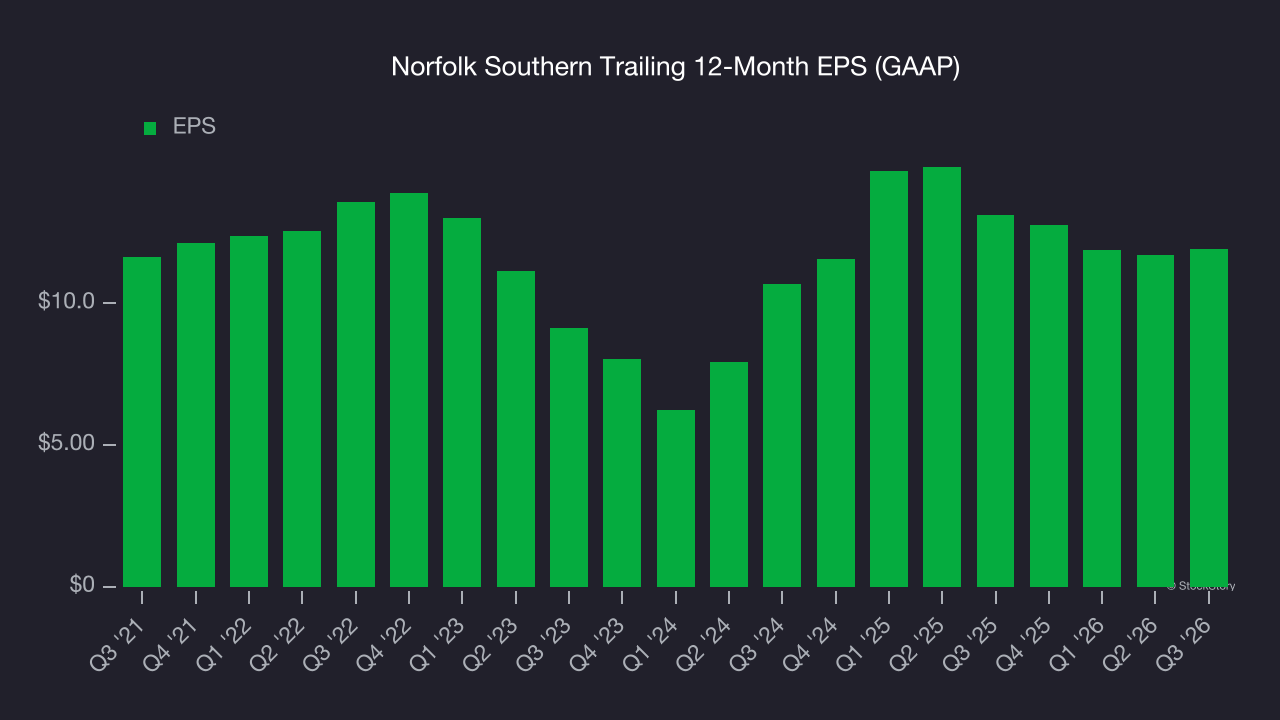
Diving into the nuances of Norfolk Southern’s earnings can give us a better understanding of its performance. As we mentioned earlier, Norfolk Southern’s operating margin declined by 7 percentage points over the last five years. This was the most relevant factor (aside from the revenue impact) behind its lower earnings; interest expenses and taxes can also affect EPS but don’t tell us as much about a company’s fundamentals.
Like with revenue, we analyze EPS over a more recent period because it can provide insight into an emerging theme or development for the business.
For Norfolk Southern, its two-year annual EPS growth of 5.7% was higher than its five-year trend. Accelerating earnings growth is almost always an encouraging data point.
In Q3, Norfolk Southern reported EPS of $3.37, up from $3.16 in the same quarter last year. Despite growing year on year, this print slightly missed analysts’ estimates. Over the next 12 months, Wall Street expects Norfolk Southern’s full-year EPS to grow 16.2% from $11.93 to $13.86.
Key takeaways from Norfolk Southern’s Q3 results
It was encouraging to see Norfolk Southern beat analysts’ revenue expectations this quarter. On the other hand, its EPS slightly missed. Overall, this print had some key positives. The market seemed to be hoping for more, and the stock traded down 2.1% to $321.18 immediately following the results.
Should you buy the stock or not? The latest quarter does matter, but not nearly as much as longer-term fundamentals and valuation, when deciding if the stock is a buy. We cover that in our actionable full research report which you can read here (it’s free).