Financial advisory firm Lazard (NYSE: LAZ) fell short of the market’s revenue expectations in Q3 2026, but sales rose 12.4% year on year to $814.2 million. Its non-GAAP profit of $0.36 per share was 13% below analysts’ consensus estimates.
Is now the time to buy Lazard? Find out by accessing our full research report, it’s free.
Lazard (LAZ) Q3 2026 highlights:
- Assets Under Management: $284 billion vs analyst estimates of $286.3 billion (7.4% year-on-year growth, 0.8% miss)
- Revenue: $814.2 million vs analyst estimates of $852.5 million (12.4% year-on-year growth, 4.5% miss)
- Pre-tax Profit: $54.75 million (6.7% margin)
- Adjusted EPS: $0.36 vs analyst expectations of $0.41 (13% miss)
- Market Capitalization: $3.64 billion
"Our Lazard 2030 strategy continues to progress as planned, with strong momentum firm-wide," said Peter R. Orszag, CEO and Chairman. "Financial Advisory delivered record third quarter revenue as the investments we have made in the business increasingly translate into results, while client activity and our forward indicators remain strong. In Asset Management, record year-to-date gross inflows reflect improving investment performance and focused distribution efforts. With our new private capital advisory business, Lazard CL, launching in early November, we are building a more productive, diversified firm positioned for long-term profitable growth."
Company overview
Tracing its roots back to 1848 when it began as a dry goods merchant in New Orleans, Lazard (NYSE: LAZ) is a global financial advisory and asset management firm that provides strategic advice to corporations, governments, institutions, and wealthy individuals.
Revenue growth
A company’s long-term sales performance can indicate its overall quality. Any business can experience short-term success, but top-performing ones enjoy sustained growth for years. Unfortunately, Lazard struggled to consistently increase demand as its $3.17 billion of revenue for the trailing 12 months was close to its revenue five years ago. This was below our standards and is a sign of poor business quality.
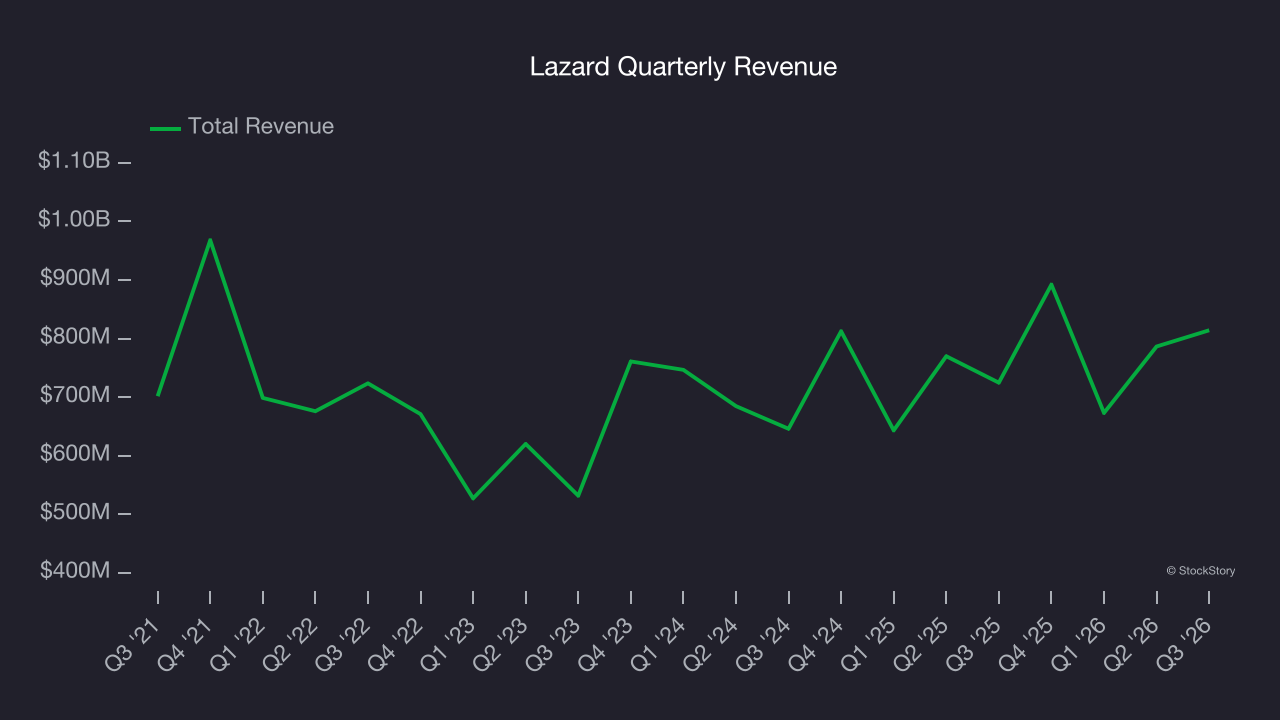
Long-term growth is the most important, but within financials, a half-decade historical view may miss recent interest rate changes and market returns. Lazard’s annualized revenue growth of 5.6% over the last two years is above its five-year trend, which is encouraging. 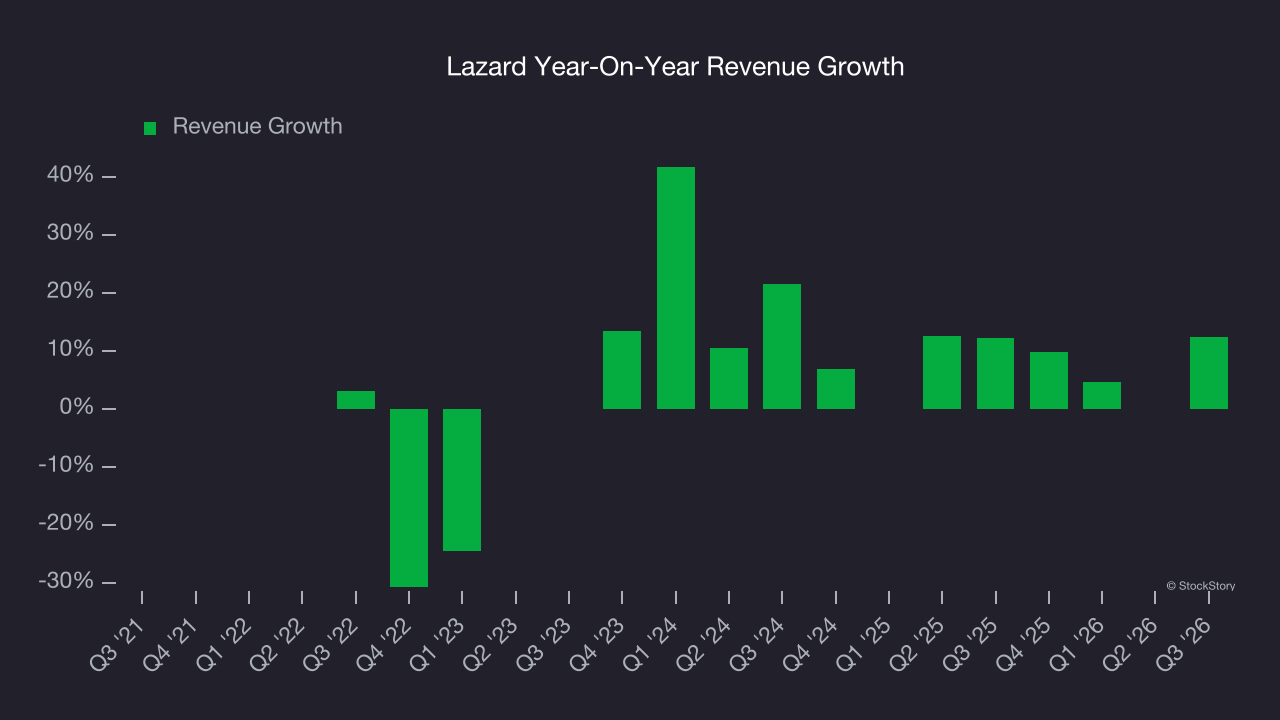 Note: Quarters not shown were determined to be outliers because they were impacted by outsized investment gains/losses that are not indicative of the recurring fundamentals of the business.
This quarter, Lazard’s revenue grew by 12.4% year on year to $814.2 million but fell short of Wall Street’s estimates.
ALSO WORTH WATCHING: Nvidia’s Quiet Partner. Nvidia’s chips cost a hundred grand. The connectors that make them work cost even more. One company makes them all.
Every AI server needs specialized infrastructure the chip companies don’t make. High-speed cables. Power connectors. Thermal sensors. This 90-year-old company built a monopoly on it. The AI boom just started. This stock is still flying under the radar. Claim The Stock Ticker Here for FREE.
Assets under management (AUM)
Assets Under Management (AUM) represents the total value of investments that a financial institution manages for its clients. These assets generate steady income through management fees, creating predictable revenue streams that remain stable so long as clients remain invested with the firm.
Lazard’s AUM was flat over the last five years, much worse than the broader financials industry and worse than its total revenue. When analyzing Lazard’s AUM over the last two years, we can see that growth accelerated to 4.6% annually. Fundraising or short-term investment performance was a net detractor to the company over this shorter period since assets grew slower than total revenue. Keep in mind that asset growth can be erratic and seasonal, so we don’t rely on it too heavily for our business quality analysis.
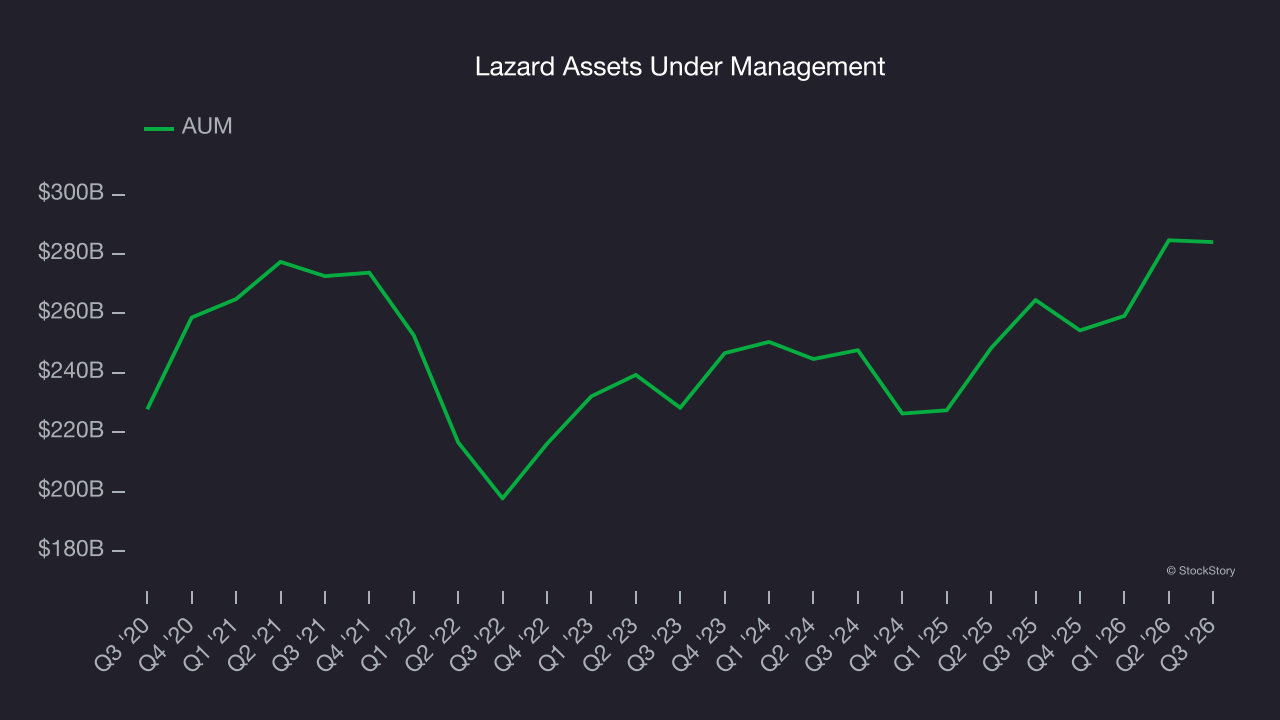
Lazard’s AUM punched in at $284 billion this quarter, falling 0.8% short of analysts’ expectations. This print was 7.4% higher than the same quarter last year.
Key takeaways from Lazard’s Q3 results
We struggled to find many positives in these results. Its revenue missed and its EPS fell short of Wall Street’s estimates. Overall, this was a weaker quarter. The stock remained flat at $37.66 immediately following the results.
Is Lazard an attractive investment opportunity right now? When making that decision, it’s important to consider its valuation, business qualities, as well as what has happened in the latest quarter. We cover that in our actionable full research report which you can read here (it’s free).