Water control and measurement company Badger Meter (NYSE: BMI) fell short of the market’s revenue expectations in Q3 2026, with sales flat year on year at $235.9 million. Its GAAP profit of $1.24 per share was 2.5% above analysts’ consensus estimates.
Is now the time to buy Badger Meter? Find out by accessing our full research report, it’s free.
Badger Meter (BMI) Q3 2026 highlights:
- Revenue: $235.9 million vs analyst estimates of $241.1 million (flat year on year, 2.1% miss)
- EPS (GAAP): $1.24 vs analyst estimates of $1.21 (2.5% beat)
- Operating Margin: 20.2%, in line with the same quarter last year
- Free Cash Flow Margin: 17.1%, down from 20.5% in the same quarter last year
- Market Capitalization: $3.82 billion
“We were pleased with our third quarter financial results delivering continued sequential sales and operating profit improvement,” said Kenneth C. Bockhorst, Chairman, President and Chief Executive Officer. “Consistent with our expectations, third quarter sales reflected the ongoing ramp of awarded utility water projects as well as solid underlying demand trends. I want to thank our employees across the globe for their commitment, contributions and ongoing customer focus.”
Company overview
The developer of the world’s first frost-proof water meter in 1905, Badger Meter (NYSE: BMI) provides water control and measure equipment to various industries.
Revenue growth
Reviewing a company’s long-term sales performance reveals insights into its quality. Any business can have short-term success, but a top-tier one grows for years. Luckily, Badger Meter’s sales grew at an excellent 12.8% compounded annual growth rate over the last five years. Its growth surpassed the average industrials company and shows its offerings resonate with customers, a great starting point for our analysis.
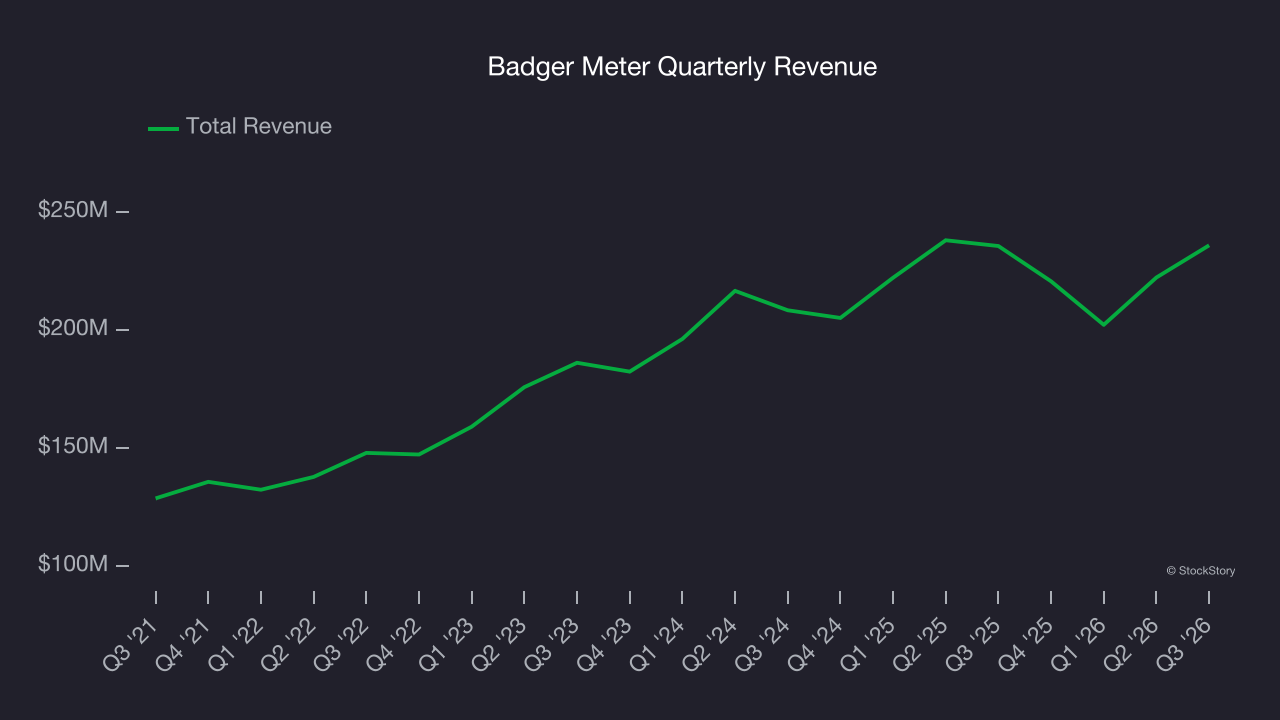
Long-term growth is the most important, but within industrials, a half-decade historical view may miss new industry trends or demand cycles. Badger Meter’s recent performance shows its demand has slowed significantly as its annualized revenue growth of 4.7% over the last two years was well below its five-year trend. 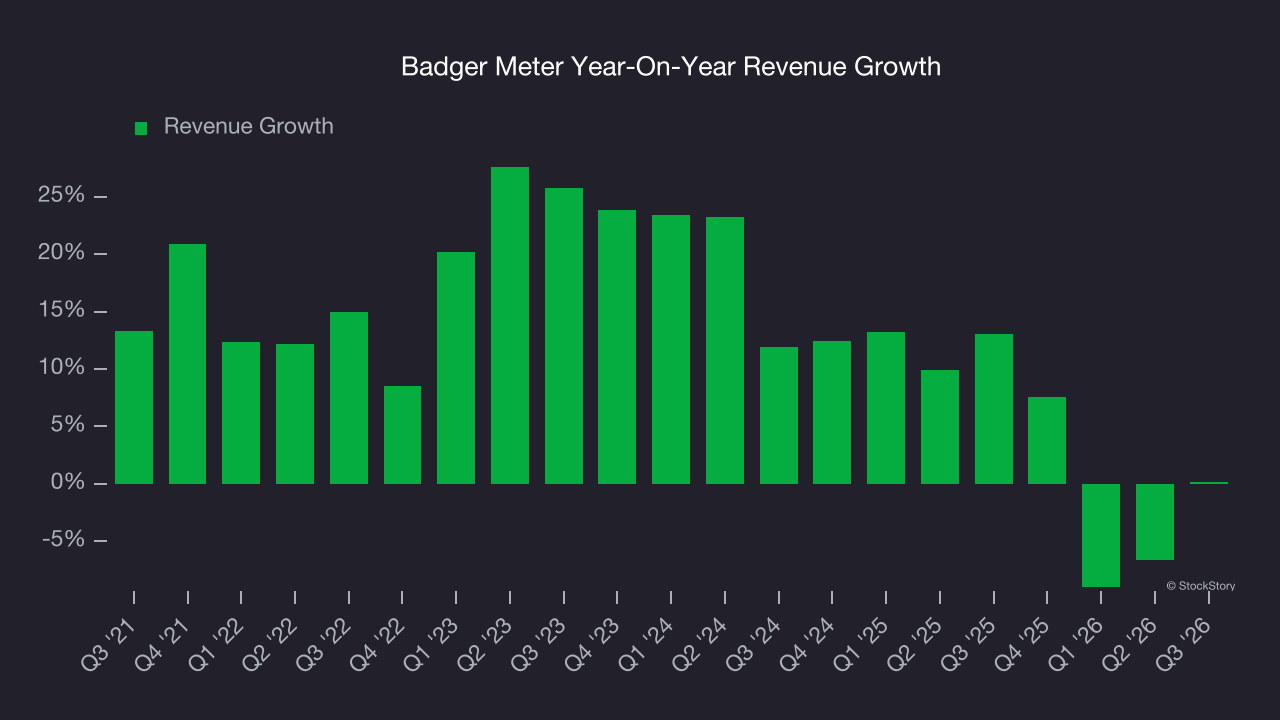
This quarter, Badger Meter’s $235.9 million of revenue was flat year on year, falling short of Wall Street’s estimates.
Looking ahead, sell-side analysts expect revenue to grow 10.4% over the next 12 months, an improvement versus the last two years. This projection is admirable and implies its newer products and services will catalyze better top-line performance.
ONE MORE THING: 3 Hidden Platforms Growing 3X Faster than Amazon, Google, and PayPal. Amazon, Google, and Meta all followed the same playbook: Dominate an ignored market. Build an unbeatable moat. Scale until you’re unstoppable.
These three platforms are running that exact playbook right now. The early investors in Amazon made fortunes. The early investors in these could do the same. Get All 3 Stocks Here for FREE.
Operating margin
Badger Meter has been a well-oiled machine over the last five years. It demonstrated elite profitability for an industrials business, boasting an average operating margin of 18.2%. This result isn’t surprising as its high gross margin gives it a favorable starting point.
Looking at the trend in its profitability, Badger Meter’s operating margin rose by 2.9 percentage points over the last five years, as its sales growth gave it operating leverage.
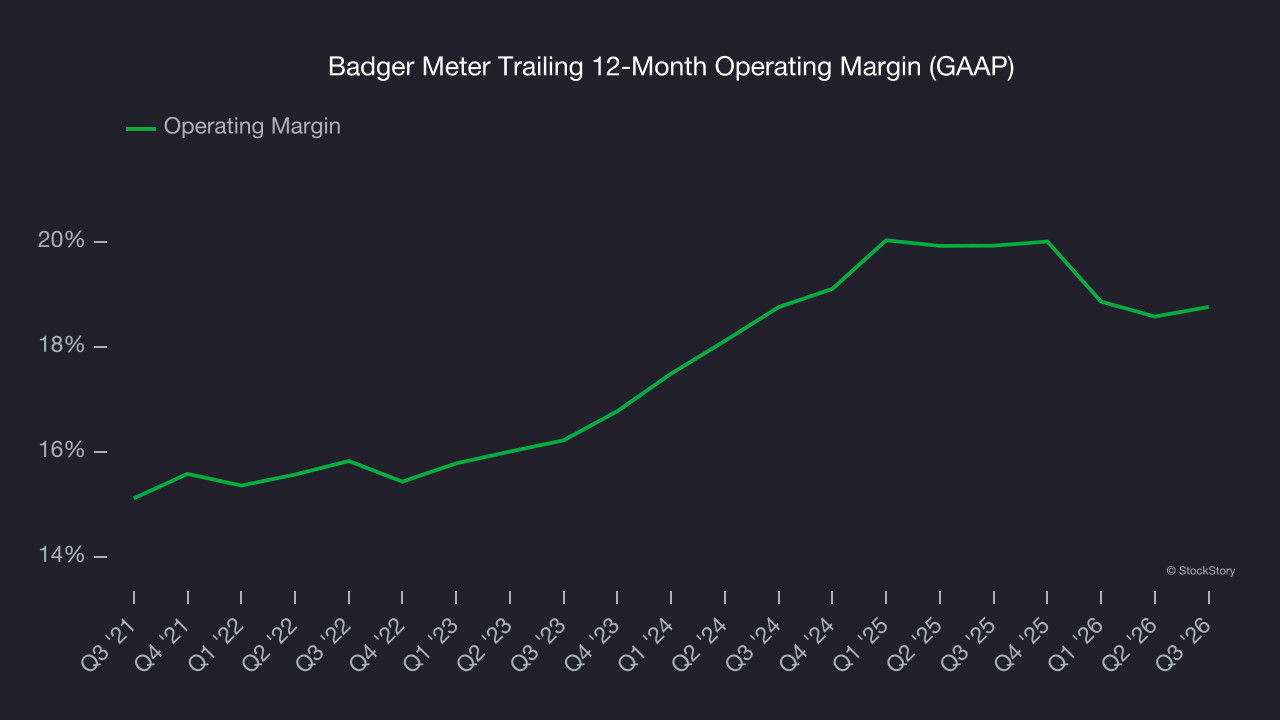
In Q3, Badger Meter generated an operating margin profit margin of 20.2%, in line with the same quarter last year. This indicates the company’s cost structure has recently been stable.
Earnings per share
We track the long-term change in earnings per share (EPS) for the same reason as long-term revenue growth. Compared to revenue, however, EPS highlights whether a company’s growth is profitable.
Badger Meter’s EPS grew at 17.5% compounded annual growth rate over the last five years, higher than its 12.8% annualized revenue growth. This tells us the company became more profitable on a per-share basis as it expanded.
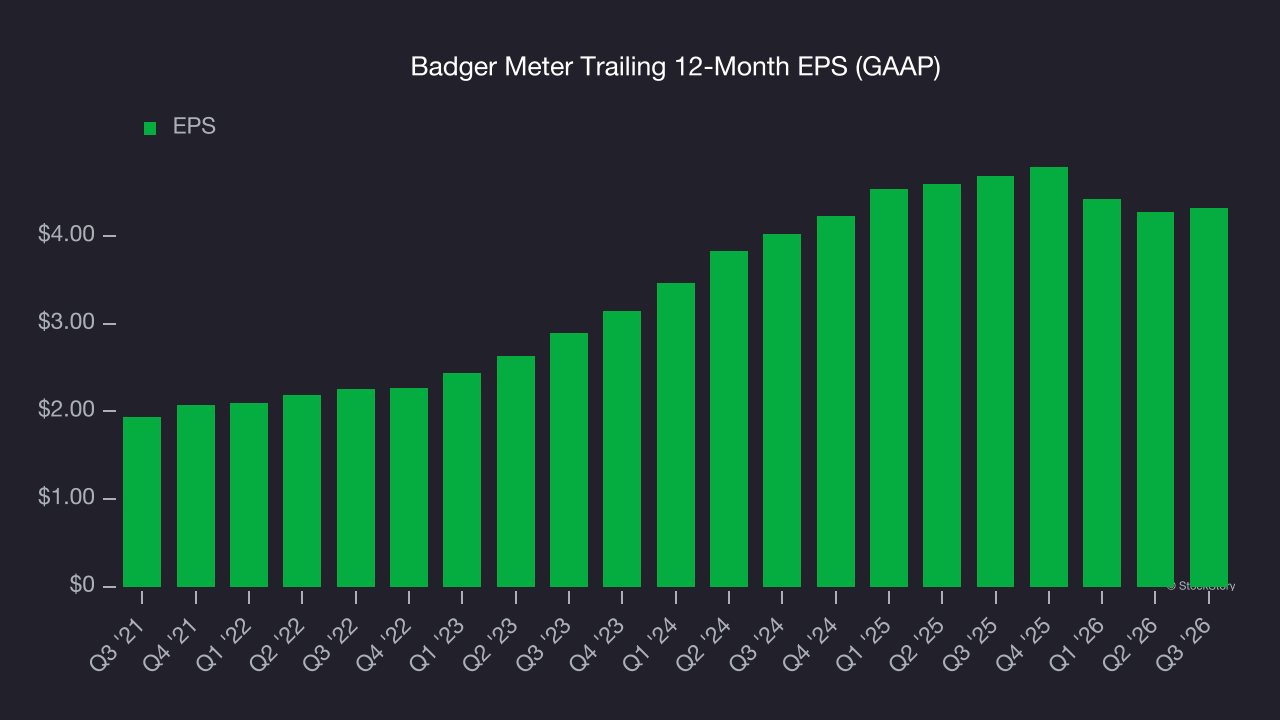
We can take a deeper look into Badger Meter’s earnings quality to better understand the drivers of its performance. As we mentioned earlier, Badger Meter’s operating margin was flat this quarter but expanded by 2.9 percentage points over the last five years. On top of that, its share count shrank by 1.6%. These are positive signs for shareholders because improving profitability and share buybacks turbocharge EPS growth relative to revenue growth. 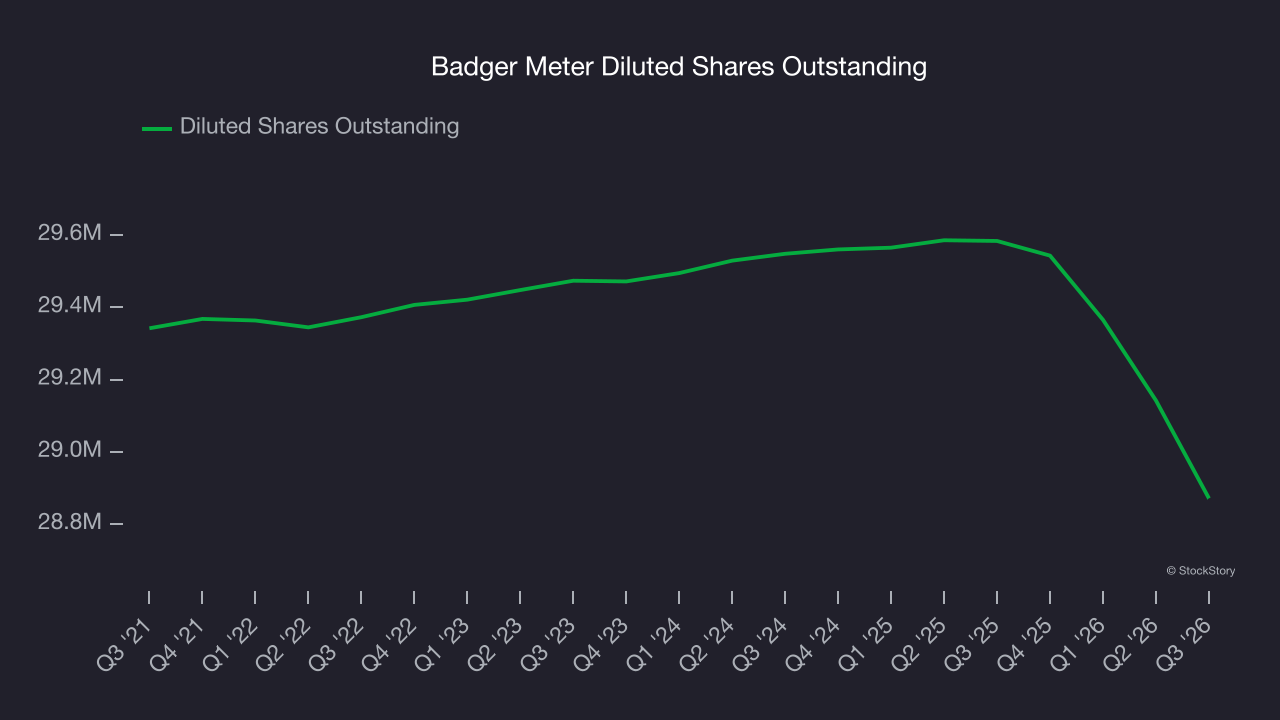
Like with revenue, we analyze EPS over a shorter period to see if we are missing a change in the business.
For Badger Meter, its two-year annual EPS growth of 3.6% was lower than its five-year trend. This wasn’t great, but at least the company was successful in other measures of financial health.
In Q3, Badger Meter reported EPS of $1.24, up from $1.19 in the same quarter last year. This print beat analysts’ estimates by 2.5%. Over the next 12 months, Wall Street expects Badger Meter’s full-year EPS to grow 13.9% from $4.33 to $4.93.
Key takeaways from Badger Meter’s Q3 results
Although EPS beat, revenue missed. Overall, this quarter could have been better. The stock traded down 5.7% to $124.69 immediately following the results.
Badger Meter didn’t show its best hand this quarter, but does that create an opportunity to buy the stock right now? We think that the latest quarter is only one piece of the longer-term business quality puzzle. Quality, when combined with valuation, can help determine if the stock is a buy. We cover that in our actionable full research report which you can read here (it’s free).