On average, yes.
The World Bank's Q3 2025 data puts the global bank average at 14.99% total cost on a $200-equivalent transfer, while the digital-only MTO index sits at 3.54%. That's a four-to-one ratio on the same service category.
But "on average" conceals a lot of variation, and "cheaper" depends on which costs you're counting. Here are five specific charges determine what the recipient actually get:
- The flat transfer fee that shows up on your receipt
- The exchange rate markup that may not show up
- Correspondent and intermediary deductions that happen in transit
- Payment method surcharges that change based on how you fund the transfer
- Receiving-side charges at the destination bank
Let’s explore each:
What the flat fee tells you (and what it doesn't)
UK banks charge a wide range for outgoing international transfers.
Barclays waives the fee for app and online banking payments but charges £25 by phone or in-branch. HSBC charges £5 from a standard account and £0 from a Global Money account.
Lloyds charges £9.50 for non-euro payments. NatWest's current terms say most standard online international payments are free, with £15 applying to urgent transfers. Remittance apps vary too. Wise currently shows fees ranging from roughly £6 to over £20 on a £1,000 UK-to-Pakistan transfer depending on whether you fund by bank transfer or debit card.
Others, such as Canada-based RemitBee, waive the flat fee entirely on qualifying transfers and charge only through the exchange rate margin.
Since several UK banks now offer £0-fee online transfers (Barclays and NatWest among them), the fee line alone doesn't decide the comparison. A few things the flat fee won't tell you.
● Whether the exchange rate includes a margin on top of the mid-market rate
● Whether intermediary banks will deduct charges in transit
● Whether the recipient's bank applies its own fee on arrival
Where the exchange rate margin fits
When a bank or app converts your pounds into another currency, the rate applied is usually different from the mid-market rate you'd see on XE or Google.
That gap is the exchange rate margin, and it can be a substantial cost component, especially on larger transfers.
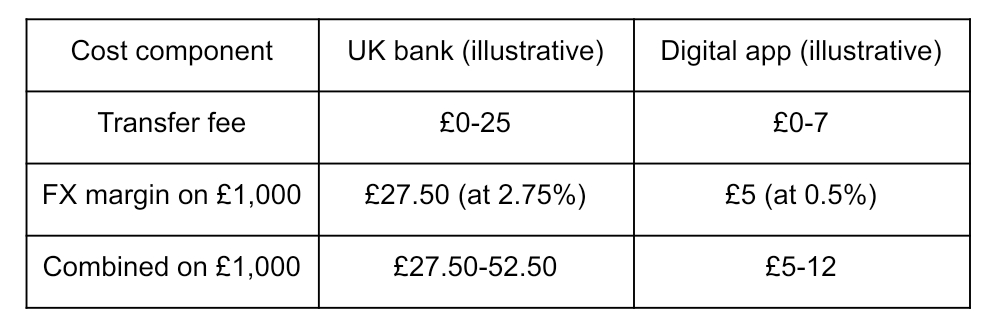
Published UK bank margins vary. Barclays caps its conversion charge at 2.75% for personal customers, with rates typically better on higher-value transactions.
Lloyds publishes a 3.55% margin on amounts up to £10,000, tapering above that. NatWest says its margin varies by amount but will not exceed 2.75%.
The World Bank's Q3 2025 report notes that transfer fees account for a large portion of remittance costs globally. In most displayed regional breakdowns for digital services, the fee component actually exceeds the FX margin.
So the markup isn't automatically the dominant cost — but on larger transfers where the flat fee shrinks as a percentage of the amount, the margin's share of the total grows.
Some providers handle this differently. Wise uses the mid-market rate with zero markup and charges a separate explicit fee.
Others embed a published margin but waive the flat fee.
The structure matters less than the total, which is why comparing the final recipient amount is more useful than comparing any single cost line.
What correspondent fees take in transit
Bank wires that move through the SWIFT network may pass through one or more intermediary banks, each of which can deduct a handling charge before forwarding the funds.
The sender's bank often can't predict the exact amount deducted in advance.
Lloyds publishes an optional correspondent-bank fee for senders who want the recipient to receive the full amount:
- Zone 1 (USA, Canada, non-EEA Europe) adds £12 on top of the £9.50 transfer fee
- Zone 2 (rest of the world) adds £20, bringing the pre-FX total to £29.50
Many remittance apps use local payout networks on common corridors, which can avoid traditional correspondent deductions.
But "can" isn't "always" — some apps still use SWIFT on certain routes.
Check whether your provider discloses intermediary charges for the specific corridor you're using.
How the payment method changes the price
Funding a transfer by bank transfer (Faster Payment or direct debit) is almost always cheaper than paying by card. The cost differences within a single provider can be striking.
● Bank transfer funding is typically the cheapest option
● Credit card funding, where accepted, tends to be the most expensive
● Debit card funding often carries a noticeably higher fee at the same provider
● Your card issuer may treat a money transfer as a cash advance, triggering interest from the transaction date
The quoted price on a comparison page sometimes assumes the cheapest funding method. If you switch to a card at checkout, the cost can jump.
Compare using the funding method you actually plan to use.
What the receiving bank charges on arrival
The final deduction happens at the other end.
The recipient's bank may apply an inward remittance processing fee, a currency conversion margin, or both, depending on how the funds arrive and in what currency.
Transfers settled directly in local currency through a provider's payout network tend to avoid the recipient-bank FX conversion.
Funds arriving via SWIFT in a foreign currency are more likely to face both a flat receiving fee and a conversion spread.
A safe money transfer provider that displays the guaranteed recipient amount in local currency before you confirm helps reduce this uncertainty, provided the displayed figure is genuinely net of all deductions.
What the total comparison comes down to
Stacking all five costs changes the picture. A Lloyds non-euro wire at £9.50 plus a 3.55% margin plus a £20 Zone 2 correspondent fee reaches roughly £65 on a £1,000 transfer.
A digital provider quoting £0 fee and a 0.5% margin totals about £5, assuming no intermediary or receiving-side charges apply.
Whether you're comparing providers for a money transfer to India from Canada or from London to Lagos, the five-cost framework is the same.
● Fee
● Margin
● Receiving-side charges
● Intermediary deductions
● Funding method surcharge
Compare the amount that actually lands in the recipient's account. That figure tells you more than any single line on the receipt.