Not all profitable companies are built to last - some rely on outdated models or unsustainable advantages. Just because a business is in the green today doesn’t mean it will thrive tomorrow.
Profits are valuable, but they’re not everything. At StockStory, we help you identify the companies that have real staying power. Keeping that in mind, here is one profitable company that balances growth and profitability and two that may face some trouble.
Two Stocks to Sell:
Genco (GNK)
Trailing 12-Month GAAP Operating Margin: 19.1%
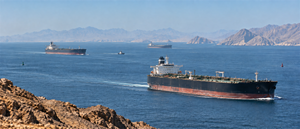
Headquartered in NYC, Genco (NYSE: GNK) is a shipping company that transports dry bulk cargo along worldwide maritime routes.
Why Is GNK Risky?
- Demand for its offerings was relatively low as its number of owned vessels has underwhelmed
- Performance over the past two years shows its incremental sales were less profitable as its earnings per share were flat
- Capital intensity has ramped up over the last five years as its free cash flow margin decreased by 81.8 percentage points
At $27.99 per share, Genco trades at 12.1x forward P/E. Dive into our free research report to see why there are better opportunities than GNK.
Forestar Group (FOR)
Trailing 12-Month GAAP Operating Margin: 12.6%
As a majority-owned subsidiary of homebuilding giant D.R. Horton, Forestar Group (NYSE: FOR) develops and sells finished residential lots to homebuilders, focusing primarily on land acquisition and development for single-family homes.
Why Should You Sell FOR?
- Products are seeing elevated demand as its number of lots sold averaged -18.6% growth over the past two years
- Cash-burning tendencies make us wonder if it can sustainably generate shareholder value
- Shrinking returns on capital from an already weak position reveal that neither previous nor ongoing investments are yielding the desired results
Forestar Group’s stock price of $25.97 implies a valuation ratio of 9.2x forward P/E. To fully understand why you should be careful with FOR, check out our full research report (it’s free).
One Stock to Watch:
Mueller Water Products (MWA)
Trailing 12-Month GAAP Operating Margin: 19.4%
As one of the oldest companies in the water infrastructure industry, Mueller (NYSE: MWA) is a provider of water infrastructure products and flow control systems for various sectors.
Why Does MWA Stand Out?
- Operating margin expanded by 8.9 percentage points over the last five years as it scaled and became more efficient
- Incremental sales over the last two years have been highly profitable as its earnings per share increased by 29.2% annually, topping its revenue gains
- Free cash flow margin jumped by 12.1 percentage points over the last five years, giving the company more resources to pursue growth initiatives, repurchase shares, or pay dividends
Mueller Water Products is trading at $22.16 per share, or 14.2x forward P/E. Is now the right time to buy? See for yourself in our comprehensive research report, it’s free.
Stocks We Like Even More
ONE MORE THING: Top 5 Growth Stocks. The biggest stock winners almost always had one thing in common before they ran. Revenue growing like crazy. Meta. CrowdStrike. Broadcom. Our AI flagged all three. They returned 315%, 314%, and 455%, respectively.
Find out which 5 stocks it’s flagging this month — FREE. Get Our Top 5 Growth Stocks for Free HERE.
Stocks that made our list in 2020 include now familiar names such as Nvidia (+1,460% between June 2020 and June 2025) as well as under-the-radar businesses like the once-micro-cap company Kadant (+214% between June 2020 and June 2025). Find your next big winner with StockStory today.